Converting a US Dime to Indian Rupees Isn't as Simple as You'd Think
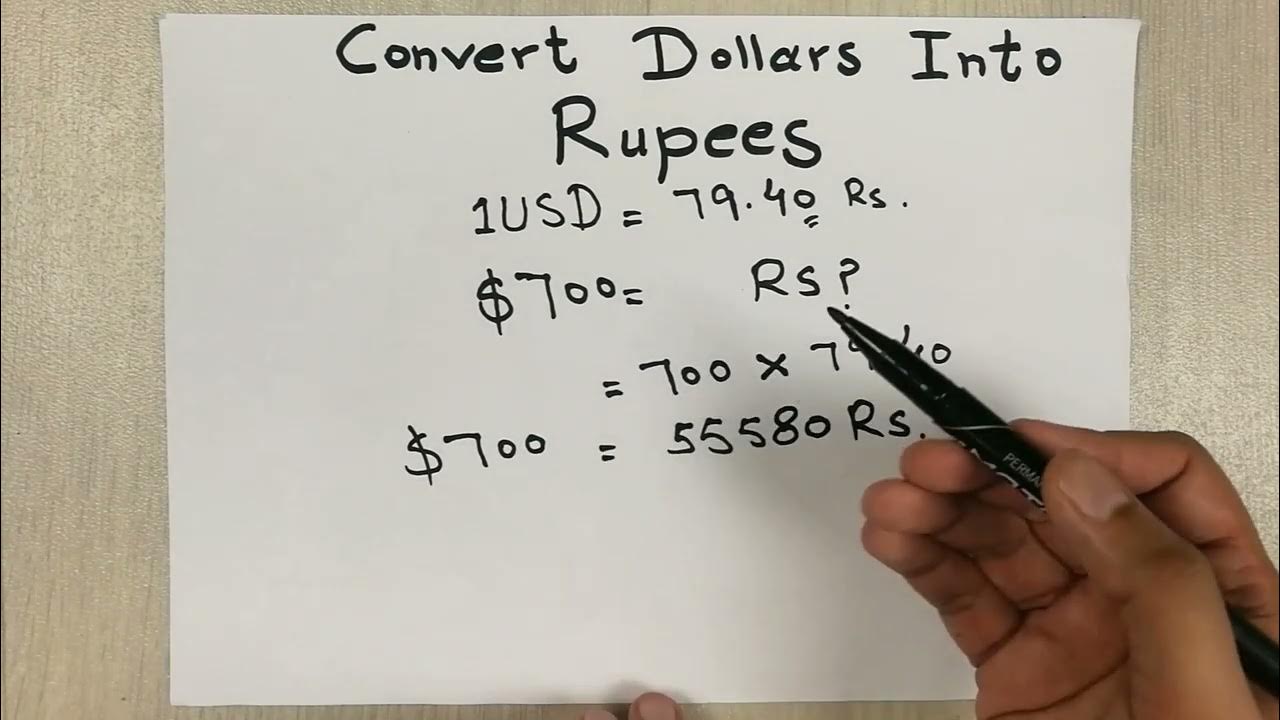
Most people grab their phone and throw the numbers into a converter app, but the actual process involves a few details that get glossed over. The basic math: take the USD to INR exchange rate, divide by 100, and you have your answer for a single dime. If the rate is 83.50, then one dime equals 8.35 rupees. That's it. The part nobody warns you about is that this number shifts constantly, and the rate you see on Google is not the rate you actually get unless you're doing a purely academic calculation. I ran into this problem last year when someone sent me a batch of US coin payments through a remittance service that accepted physical currency. The app showed one dime as roughly 8.30 rupees, but when I actually processed the transaction, the credited amount came out to about 7.90 rupees per dime. The gap wasn't rounding. It was the spread. The service was quoting the mid-market rate but charging a hidden margin on the buy side, which on small denominations like dimes eats into the value noticeably more than you'd expect. My workaround was straightforward. I stopped using the converter's displayed rate as my benchmark and instead pulled the raw forex rate from a platform like OANDA orXE before initiating the transfer, then cross-checked what the service actually quoted. If the difference was more than half a percent, I switched providers. For a single dime the savings are negligible, but when you're converting a stack of them it adds up fast. A roll of dimes is forty cents, and at a typical 2 percent spread you'd lose around 1.60 rupees per roll compared to the mid-market rate.
The deeper issue here is that most consumer-facing converters only show you the wholesale rate. They don't display the spread, the processing fee, or the minimum transfer threshold that might force you to convert in chunks. When I was doing regular conversions for a friend's family back in India, I learned to track the effective rate after all fees rather than getting fixated on the headline number. A service might advertise "zero fees" but build a 3 percent spread into the rate itself, which on small amounts like a dime is actually worse than charging a flat conversion fee. Another thing that trips people up is the timing. Forex rates move throughout the trading day, and while a single dime won't make or break you on a bad conversion, if you're converting regularly the day of the week matters more than you'd think. Monday mornings tend to have wider spreads as markets adjust to the weekend, and Friday afternoons can see similar volatility as traders close positions. I started scheduling my conversions around Wednesday midday when spreads typically tighten, and over a year of monthly transfers that small adjustment saved me enough to notice without being dramatic about it. If you need real-time accuracy, the most reliable approach is to check the rate on a proper forex terminal or your bank's foreign exchange page rather than a search engine result. Google shows a snapshot from an aggregator, not the actual executable rate. And if you're converting larger volumes of small-denomination coins through a service, always ask what the all-in effective rate is before committing. The published rate is just the starting point, not the final number.