Calculating Net Working Capital Before You Panic About Cash Flow
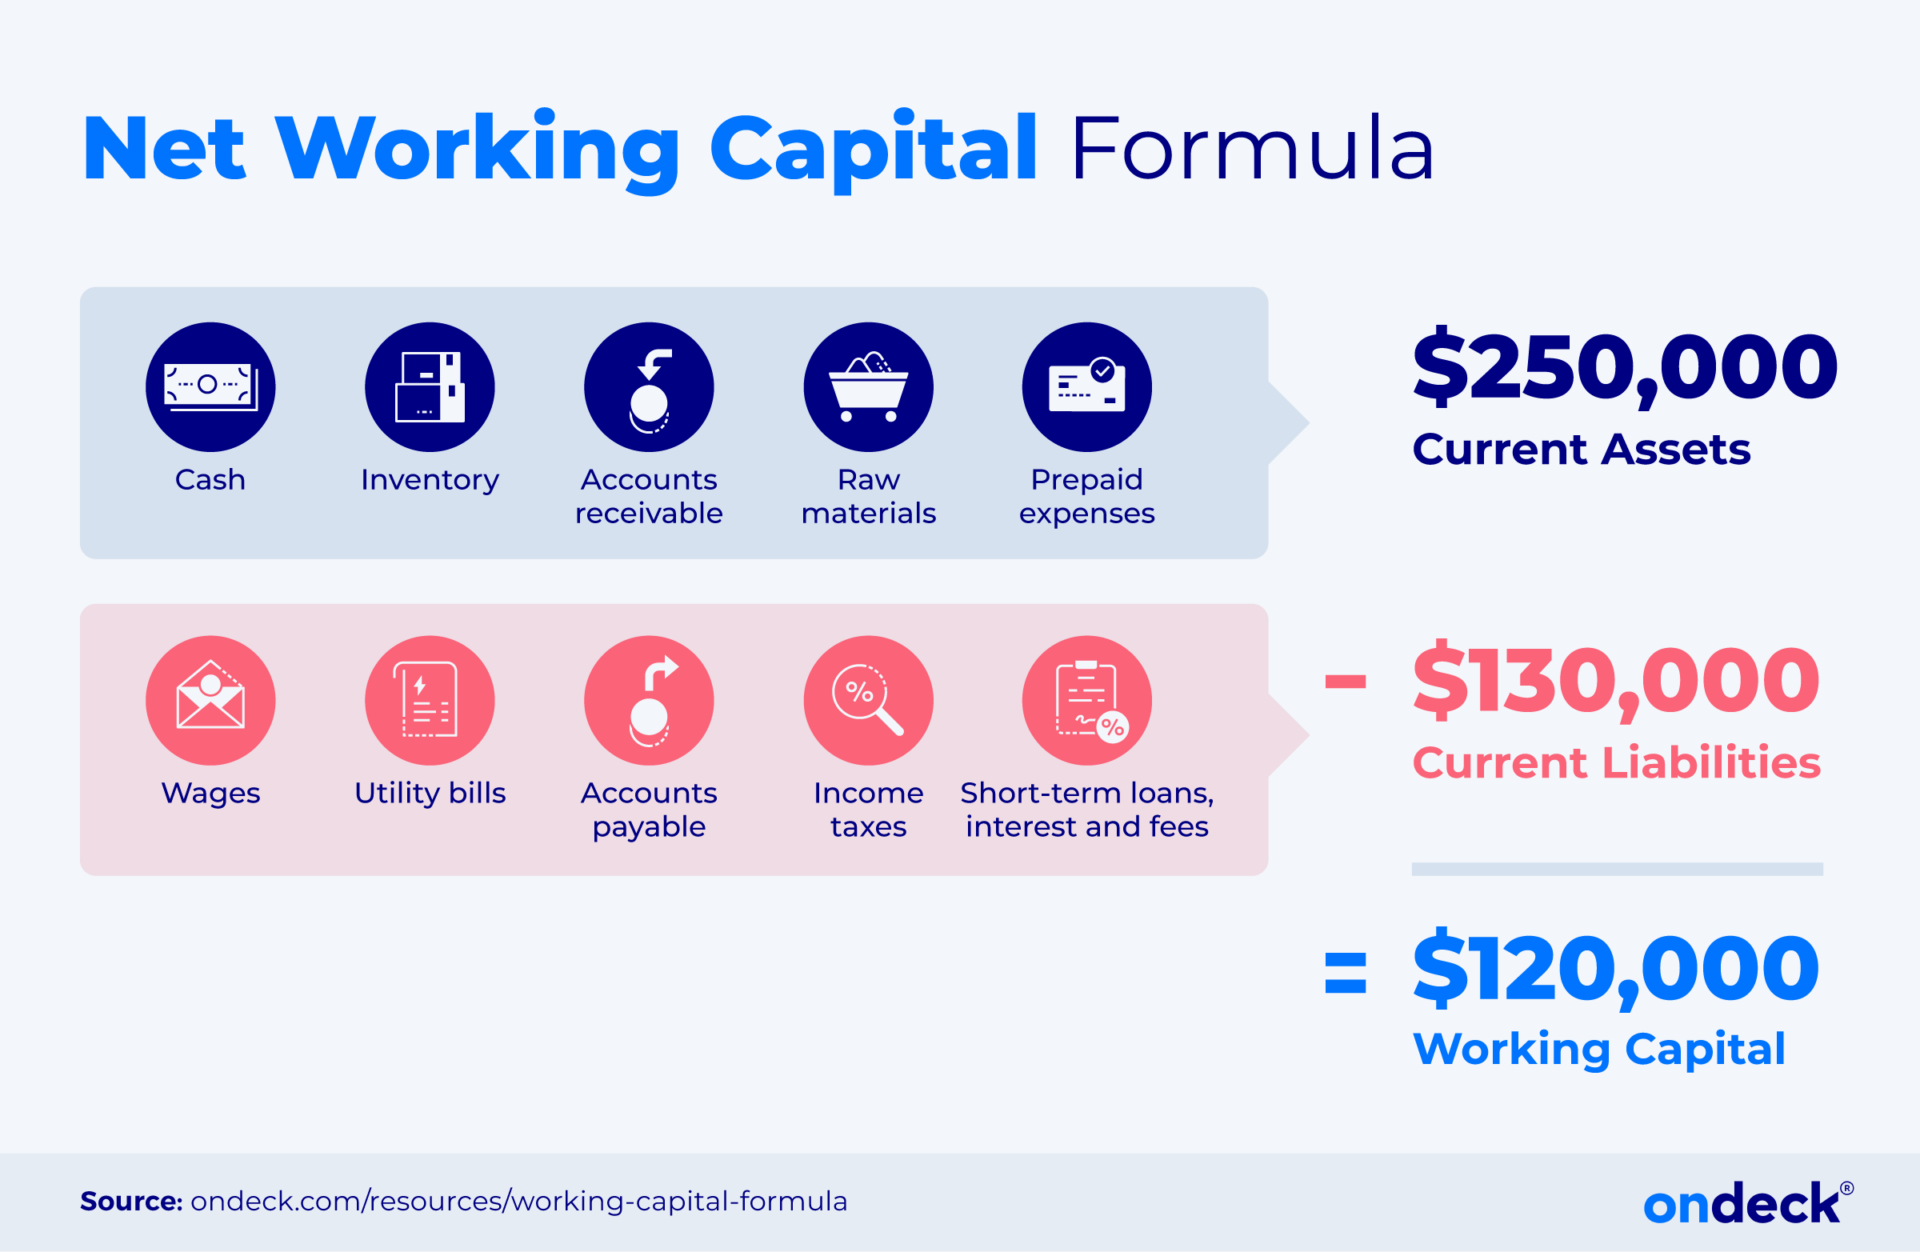
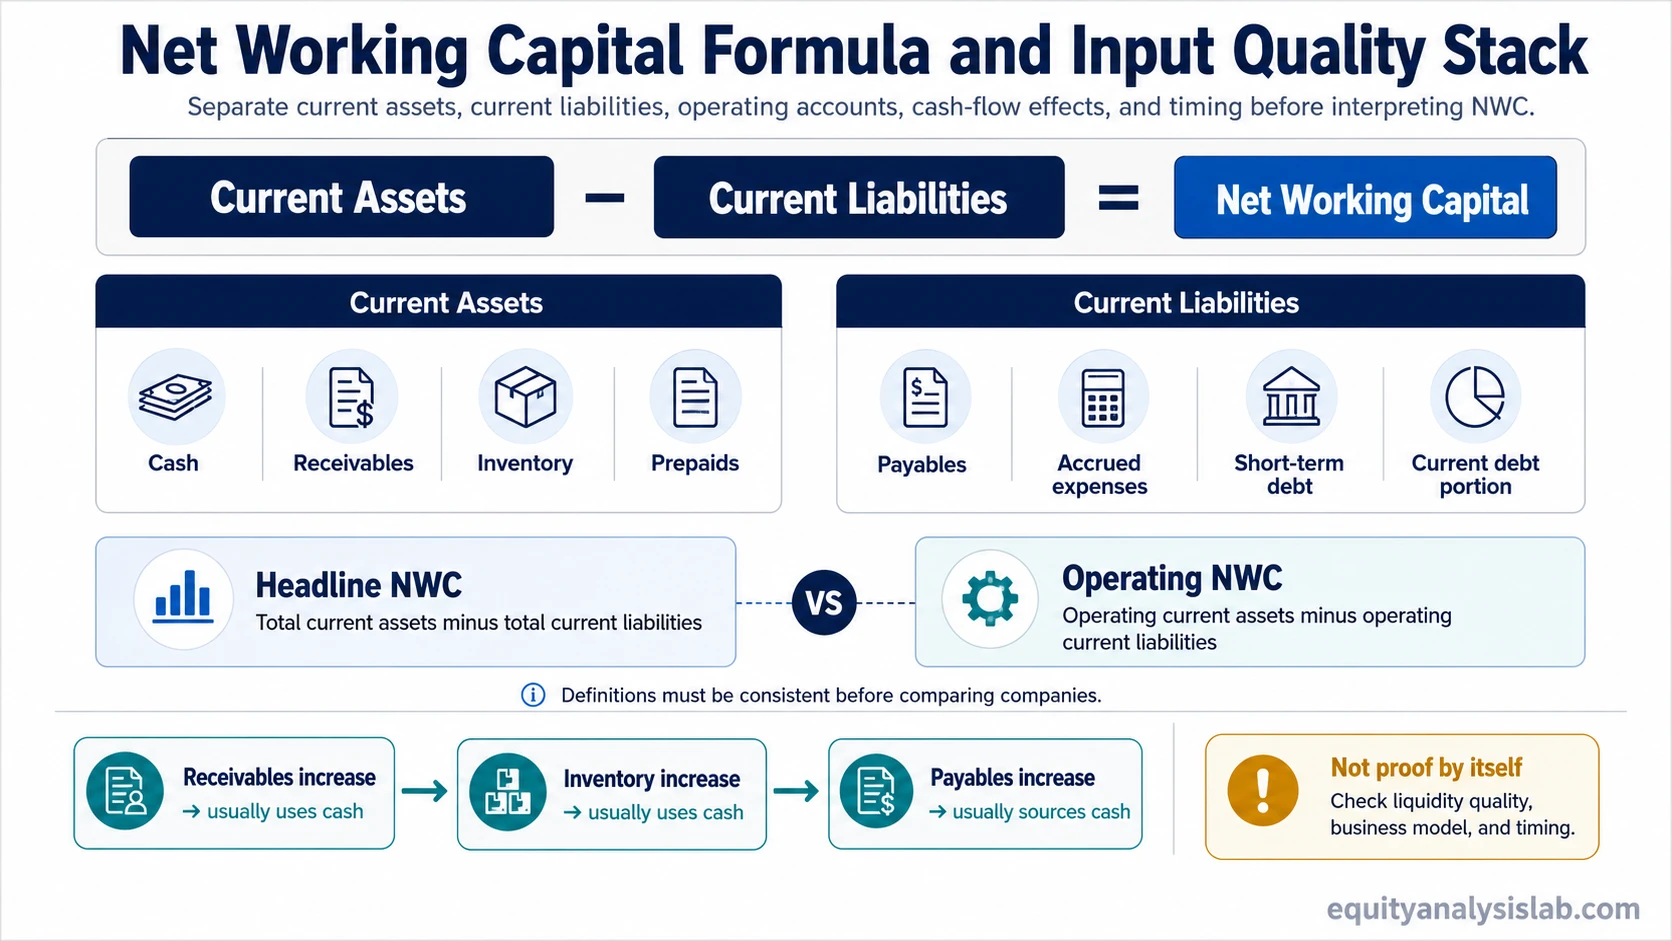
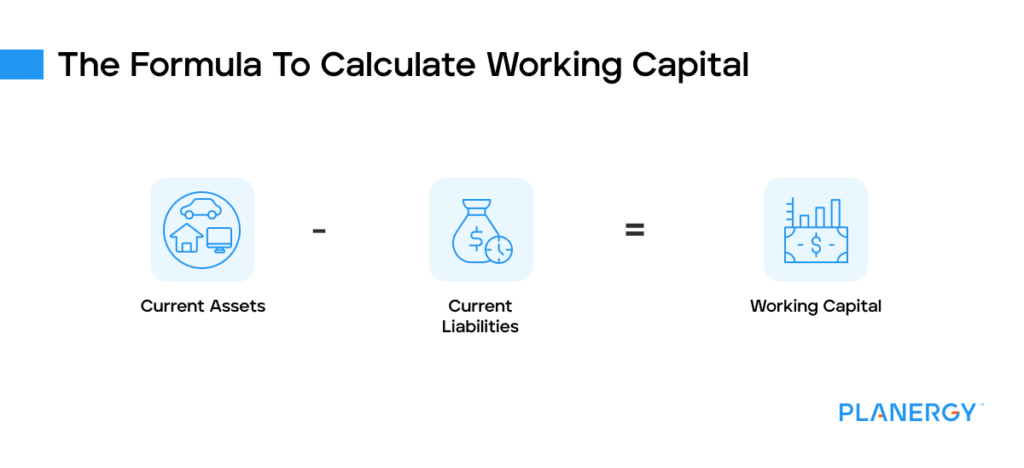
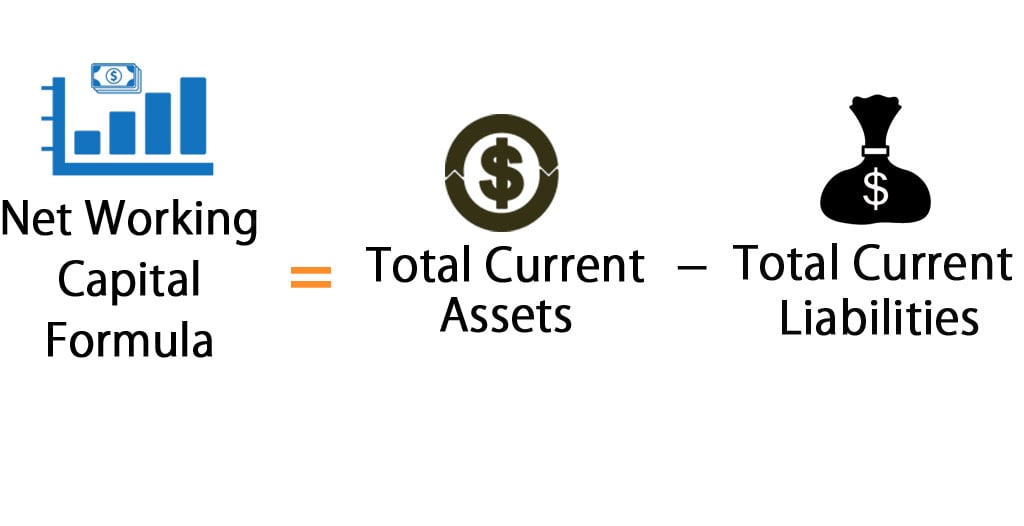
Most people figure out they need to track working capital the same week their accounts payable goes unpaid and the bank calls about an overdraft. I learned this the hard way in 2019 when a manufacturing client of mine had $400,000 in revenue on paper but couldn't make payroll. His balance sheet said he was fine. His bank account said otherwise. The gap between those two numbers was a working capital problem he hadn't been measuring. The formula itself is simple enough that you can write it on a napkin. Current assets minus current liabilities equals net working capital. That's it. But the reason this number matters has less to do with arithmetic and more to do with what sits inside each bucket. Most business owners add up cash, receivables, and inventory without checking whether those figures are current, collectible, or moving at all. Current assets are things you can convert to cash within one year. That includes cash and cash equivalents, accounts receivable, inventory, prepaid expenses, and short-term investments. Current liabilities are obligations due within the same window: accounts payable, short-term debt, accrued expenses, taxes owed, and the current portion of long-term debt. The difference between them tells you whether you have breathing room or a ticking clock.
I've seen people mistake inventory for liquidity. It's not, not really, unless you can sell it. In my client's case, his balance sheet showed $600,000 in inventory, which made his working capital look healthy at first glance. But half of that was obsolete components from a product line discontinued two years earlier. Once I adjusted for that, his real working capital dropped from positive $200,000 to negative $100,000. The formula didn't change. The inputs did.
Why the Number Alone Lies to You
A positive net working capital figure sounds good. It is not always good. If your working capital is $500,000 but $450,000 of that is tied up in aging inventory you can't move, you are not liquid. You are just holding expensive stuff. Conversely, a small or even negative number can be fine if your business model generates cash quickly enough to cover obligations. Grocery stores and restaurants routinely run negative working capital because they sell inventory before paying suppliers. That is normal for those models. It is catastrophic for a custom furniture maker with 90-day receivables. The ratio version of this metric is more useful than the raw dollar amount. Divide net working capital by total current assets and you get the working capital ratio, sometimes called the current ratio when expressed differently. A ratio above 1.5 is generally comfortable. Below 1.0 is a yellow flag. But again, industry context matters more than the number itself. Commercial real estate, software, and heavy manufacturing all operate with very different norms. Here is the part most guides skip. Net working capital does not tell you about timing. It tells you about a snapshot. Your receivables balance on March 31 could be $200,000, but if $150,000 of that is past due, you do not have $200,000 in accessible liquidity. You have maybe $50,000. The workaround I use is to age the receivables separately before plugging anything into the formula. Pull an AR aging report, mark anything over 60 days as questionable, and adjust your current assets downward before calculating. This usually reveals a gap of 15 to 30 percent compared to the unadjusted number.
Get the Full Details
How to Actually Use This Metric
Once you have the adjusted number, you use it to answer three questions. Can you pay upcoming obligations? How much capital is trapped in operations? Where is the inefficiency sitting? For the first question, compare your net working capital against your next 30 days of payables. If your NWC is lower, you will need external financing or faster collections. For the second, look at the composition. High inventory relative to receivables suggests overproduction or poor sales forecasting. High receivables relative to payables means your customers are using your money for free. For the third, drill into the line items with the biggest variance month over month. I track this monthly for every client now. Not quarterly. Monthly. The difference is that quarterly tracking means you discover problems after they have compounded for three months. Monthly tracking gives you a two-month window to fix things before they become crises. The process takes about 20 minutes if your accounting is organized. About four hours if you are pulling data from three different systems like most small businesses do.
One edge case worth mentioning. Seasonal businesses will swing wildly on this metric depending on when you measure. A landscaping company might show negative working capital in November and triple that by June. The fix is to track the trend across seasons rather than chasing an absolute target. Look at whether the seasonal cycle is improving or deteriorating year over year.
When This Metric Fails You Completely
Net working capital ignores the cost of capital. It does not tell you whether tying up $1 million in receivables is better or worse than keeping that money in a savings account. For a thin-margin business, the opportunity cost of illiquid working capital can eat into profitability faster than any expense cut will recover it. If your gross margin is under 25 percent, I would supplement this metric with a cash conversion cycle calculation instead. That accounts for how many days your money is actually stuck in the operating loop. It also fails for service businesses with minimal inventory and fast payment cycles. A consulting firm might show $50,000 in working capital and another show $500,000, but the second firm could be far healthier because its clients pay upfront while the first firm chases invoices. The dollar amount alone misleads you. The ratio and the composition tell the real story. If you want to dig deeper into how this works across different business models, the material covering The Definitive Guide To Net Working Capital Formula Unlock Your Businesss Liquidity Health goes into sector-specific benchmarks and the adjustments I make for industries where standard formulas break down.