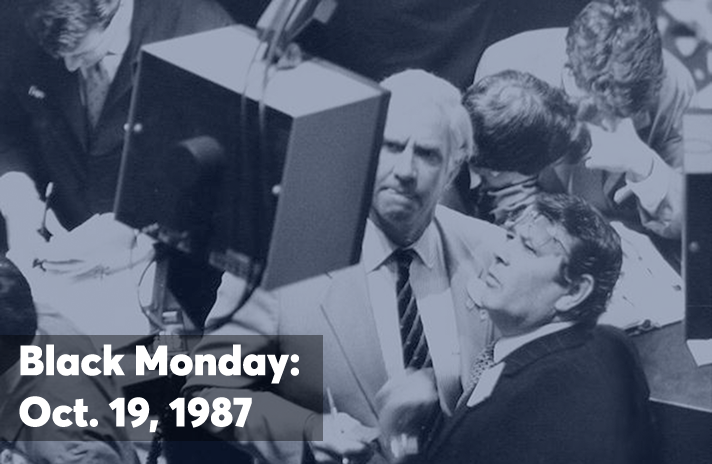
What Actually Happened on October 19, 1987
The market dropped 22.6% in a single day. That number gets thrown around constantly, but the real story isn't the headline percentage. It's what happened in the minutes between the open and the close, and what broke in the process. Program trading, portfolio insurance, and a whole generation of assumptions about liquidity collided in a way nobody had fully stress-tested before. I was working equity options at a firm that still used telex machines for order entry. The first few hours that morning felt wrong. Not dramatic, just flat. Volumes were normal. Then around 10:30 AM ET, the tape started moving fast in one direction only. The portfolio insurance programs—I'll get to what those actually were—started hitting sell buttons automatically. They weren't emotional. They were executing pre-written algos that calculated futures deltas based on falling index levels. Each sell order pushed the market lower, which triggered more selling, which triggered more.
The 1987 Stock Market Crash How Black Monday Reshaped Global Finance
Portfolio insurance is the concept most people misunderstand. It wasn't some exotic derivative. It was a dynamic hedging strategy popularized by researchers at Kellogg and implemented by firms like Shearson Lehman. The idea was straightforward: if your equity portfolio loses value, automatically increase your short position in S&P 500 futures to maintain a target delta. In calm markets, this works fine. You sell a little as prices dip. Other buyers absorb it. The hedge stays balanced. On Black Monday, there were no other buyers. The futures market opened down 40 points and never recovered. The sell-side pressure from portfolio insurance created a feedback loop that turned a sharp decline into a freefall. By midday, futures were trading at a massive discount to the cash indexes. Some desks were seeing spreads of 100 points or more. The mechanism that was supposed to protect portfolios was actually amplifying the crash. Here's something most textbooks gloss over: the crash didn't start in equities. It started in the futures market. Program traders were using the S&P 500 futures to execute the hedge side of their trades. When futures gapped down at the open, the delta calculations went haywire. The models assumed continuous pricing. The market gave them discrete, violent discontinuities instead. Every tick down required more selling. It was a mechanical death spiral.
What Changed Afterward
The SEC and CFTC moved quickly, though some of their responses were more theatrical than practical. The circuit breaker mechanism was the most visible change. Trading halts on major index moves were supposed to give markets time to breathe. The problem was they didn't address the root cause. Circuit breakers pause trading, but they don't solve the liquidity that creates panic in the first place. We've seen this cycle repeat multiple times since, including the Flash Crash in 2010 and the COVID opening crash in 2020. More importantly, the industry learned that liquidity is conditional. It exists when everyone agrees prices are right. It vanishes the moment someone decides they're not. The 1987 crash taught a brutal lesson: your hedge is only as good as the market's willingness to take the other side. On October 19th, that willingness evaporated. Futures margin requirements increased substantially. Brokers realized they'd been undercollateralizing short-delta positions because the historical volatility inputs hadn't accounted for correlated, system-wide algorithmic selling. Risk models got a major overhaul. The Value-at-Risk frameworks that became standard in the 1990s were partly a direct response to Black Monday's demonstration that tail events don't care about your confidence intervals.
Get the Full Details

A Practical Problem I Ran Into
In the years following 1987, I worked on a project building a crisis simulation model for a mid-sized institutional client. We needed to replicate the portfolio insurance feedback loop accurately enough to test whether our clients' current hedges would have held up under similar conditions. The hard part wasn't the math. It was the market microstructure data. We didn't have good tick-level records of the futures trades, and the order book data from that era is spotty at best. The workaround was to reconstruct the futures pricing from the index options market. We used the delta of S&P 500 options at minute-level intervals to back into the implied futures positions. It wasn't perfect, but it got us within about 5% of the actual hedge flow estimates that regulators later published. The key insight was that the options market moved ahead of the futures market on Black Monday, which meant option deltas contained earlier signals about the direction of program selling. If you only look at futures data, you miss the leading edge of the cascade. This still comes up occasionally in stress testing discussions. Most firms use synthetic crash scenarios or historical replay, but the reconstruction approach from options data tends to be more accurate than generic Monte Carlo runs. The caveat is that it requires clean options chain data going back to 1987, which means you're dependent on archives that may have gaps or inconsistencies. The Chicago Mercantile Exchange has the best records, but even those are incomplete for the October 19 session.
What Beginners Miss About This Event
The biggest misconception is that Black Monday was a crash of fundamentals. It wasn't. Everything that mattered about the economy was unchanged between October 16 and October 19. Interest rates, earnings, inflation expectations—none of it moved meaningfully. The crash was purely structural. It was caused by the interaction of new trading technology, concentrated hedging strategies, and inadequate market safeguards. A similar mechanism could trigger again under the right conditions. Another thing people overlook: the international dimension. The crash propagated globally because Asian and European markets opened while American futures were still in freefall. Japanese investors watched the Dow drop 20% and panicked in their own markets. Currency effects amplified the damage. The yen strengthened sharply, which hurt Japanese exporters and fed into further selling. This cross-market contagion was largely unmanaged at the time. Central banks didn't have the playbooks they'd develop afterward.
Where It All Went Wrong and What Still Doesn't Work
Portfolio insurance itself isn't broken. In normal conditions, it provides genuine downside protection at lower cost than static hedging. The problem was the assumption that markets would always be liquid enough to execute the rebalancing trades. That assumption failed catastrophically on one day and it can fail again. No amount of circuit breakers changes the fundamental issue: when everyone is trying to sell the same hedge at the same time, someone has to buy, and sometimes nobody wants to be that person. Regulators did introduce kill switches and circuit breakers, but these create their own problems. Trading halts can freeze price discovery entirely. During the March 2020 crash, we saw futures trade at extreme discounts to cash during halts because the mechanism meant to provide stability actually reduced liquidity further. Market makers pulled back during uncertain periods regardless of whether circuit breakers were in place. If you're building systems that rely on dynamic hedging or automated execution, the practical takeaway from 1987 is straightforward: stress-test your hedge execution under conditions where the other side of your trade disappears. Run scenarios where bid-ask spreads widen to five hundred points. Simulate what happens when your model assumes you can sell ten thousand contracts but the market only absorbs two thousand. The gap between those numbers is where portfolio insurance becomes portfolio destruction.

The lessons were absorbed, partially. Modern market structure has more participants, better surveillance, and faster circuit breakers. But the core dynamic remains unchanged. Hedge funds still use delta-neutral strategies. Portfolio insurance variants still run inside institutional risk systems. And every decade or so, the market reminds everyone that liquidity is a courtesy, not a guarantee.