The Nonalcoholic Beverage Market Right Now
The category is growing faster than most people think. I've been tracking formulation shifts and distribution changes for about eight years, and the pace has accelerated noticeably since 2021. What used to be a niche shelf in Whole Foods is now a full facings situation in conventional grocery, and that expansion has created some interesting problems for brands trying to stay relevant. I worked on a project last year where we tried to reverse-engineer why certain craft nonalcoholic spirits were failing at retail despite strong social media presence. The issue wasn't the product itself. It was shelf placement, price point confusion, and a marketing team that kept treating their audience like they were still in the "curious drinker" phase instead of the "regular buyer" phase. Most brands never make that distinction clearly enough.
Unlock The Secrets Of Top Nonalcoholic Beverage Brands The Trends That Will Shape the Industry
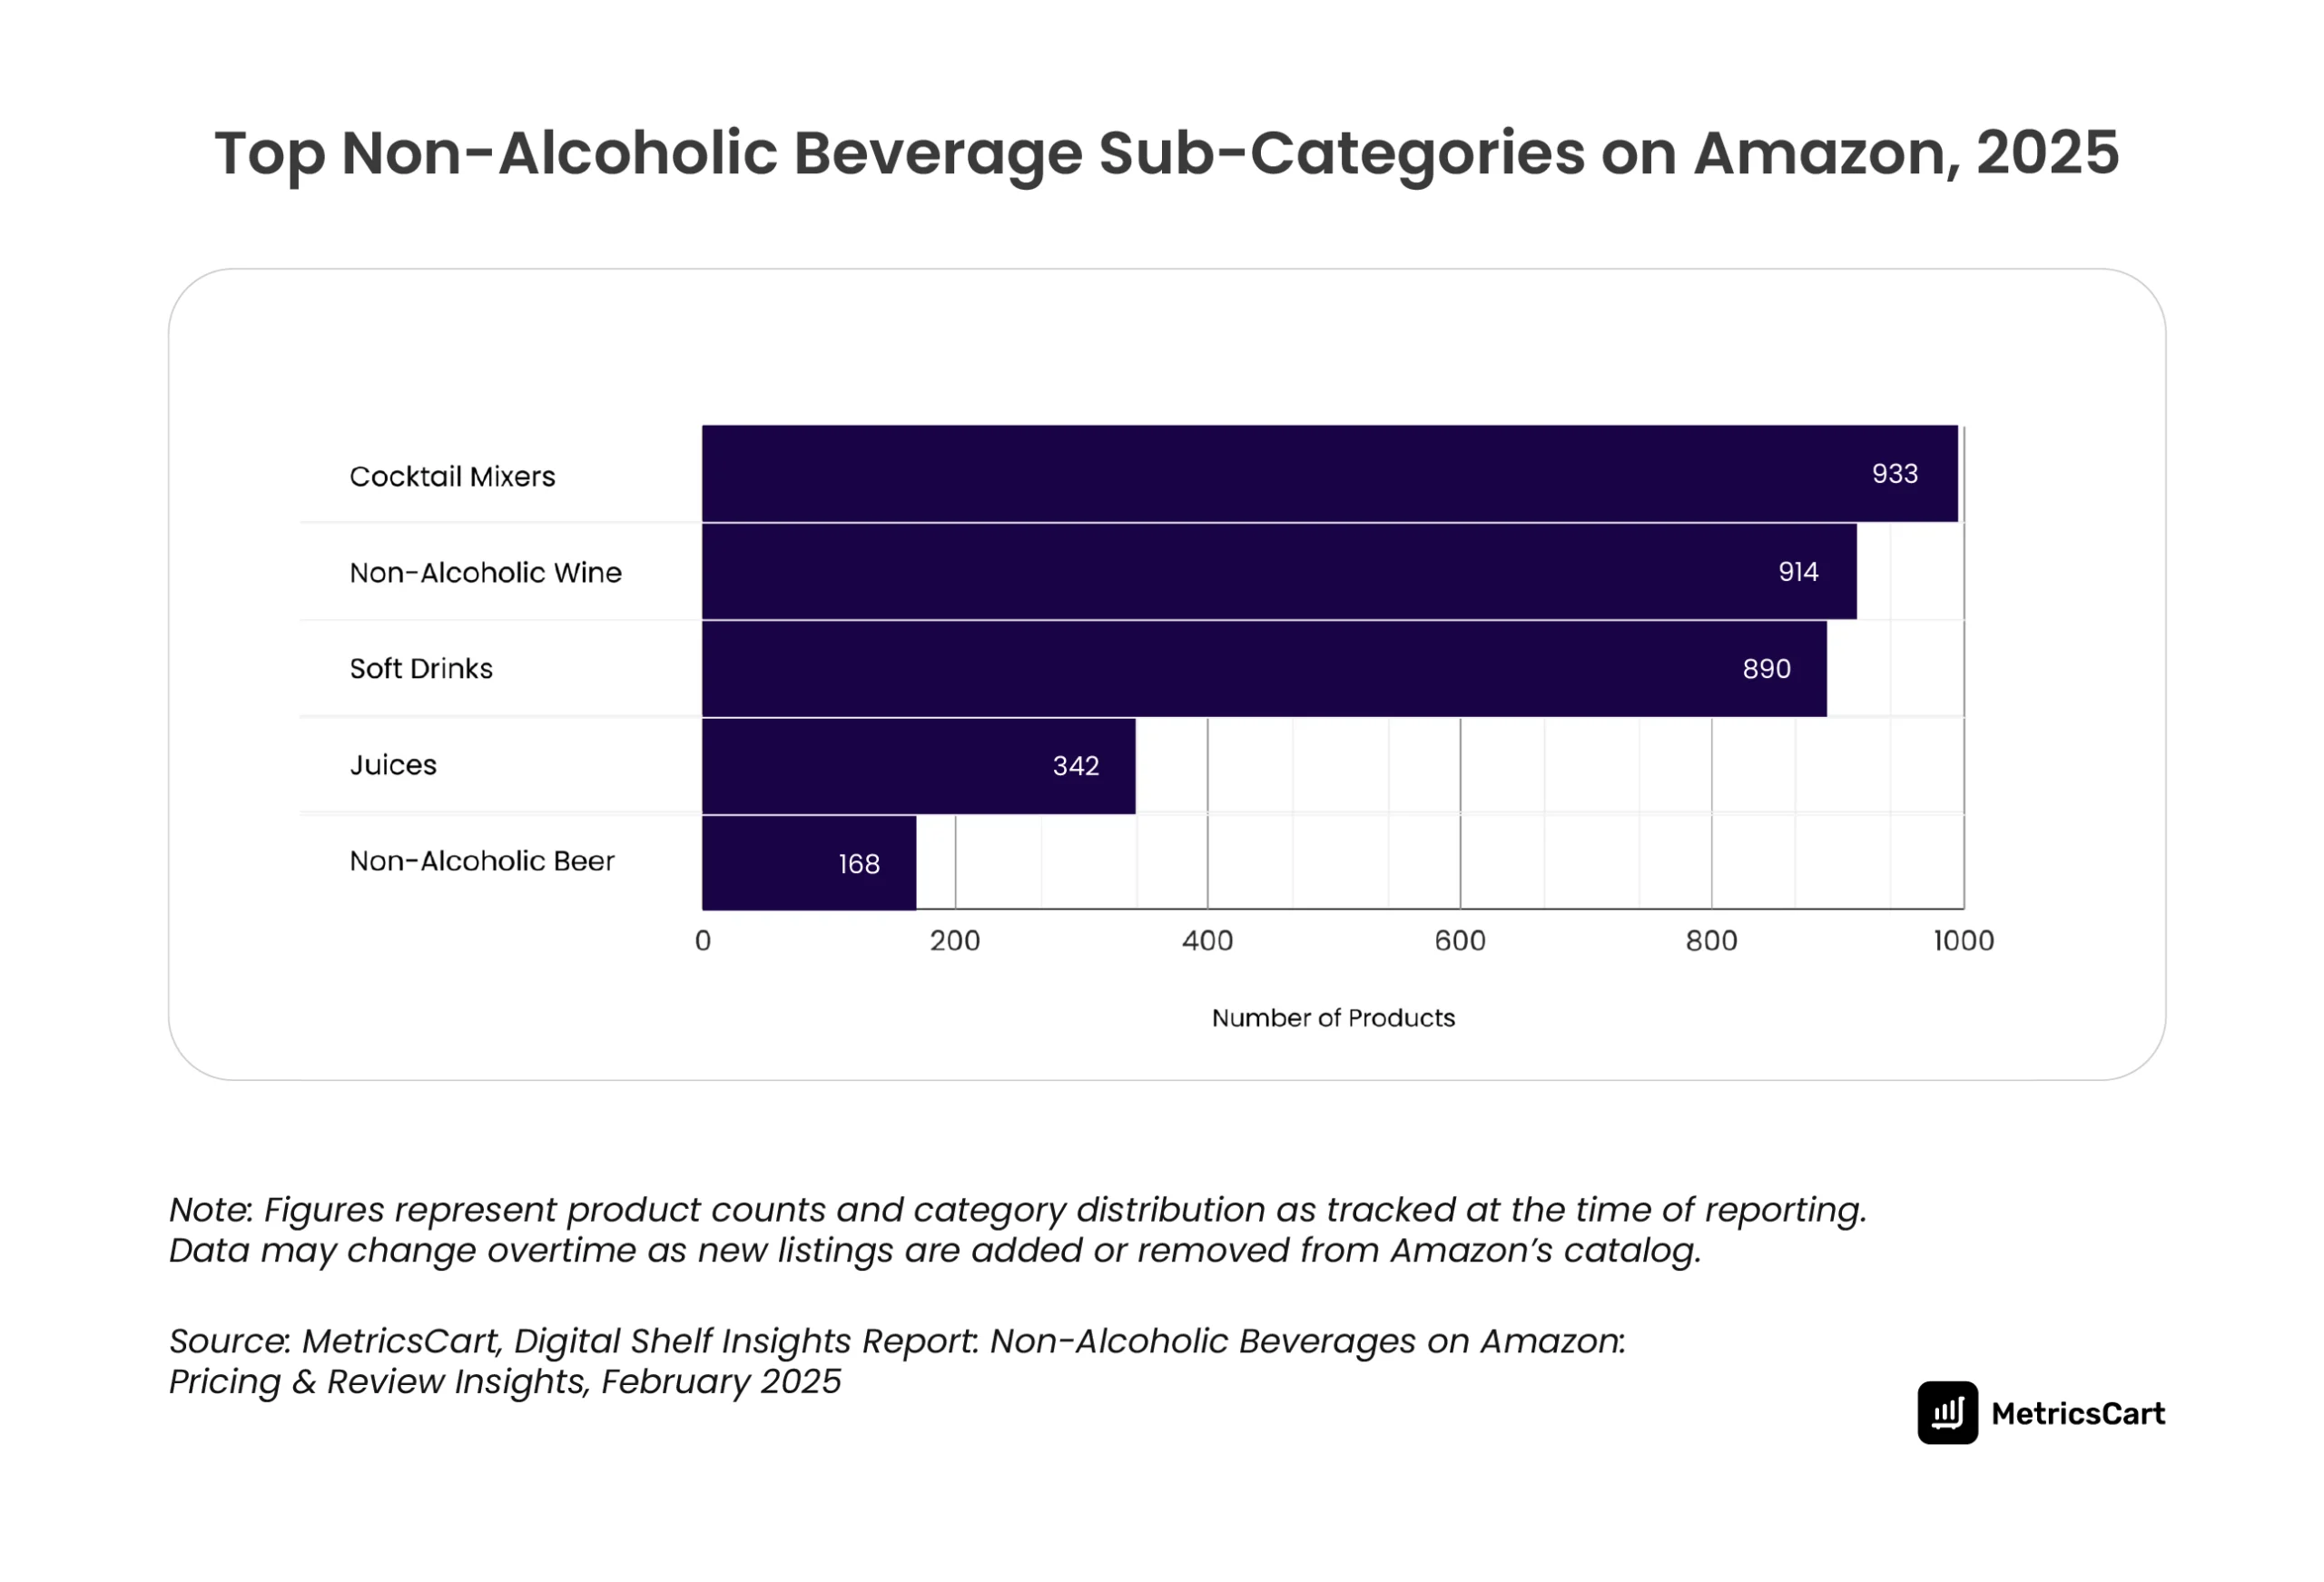
Here's what actually separates the surviving brands from the ones that folded within eighteen months. I'm not going to list company names because that date-stamps the information and most of those rankings shift quarterly anyway. The patterns are more useful. Nonalcoholic beer still dominates by volume. It always has. But the growth margins are elsewhere. Nonalcoholic wine, functional sparkling waters with adaptogens, and the so-called "sober curious" spirit alternatives are where the margin expansion is happening. Retail buyers have told me directly that they're requesting more SKUs in the $8 to $14 range per unit, not the premium $18-plus channel where early movers got stuck. One thing most trend reports miss: carbonation fatigue. Consumers are showing signs of tiredness with heavily carbonated alternative drinks. I noticed this when a client asked me to help formulate a still version of their popular botanical spritz. The still version actually outsold the carbonated original in test markets within six weeks. The lesson isn't that carbonation is bad. It's that the market has oversaturated on it and differentiation is moving toward texture and mouthfeel instead of fizz.
Formulation Realities Nobody Talks About
Removing alcohol creates a structural problem. Alcohol is a solvent, a preservative, and a mouthfeel agent all at once. When you take it out, you need replacements for each function and most brands get two of those three wrong. I've seen too many products that taste correct in isolation but fall apart after three months on the shelf because the preservation system wasn't designed for a zero-alcohol matrix. The workaround I use now is to build the preservation hurdle first, then formulate flavor around it. Start with pH, water activity, and preservative compatibility before you lock in botanical profiles. Flip that order and you'll waste forty to sixty hours of development time on products that look good in week one and separate or sour by month three. Another counter-intuitive point: using small amounts of glycerin or propylene glycol for mouthfeel is standard practice in the industry, but the label-cleaning crowd pushes back on it. The brands winning right now are the ones that figured out how to communicate this honestly without alienating their core demographic. "Processed mouthfeel agents" doesn't sell. "Texture from grape concentrate and vegetable glycerin" does. Word choice matters more than actual ingredient difference here.
Get the Full Details
Distribution and the Shelf Reality
I spent a semester advising a startup that had excellent product and terrible distribution strategy. They wanted direct-to-consumer only. The math didn't work. Their customer acquisition cost was running about $34 per order and their repeat rate was only 28 percent because people don't subscribe to nonalcoholic beverages the way they subscribe to coffee or meal kits. Moving into retail changed everything. They hit a break-even point at roughly 4,200 units per store per month, which turned out to be achievable in about sixty stores across three regions. The mistake most founders make is thinking retail is the hard part. It isn't. The hard part is maintaining fill rates once you're on shelves. I've watched brands lose accounts because they couldn't keep product in stock during peak demand windows. Warehouse capacity, lead times on botanical ingredients, and contract manufacturer bandwidth are the real bottlenecks, not the sales pitch.
What to Watch Over the Next Twelve Months
Regulatory changes around health claims are tightening in both the EU and US. Brands making functional beverages with adaptogens or nootropics need to understand that structure-function claims require disclaimers and certain language is becoming noncompliant faster than companies realize. I had a client pull a product launch because the FDA sent a warning letter about implied cognitive benefits. They weren't even making direct medical claims. The language was borderline and the regulatory environment doesn't tolerate borderline right now. Another trend that's barely covered: private label nonalcoholic beverages. Major retailers are developing their own versions and the quality gap has closed significantly. If you're building a brand in this space, assume your private label competitor will be on the shelf next to you within two years. That should influence your pricing strategy and your investment in brand equity from day one. The market isn't going away. The people who treat it like a temporary wellness fad are the ones who will burn through capital and leave. The brands that are sticking around are the ones treating this like a legitimate beverage category with real formulation challenges, real distribution complexity, and real consumer habits that take years to shift rather than months.