Why Everyone Keeps Looking at This One Line on a Screen
The 10 Year Treasury Chart Understanding The Key To The Us Economic Engine isn't a meme. It's something you probably see reposted every time the Fed meets and someone with decent font choices makes a screenshot go viral. But here's the thing most people miss when they're glancing at it between scrolls: the chart itself is almost irrelevant without context. A rising yield curve means one thing in 2022 and something entirely different in 2019. I've seen traders lose money because they treated a single data point like a crystal ball instead of a noisy signal that needs corroborating evidence. I work with fixed income data, and the ten-year is the benchmark everyone clings to because it's simple. That simplicity is also its main weakness. When I first started pulling these charts for clients, I made the mistake of assuming a crossing event on the yield curve was a reliable recession signal. It wasn't. The inversion had already been pricing in monetary tightening for months, and by the time the chart looked dramatic, the market had moved three times already. You need to understand what the yield actually represents before you make any trades or decisions based on it.
The 10 Year Treasury Chart Understanding The Key To The Us Economic Engine
The 10-year Treasury note is a debt instrument issued by the U.S. government with a maturity of exactly ten years. The yield you see on any chart is the annualized return an investor would get if they bought the bond at the current price and held it to maturity. It moves inversely to price. When demand for the bond goes up, price goes up, yield goes down. When people sell, yield rises. That's it mechanically. The reason it matters economically is that it serves as the risk-free baseline for virtually every other interest rate in the system. Mortgage rates track it. Corporate bond spreads are priced on top of it. Even equity valuations use it as the discount rate component in DCF models. When the 10-year yield jumps from 2% to 4%, commercial real estate becomes unviable, tech startups face harsher financing conditions, and the dollar strengthens because higher yields attract foreign capital. These are not theoretical connections. They happen in real time and they affect real businesses that don't have treasury departments to hedge against them. Here's where it gets practical. To read this chart properly, you need to overlay at least three things: the 2-year yield, the federal funds rate, and inflation expectations from TIPS. A standalone 10-year line tells you almost nothing about direction or cause. The spread between the 10-year and 2-year is the curve shape. Steepening means markets expect growth or future rate hikes. Flattening means the opposite. Inverting, which we saw from mid-2022 through most of 2023, historically precedes recessions but not reliably enough to trade off of alone. The lag is unpredictable. Sometimes six months. Sometimes eighteen. Sometimes the inversion happens and nothing follows because the Fed cuts fast enough to prevent the downturn.
How to Actually Pull and Read the Data Yourself
You don't need a Bloomberg terminal for this. The Federal Reserve Economic Data site at fred.stlouisfed.org has everything free. Pull the DGS10 series for the 10-year constant maturity Treasury yield and DGS2 for the 2-year. Download the data in daily frequency and plot it against your favorite charting tool. TradingView works fine. Excel works fine. I use a basic Python script with matplotlib for quick checks, but honestly the process from raw data to readable chart takes about five minutes once you have it set up. The chart you'll produce will look like a random walk most of the time. Yields can drift within a tight range for months with no obvious catalyst, then gap up or down on a single employment report. The key is not predicting the next tick. It's understanding where the current yield sits relative to its own history. Is it in the 80th percentile of the last decade? The last twenty years? The last thirty? That percentile context matters more than the absolute number. A yield of 4% meant something different in 2004 than it does now, and comparing raw numbers across decades without adjusting for the macro environment is one of the most common mistakes I see from people who are just starting to look at this space. Another thing that trips people up: the difference between the on-the-run and off-the-run 10-year. The on-the-run is the most recently issued Treasury note and it trades at a liquidity premium. The yield on the on-the-run is what you'll see quoted everywhere, but if you're actually trying to understand what the market is paying for long-duration risk, you should also watch the off-the-run spread. It widened noticeably during the March 2020 crash and again in 2023 during the regional banking stress. Those spread widens told a story about liquidity that the headline yield alone hid.
Get the Full Details

What the Chart Actually Tells You and What It Lies About
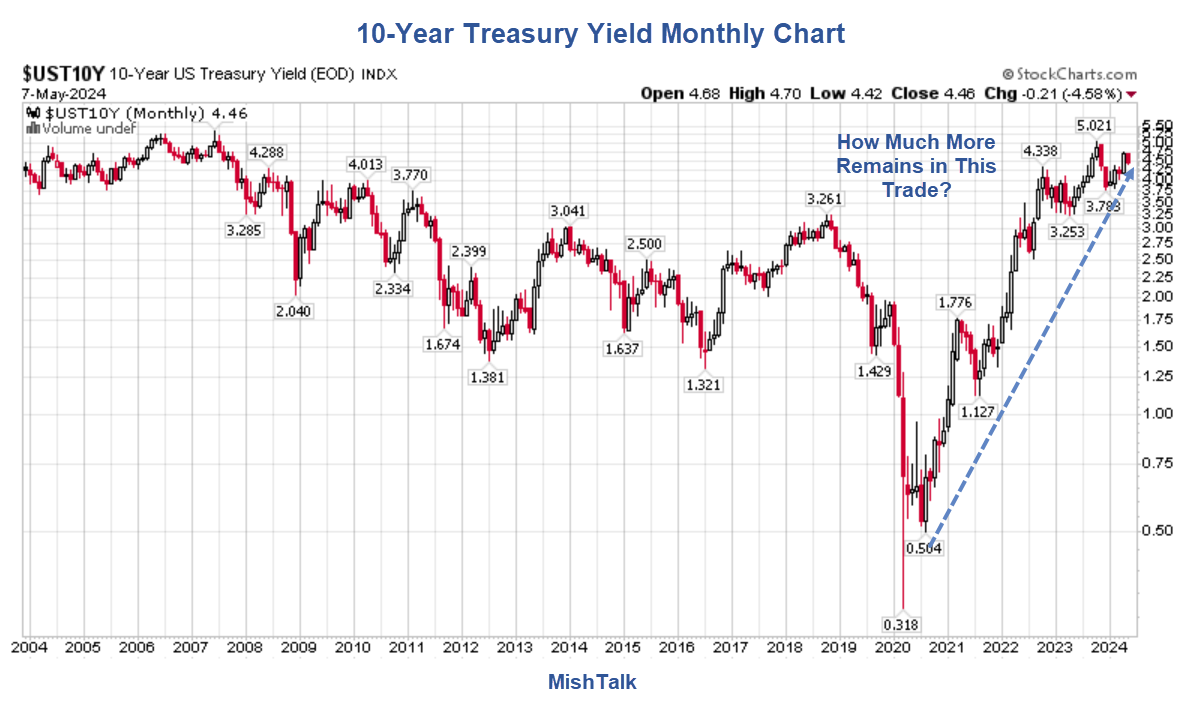
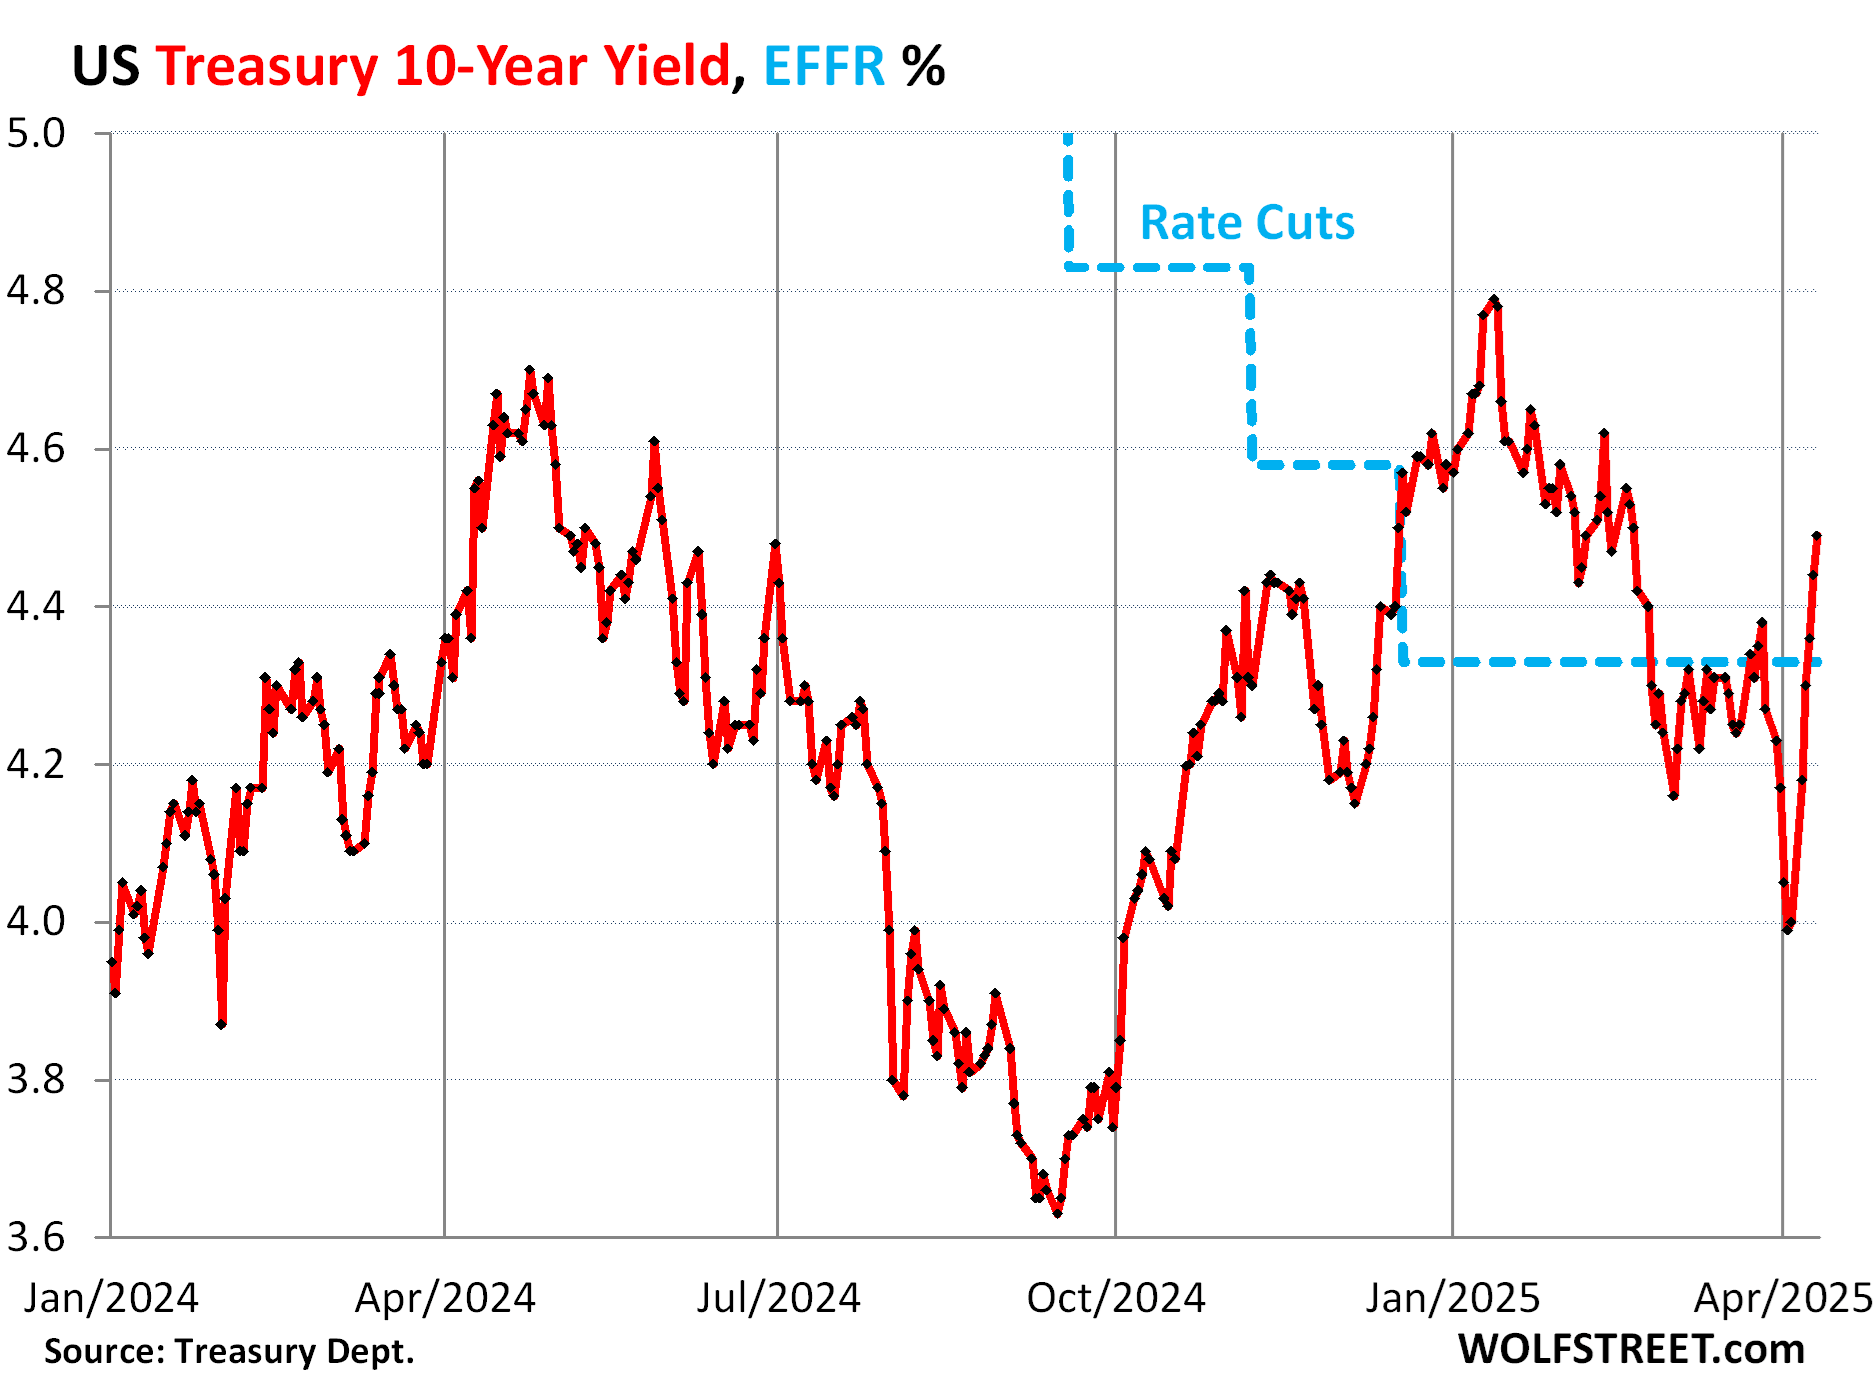
The 10-year yield is a forward-looking indicator. It reflects what the market believes will happen to growth and inflation over the next decade, discounted by current monetary policy. That's why it can fall even during a recession if investors expect the Fed to cut rates aggressively. The yield dropped to historic lows in 2020 not because the economy was performing well, but because everyone expected a brutal downturn and massive central bank response. The chart was telling you about expectations, not current reality. This distinction is critical and it's where most analyses fail. People see yields drop and assume deflationary doom. People see yields rise and assume inflation is out of control. Both reactions ignore the expectation component. During 2023, the 10-year bounced between roughly 3.5% and 5% while the Fed held rates steady and inflation came down gradually. The yield moves were driven almost entirely by shifting expectations about how long the Fed would hold rates high, not by changes in actual economic conditions. If you were trading based on the chart alone, you got whipsawed repeatedly. I encountered a specific edge case last year that illustrates this perfectly. We were building a model to forecast commercial lending demand for a mid-market bank client. The 10-year yield had been stable around 4.2% for three months, but the curve was steepening rapidly as short rates stayed elevated while long rates climbed. On the surface, this looked like a straightforward growth signal. It wasn't. The steepening was driven by term premium expansion, not growth expectations. The market was demanding extra compensation for holding long-duration paper because of fiscal supply concerns, not because anyone expected booming economic activity. If we'd interpreted the chart naively, we would have overestimated lending demand by a significant margin. The workaround was to strip out the breakeven inflation rate and the nominal real yield separately, then compare the term premium component against historical norms. Only then did the picture become clear.
Common Pitfalls That Cost People Money
The first pitfall is treating the 10-year yield as a leading indicator of GDP growth. It's not. It's a leading indicator of monetary policy expectations, which is a different thing entirely. GDP can grow while yields fall, as we've seen multiple times when the Fed was easing aggressively. The correlation exists in some periods and breaks down in others. Relying on it as a standalone predictor is a mistake. The second pitfall is ignoring the global context. The U.S. 10-year yield doesn't move in a vacuum. German bund yields, Japanese JGB yields, and British gilt yields all interact with it through capital flows. When the Bank of Japan stayed deeply accommodative while the Fed tightened, the yield differential drove massive dollar strength. That dollar strength then fed back into U.S. export competitiveness and corporate earnings. A chart that only shows the U.S. side of this equation is missing half the story. The third pitfall is the recency bias. When yields have been low for a decade, analysts unconsciously treat low yields as the default state and high yields as the anomaly. The opposite is also true after a sharp rally. Neither assumption is correct. The long-term average of the 10-year yield since 1962 is roughly 5.5%. We've spent the better part of the last fifteen years below that. Mean reversion isn't a trading strategy, but it's a reality check that keeps your assumptions honest.
When This Tool Completely Fails You
The 10-year Treasury chart is useless as a timing tool. No amount of pattern recognition on this chart will tell you when to buy or sell. The signal-to-noise ratio is terrible on anything shorter than a quarterly horizon. If you're looking for entry and exit points, you need order flow data, options positioning, and central bank communication analysis layered on top. The yield chart alone gives you directional context at best. It's also largely irrelevant during periods of quantitative tightening or expanded quantitative easing. When the Fed is a major buyer or seller of 10-year notes, the yield stops being a pure market equilibrium and becomes a function of balance sheet policy. The period from 2020 to 2022 was dominated by Fed purchases. The period from 2022 onward has been dominated by runoff. In both cases, the yield chart reflected central bank actions more than it reflected organic market sentiment about growth and inflation. Trying to read pure economic signals into yields during those periods produced noisy and misleading results. If you want a more reliable picture of where the economy is actually heading, combine the 10-year yield with the Phillips curve relationship, the yield curve spread, and the Chicago Fed National Activity Index. None of these are perfect on their own. Together they give you a framework that's harder to misinterpret. The 10-year Treasury remains essential to that framework, but it's a component, not the whole thing. Anyone who tells you otherwise is selling something.