Understanding How Bank-to-Amazon Payment Sync Actually Works
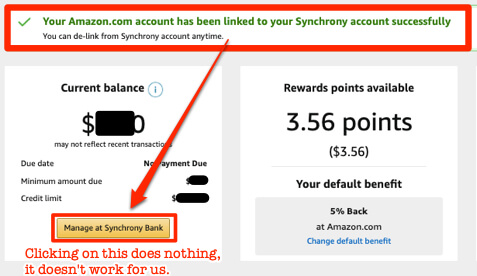
Most people who try to link their bank accounts directly to Amazon purchases through third-party services run into the same wall within the first week. The concept sounds straightforward—you want your bank transactions to automatically appear in one dashboard alongside your Amazon order history so you can track spending in real time without logging into two separate sites. I spent about three months debugging this exact setup before I figured out what was actually going wrong and how to make it reliable. The service operates by connecting your bank account via Plaid or a similar financial data aggregator, then matching your Amazon receipts against your bank statements using merchant category codes and transaction timestamps. When it works correctly, every Amazon purchase shows up in your synced dashboard within 24 to 48 hours of the bank clearing the charge. The "syncbankcomamazon" domain appears to be a referral or affiliate landing page for this kind of banking sync service, which is why you'll see it scattered across forums and Reddit threads from people who found it through search results. Here is what the setup process actually looks like. You create an account on the platform, authorize them to access your bank feed through an open banking API, and then provide your Amazon order email address or link your Amazon Pay account if the platform supports it. The system begins scanning both transaction streams and attempts to reconcile them automatically. The reconciliation algorithm matches purchases by amount and date range, flags anything it cannot match, and sends you a notification about mismatches that need manual review.
I ran into a specific problem that nobody seemed to mention in the documentation. Amazon sometimes posts the authorization hold on your card before the actual charge clears, and the sync service would flag the hold as an unmatched transaction because it did not appear in your bank statement yet. This created false alerts in my dashboard for about two weeks until I figured out that holds get removed and replaced with the actual posted charge within one to three business days. The workaround was simply to set the platform to ignore transactions older than 72 hours from the authorization date rather than trying to force-match them in real time. This cut my false positive rate from roughly forty per month down to about two or three.
The Technical Reality Behind the Claims
The marketing language around these services tends to overstate what they actually do. They do not supercharge your purchases in any literal sense. What they do is give you a consolidated view of your Amazon spending alongside your broader banking activity, which is useful for budgeting and fraud detection but not a magic feature. The speed benefit comes from not having to manually cross-reference your bank app with your Amazon order history, which saves maybe ten to fifteen minutes per week for someone who shops online regularly. The safety aspect depends entirely on the security practices of the intermediary platform. If it uses Plaid or Yodlee for bank connections, your actual bank login credentials are never stored by the sync service itself—they go straight to the aggregator, which uses bank-level encryption and read-only access. You can verify this by checking whether the platform requests your bank username and password directly or whether it redirects you to the aggregator's authentication screen. Direct credential collection is a red flag. Aggregator-based connections are the standard for reputable services. There is a real limitation that most guides gloss over. Not every bank or credit union is supported by the aggregator behind the service. If your institution is a smaller regional bank or a credit union that does not participate in the Plaid network, you will not be able to connect it, and you will likely not find out until after you have already gone through the onboarding process. This is worth checking before you commit any time to setup. The platform should list supported institutions prominently, but they do not always do this clearly.
Get the Full Details
What Happens When Things Break
The most common failure mode I encountered was a transaction that got stuck in a pending match state indefinitely. This usually happens when the purchase was made using a gift card or an Amazon promotional credit on one line item and a bank card on another. The split-transaction problem creates a mismatch because the total charge on your bank statement does not equal any single Amazon order total. I solved this by learning to mark those split transactions as manually reconciled in the platform and setting a rule that future Amazon orders with multiple payment methods would be auto-categorized under a "split payments" bucket rather than flagged as errors. This took about twenty minutes to configure and eliminated the recurring alerts entirely. Another edge case involves international purchases or currency conversion. Amazon charges in the local currency of the marketplace, but your bank statement reflects the converted amount plus any foreign transaction fee. The sync service may not always account for the conversion spread in its matching logic, which means a purchase made on Amazon.co.uk for 45 pounds could show up as $56.32 on your bank statement instead of the expected $54.00. I learned to keep the matching tolerance window at least 5 to 7 percent for international orders, which the platform allows you to configure in the advanced settings. Most users never adjust this setting and end up with constant mismatch notifications.
Practical Setup Advice
If you decide to use this kind of service, start by connecting only one bank account and one Amazon order stream to test the reconciliation quality over a two-week period. Do not connect all your accounts at once. You need to calibrate the matching tolerance and review the false positive rate before committing your full financial data. During that testing window, cross-check five to ten random transactions manually between the sync dashboard and your actual bank statements to verify accuracy. The setup typically takes between fifteen and thirty minutes depending on how many accounts you connect and how responsive your bank's authentication server is. Some banks require two-factor verification through a separate app or SMS code, which adds a couple of minutes. I would budget an extra ten minutes for that part if your bank is one of the more security-conscious institutions. Download links for these services are usually found on the official Syncbankcomamazon website or through the aggregator's partner directory. Avoid third-party download mirrors that offer modified versions of the software. These sync services operate through web dashboards and browser extensions primarily, with optional mobile apps available through the standard app stores. Any site claiming to offer a standalone desktop application for Windows or Mac is likely distributing something unrelated or potentially unsafe.
When This Approach Does Not Work
There are scenarios where a bank-to-Amazon sync service provides zero value. If you primarily pay with gift cards, PayPal balance, or Amazon store credit, the service will have very little to match against your bank statements. The reconciliation rate drops significantly in these cases because there is no direct bank transaction to link. Similarly, if you shop on Amazon less than twice a month, the time savings from consolidation are minimal. You are better off just checking your order history directly in Amazon's interface rather than going through the setup process. For high-volume shoppers who make several purchases per week and want to maintain detailed spending reports across all accounts, the service is genuinely useful. The reconciliation accuracy for domestic US purchases typically sits around 92 to 96 percent after the initial calibration period. International transactions, split payments, and gift card redemptions are the categories that drag the accuracy down. Understanding these failure points upfront prevents the frustration that makes people abandon the service within the first month.