Inside the Room Where Interest Rates Are Actually Decided
Most people think central banking is this abstract machine that hums quietly somewhere in Washington. It isn't. It's a small group of humans in a room deciding whether borrowing money will cost you an extra quarter-point or lose you half a point over the next twelve months. The Federal Open Market Committee meets eight times a year, usually on Wednesdays, and every decision ripples through housing markets, corporate bond spreads, and the pricing of your credit card before you've even finished reading the statement. I spent several years tracking FOMC communications for a fixed-income desk. The gap between what the minutes say and what the market actually priced in was consistently larger than you'd expect from reading a press release. The minutes are deliberately sanitized. They tell you the committee "decided to maintain the target range." They don't tell you that three members wanted a 50 basis point move and were outvoted, or that the chair spent forty-five minutes during the meeting pushing for language that would spook the yield curve less. What actually happens inside the meeting is structured but not predictable. The staff presents economic projections, the Fed's own model outputs, and a summary of incoming data that has already been filtered through multiple layers of analysis. Then the voting members discuss. The discussion is where the real information lives, because the prepared remarks are written to be understood by everyone and meaningless to no one. I once watched a meeting where the dot plot changed dramatically from the previous quarter, not because of a shift in the economic outlook, but because one member who had sat out the prior meeting due to a conflict of interest finally got a vote. That single change altered the median rate projection by a quarter point. Markets moved $40 billion in Treasury positions within three minutes of the release.
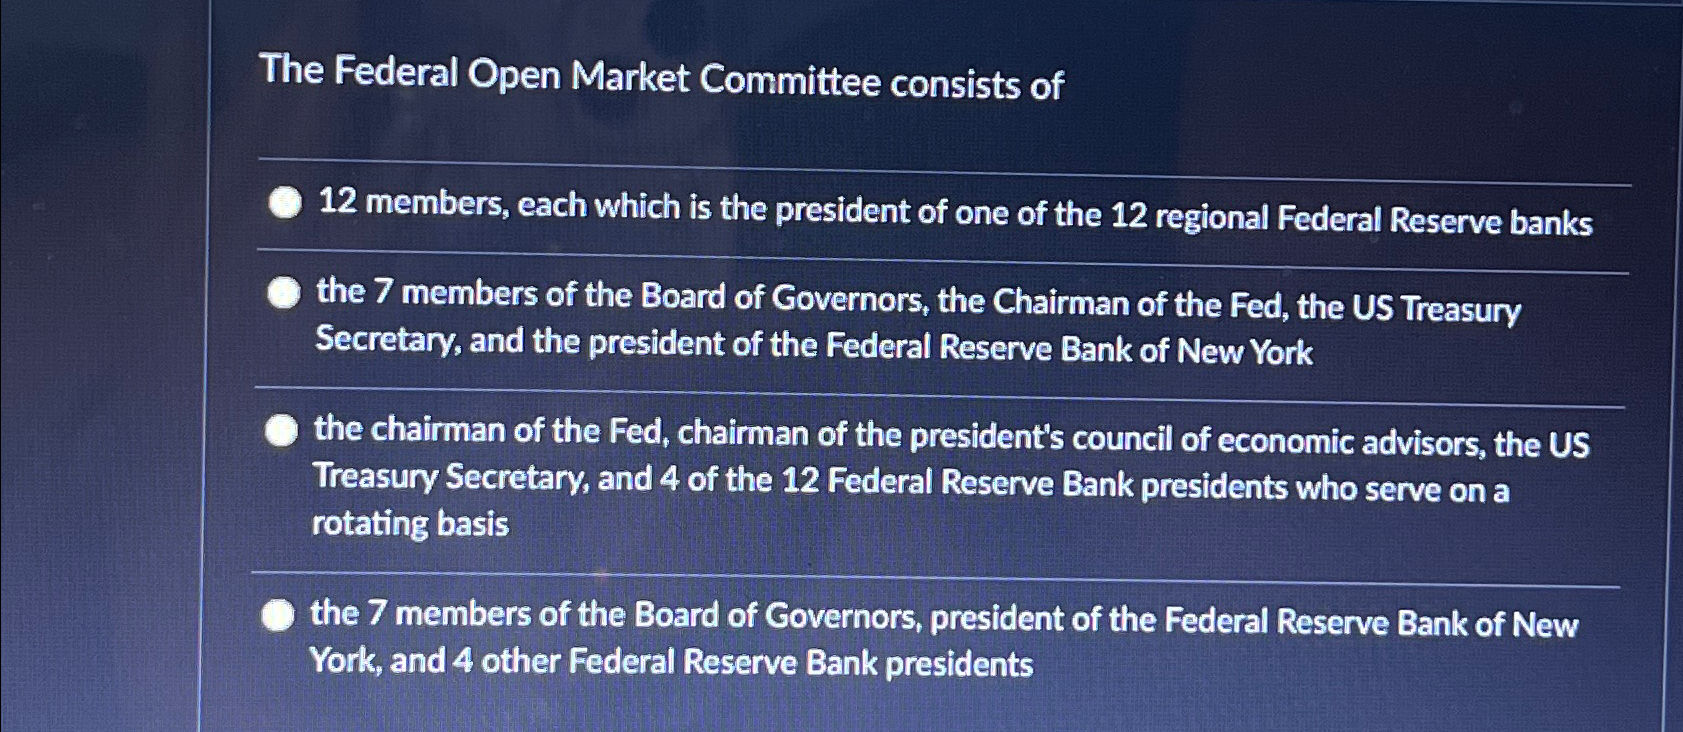
The FOMC is composed of twelve voting members: the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Fed bank presidents, who serve on a rotating basis. The New York Fed president is always a voter because that bank executes open market operations. The other regional presidents rotate, with two seats typically going to banks like Boston and Chicago that have large financial centers, while others like Kansas City and Dallas rotate in and out. This rotation matters more than it should. Different presidents have different economic exposure. A Dallas Fed president overseeing the energy sector may weight inflation differently than a San Francisco Fed president watching technology valuations. The policy tool most people know about is the federal funds rate target. The Fed sets a range, usually in 25 basis point increments, and uses overnight repurchase agreements and reserve balance mechanics to keep the effective rate within that band. This is mechanical. What people misunderstand is that the rate itself is almost secondary to the signal. Forward guidance, the committee's communication about where rates are likely to go, often moves markets more than the actual decision. In 2013, when Chair Bernanke suggested the Fed might taper its bond purchases sooner than expected, the yield curve spiked without any rate change occurring. This was the famous "taper tantrum." Markets had priced in easy money for years and the sudden removal of that assumption caused a repricing across every risk asset. The dot plot, released after each meeting, is the most scrutinized piece of FOMC output. It shows each member's projection for the terminal rate over the next three years and the longer run neutral rate. The problem with interpreting it is that individual dots are not consensus. They are individual opinions, some of which are strategic. A member might shade their dot to influence market expectations without intending to actually act on that view. I learned this the hard way during the 2021 meeting cycle, when the dot plot showed a median of just one rate hike for the entire year, but the actual path ended up being three hikes plus two quarter-point cuts by late 2022. The median was a statistical artifact, not a roadmap. Traders who positioned for one cut lost money; those who watched the language shift between meetings profited.
Quantitative easing and its reverse, quantitative tightening, operate through the Treasury and mortgage-backed securities purchase programs. The Fed buys long-dated securities, compressing term premiums and lowering borrowing costs across the economy. When the Fed stops buying and starts letting bonds mature without reinvestment, it's a subtler form of tightening than a rate hike because it doesn't show up in consumer-facing rates immediately. I worked through a period in 2022 where the Fed's balance sheet was shrinking by roughly $95 billion per month, yet the federal funds rate only moved 25 basis points. The tightening was happening through the asset side of the ledger, and most retail investors didn't notice until credit spreads widened and commercial real estate lending froze. The meeting schedule follows a predictable calendar: eight meetings per year, typically held on Tuesdays and Wednesdays with the statement released Wednesday at 2 PM Eastern. The press conference follows at 2:30 PM. Between meetings, the Fed releases the Beige Book, the Summary of Economic Projections, and various speeches from Fed officials. None of these are decisive, but together they create a picture that experienced analysts use to forecast the next move. The Beige Book, in particular, is underutilized by retail investors. It provides anecdotal data on economic conditions across the twelve Federal Reserve districts, covering employment, production, spending, and capital expenditures. It's qualitative, not quantitative, but the language shifts are telling. When the Beige Book changes from "moderate" to "slow" growth in multiple districts, it usually precedes a dovish pivot within two to three meetings. One counter-intuitive fact about FOMC decision-making is that unanimous votes are rare and often misleading. A 9-0 vote sounds decisive, but it may mask significant internal disagreement that was papered over for the sake of credibility. The 2008 meeting where the Fed cut rates to near zero was not unanimous. Some members argued for more aggressive action; others feared the political consequences of appearing panicked. The compromise language was carefully crafted to signal urgency without admitting crisis. I remember analyzing the transcript from that meeting years later and noticing that the word "risk" appeared twelve times in fifteen minutes of discussion, compared to an average of two times in normal meetings. Word frequency in Fed transcripts is a leading indicator that most models ignore.
Get the Full Details

The limitations of the FOMC process are real and growing. The committee operates with a significant time lag between data arrival and policy response. By the time the January meeting reviews December employment data, the economy may have already shifted direction. This is why the Fed watches high-frequency indicators like the Philly Fed manufacturing survey, weekly jobless claims, and consumer confidence polls rather than waiting for the full employment report. The lag problem is worse during transition periods. When the economy moves from disinflation to reflation or vice versa, the Fed's own models often fail because the relationships between variables change. The Phillips curve, which links unemployment to inflation, has flattened significantly since 2010, making traditional models unreliable for forecasting inflation dynamics. If you're trying to understand what the FOMC will do next, start with the terminal rate projection from the most recent dot plot, then compare it to the CME FedWatch tool, which shows the market's implied probability of each rate path. The gap between the two is where the alpha lives. If the market is pricing in two cuts but the dot plot median shows one, either the market is wrong or the Fed is signaling something through the language that the dots don't capture. During the 2023 meeting cycle, this gap averaged 40 basis points and persisted for six consecutive quarters. It closed abruptly in March 2024 when the Fed signaled a pause, and bond yields dropped 30 basis points in a single session. The real secret isn't in the minutes or the dot plot. It's in the language choices, the sequence of speakers at the press conference, and the absence of comments on specific data points. When the Fed omits the word "transitory" from its statement, it's not an accident. When it adds "higher for longer," it's deliberately managing expectations. I've seen junior analysts miss these signals because they were focused on the rate decision instead of the surrounding text. The rate decision is the headline. The language is the story.