Working Through Auto Loan Numbers Before You Walk Into a Dealership
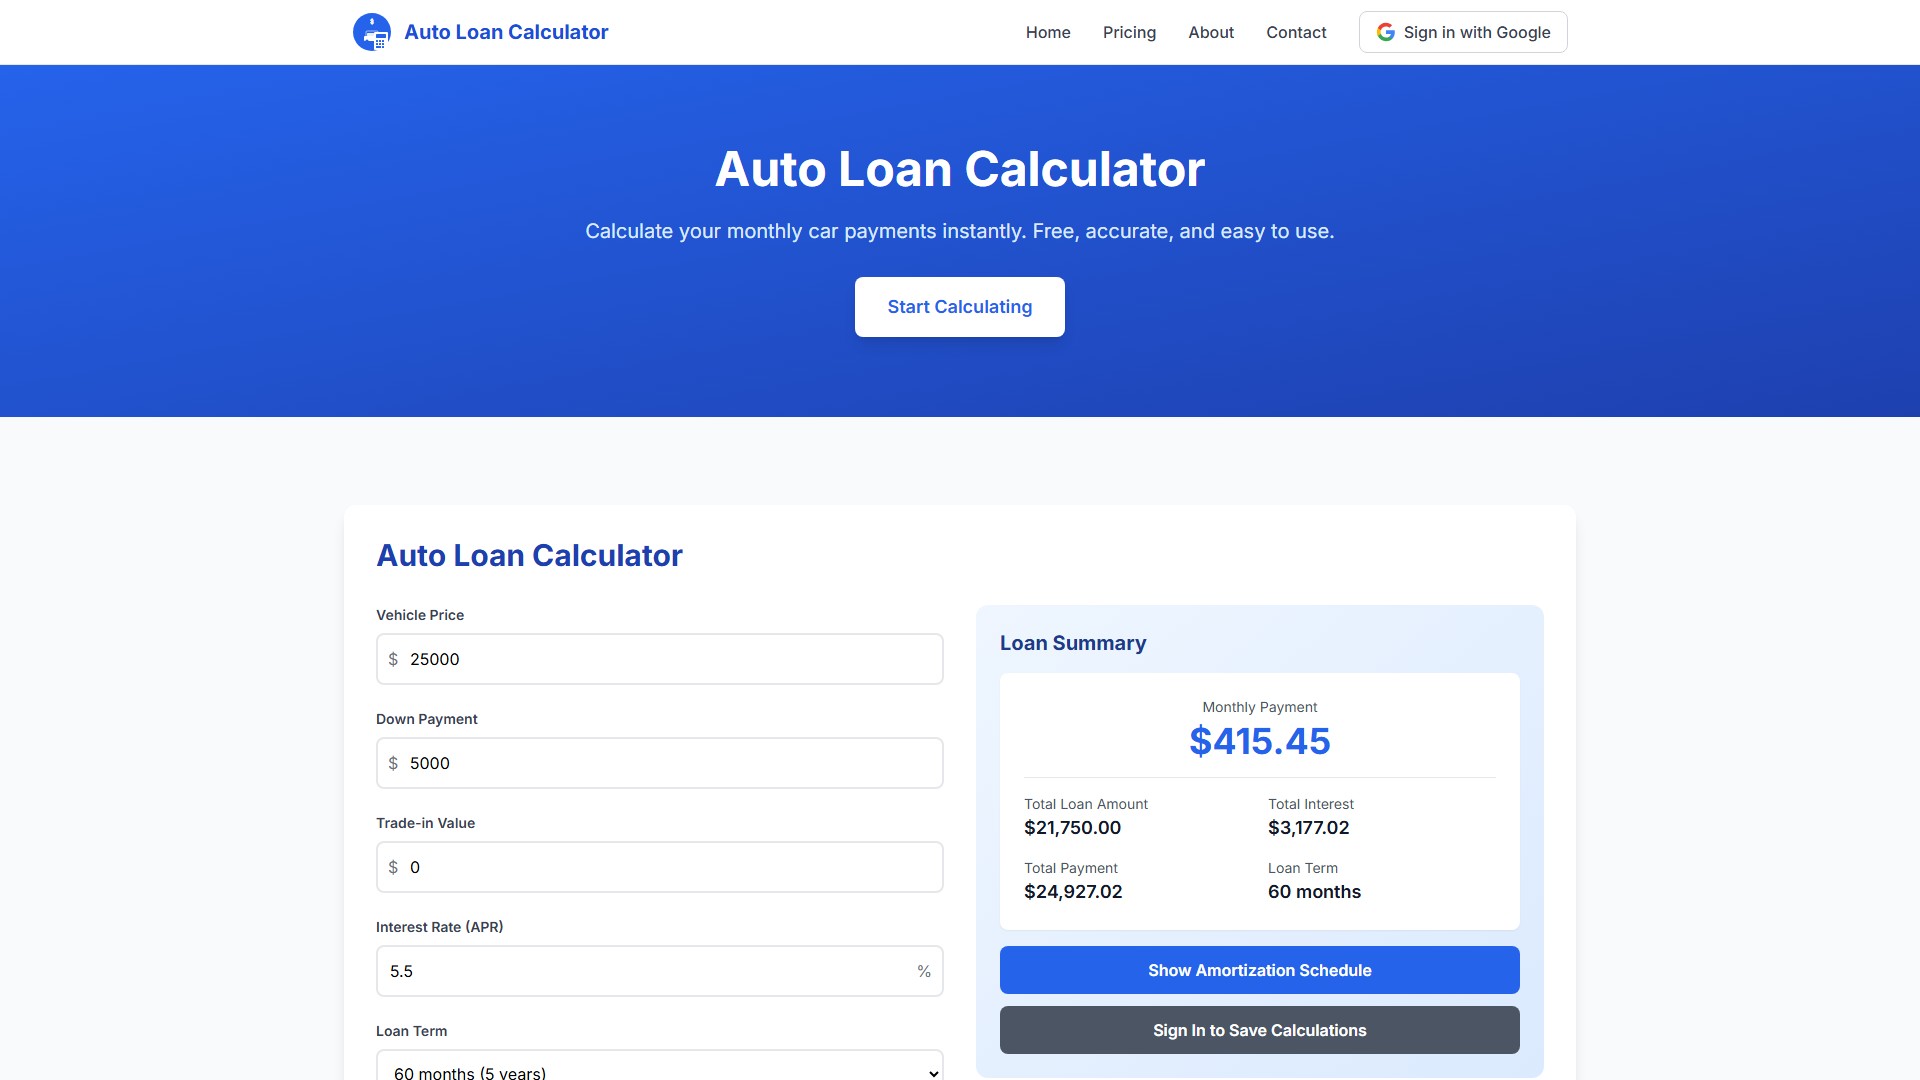
I spend a lot of time helping people understand what their actual monthly payment will be before they sit down with a finance manager. The Suncoast Auto Loan Calculator The Definitive Tool For Smarter Vehicle Financing Decisions has become the standard reference point for that conversation because it mirrors how most subprime lenders structure their numbers. Here is how I use it and what most people miss when they run the first set of numbers.
Getting the Basic Parameters Right
The calculator asks for the vehicle price, your down payment, the interest rate, and the loan term. Input them exactly as you expect them to appear on the contract. Many people make the mistake of entering the total out-the-door price including taxes and fees when they should only put in the negotiated sale price. Leave taxes, registration, and title fees out of the calculator. Those are added later by the lender and will change your final payment. The calculator gives you the baseline number. Everything else gets layered on top. Pro tip: Run the calculation twice. First with your best-case interest rate. Then with a rate five percent higher. The difference between those two numbers tells you how much room you have to negotiate before walking away.
Understanding What the Output Actually Means
The monthly payment shown is not the whole story. It covers principal and interest only. If the lender requires GAP insurance, extended warranty, or other add-ons bundled into the loan, your actual payment will be higher. I always subtract ten to fifteen dollars from the calculator result to account for these hidden costs. The total interest paid over the life of the loan is where most people get surprised. A thirty-six-month loan at eight percent looks reasonable until you see the total interest column. That same payment spread over sixty months might save two hundred dollars monthly but cost you over a thousand in extra interest. The calculator shows both numbers side by side. Pay attention to the total cost, not just the monthly hit.
Get the Full Details

A Real-World Problem With Short Terms
I ran into a specific edge case last month. A customer wanted a twenty-four-month loan on a twelve thousand dollar vehicle. The calculator showed a payment around four hundred dollars monthly. He approved it based on that number. When the lender processed the paperwork, they added mandatory credit life insurance and an electronic reporting fee that pushed his actual payment to four hundred sixty-five dollars. He could not make that payment and was three months behind before he called me. The workaround is simple. Always ask the lender whether there are mandatory add-ons that get rolled into the financed amount. Subtract five percent from the calculator result to give yourself a buffer. If your calculated payment is four hundred dollars, budget for three hundred eighty. That small cushion prevents surprises when the final paperwork lands.
Down Payment Strategy
Putting more money down sounds like the obvious move. It reduces your monthly payment and total interest. But there is a tradeoff most calculators do not show clearly. A larger down payment means less cash on hand for repairs or emergencies. I recommend keeping at least five hundred dollars in liquid savings after the down payment goes through. Run the calculator with different down payment scenarios. Compare a thousand dollar down against two thousand. The monthly difference might look small, maybe thirty dollars. But multiply that by sixty months and you see the real cost of a larger down payment. Sometimes paying a bit more monthly keeps your emergency fund intact.
Negotiating From the Number Backward
Most people start negotiations at the monthly payment. That is backwards. Start with your target number, run it through the Suncoast Auto Loan Calculator The Definitive Tool For Smarter Vehicle Financing Decisions, and work backward to find the maximum vehicle price you can afford. If you can handle four hundred fifty dollars monthly at eight percent over forty-eight months, the calculator tells you the vehicle price before taxes and fees. Use that as your ceiling during negotiations. Dealerships often quote monthly payments to avoid discussing the actual vehicle price. Having the calculator result in hand levels the playing field. You can tell the salesperson exactly what number you need and walk away if they cannot deliver.

When the Calculator Fails You
The tool works well for standard loan structures. It breaks down when you have trade-in values, promotional rates, or stacked manufacturer incentives. If the dealer offers five percent back but requires financing through their preferred lender at twelve percent, the calculator result becomes misleading. The incentive looks good until you factor in the higher rate. In those situations, I calculate the payment twice. Once with the incentive included. Once without. The difference reveals whether the deal actually saves money or just looks attractive on paper. If the promotional rate changes are minimal, stick with your pre-approved lender. The paperwork moves faster and you avoid the temptation of a deal that looks better than it is.
Monthly vs Annual Thinking
Focus on the total cost, not just the monthly number. A sixty-month loan at six percent costs less monthly than a thirty-six-month loan at nine percent. But the total interest paid is higher on the longer loan. The calculator displays both figures prominently. Look at the total interest column before committing to the lower payment. Some lenders offer balloon payment structures where you pay less monthly but owe a large sum at the end. The calculator usually does not show balloon payments clearly. Always ask whether there is a final balloon amount before signing anything. That hidden payment is where people get stuck when the loan matures. Use the calculator as your starting point. Run the numbers. Test different scenarios. Then take those results to the dealership armed with actual data instead of guesses. The tool does not replace negotiation skills, but it gives you the ammunition to make informed decisions instead of emotional ones.