How Cash App Scams Actually Work (And Why Most People Fall For Them)
I spent roughly three years helping friends, family members, and online community groups figure out why they kept getting drained on Cash App. The pattern was always the same: a decent person with good intentions who didn't know the platform well enough to spot manipulation. They weren't stupid. They were just predictable, and scammers know exactly how to press on those buttons. Here's the thing nobody tells you upfront: Cash App's design actively works against fraud detection. Money moves are instant. There's no chargeback window. Once you tap "Pay," it's essentially the same as handing someone cash at a coffee shop. The platform wants frictionless transactions because friction kills engagement. Scammers exploit that frictionless nature relentlessly.
Stop Fake Cash App Scammers In Their Tracks Essential Tips
The most common scam I see isn't some elaborate fake investment scheme. It's the "I accidentally sent you too much, can you Venmo me back" nonsense. Someone overpays you by accident — or so they claim — and asks you to return the difference. When you do, they reverse the original transaction through a support ticket that looks legitimate because they've stolen screenshots from Cash App's help center. You're now out money twice. I had a friend named Derek who lost $847 to this exact scenario. He thought he was being helpful. The scammer had built an entire Facebook group called something like "Cash App Support Help" that looked official enough that even other victims in the group couldn't tell it was fake. Derek forwarded the refund request to what he believed was Cash App support, got a response from a @cashapp-support.net email, and sent the money back. The reversal hit three days later. He never heard from the "support" team again. The workaround that actually works: never process any refund or return through an external link, email, or separate app. If Cash App genuinely processed an incorrect payment, you'd see it reflected in your transaction history as a reversal within the app itself. You never need to click anything outside the app to return money. If someone is asking you to do that, it's a scam, period.
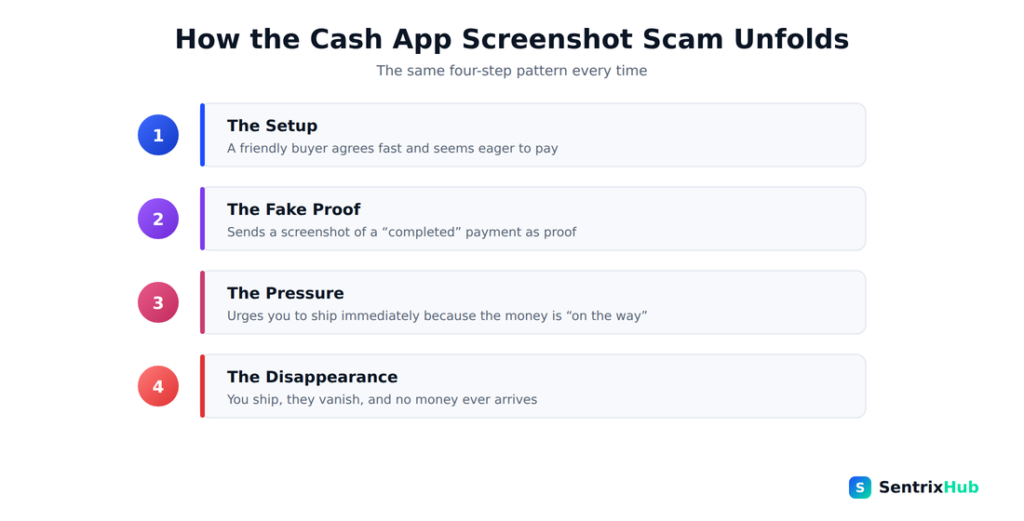
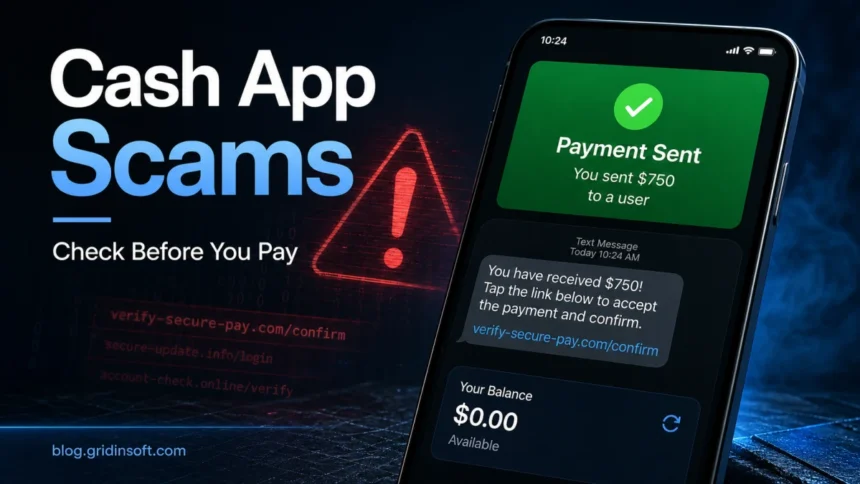
Another tactic that gets people hurt regularly is the duplicate payment request. A scammer sends you the same money twice using two different phone numbers linked to the same $50 payment. They then message you saying one went to the wrong person and you need to send it back. Both payments show as "pending" in your Cash App history, which makes it feel real. But Cash App's pending status doesn't mean the money is actually there. It means it's being processed. Scammers generate pending transactions knowing they have a window of maybe 1 to 3 business days before they get rejected or clawed back. By the time the second payment fails, they've already got your real money. The tip that saves people the most trouble: before you send money back to anyone, check your balance as real cash, not as available balance. Available balance includes pending transactions that haven't settled yet. Your actual cash balance is what you can spend without going negative. If your available balance says $100 but your cash balance says $0, someone is playing you. The impersonation scam deserves its own section because it's evolved significantly. Scammers now create profiles that look exactly like official Cash App social media accounts. They run giveaways. They DM people saying you've been selected for a bonus. You send them a small verification fee of $10 to $50, and they disappear. Or worse, they ask for your Cash App login credentials to "process" your bonus, and then they drain your actual account.
Get the Full Details
Cash App has an official Twitter account and an official Instagram account. That's it. They do not run DM-based giveaways. They do not contact users directly about bonuses. Any message you receive from anyone claiming to represent Cash App through direct message is a scam. I've seen people fall for this into 2025 and beyond, which tells you something about how effective these operations are at manufacturing legitimacy. Here's a counter-intuitive detail most guides miss: the "Cash App Report" feature is useful but limited. When you report a scam within the app, you're not getting your money back. You're flagging the account for review. Cash App may suspend the recipient's account, which prevents them from targeting other people, but they rarely reverse completed transactions. Think of reporting as damage control, not recovery. The only reliable way to recover funds is if the payment is still pending and you cancel it before it processes. Once it completes, you're relying entirely on the goodwill of the person who received it or on law enforcement, which in practice means filing a report with the FTC and your local police and hoping someone cares enough to pursue it. Another nuance: linking your Cash App to a credit card instead of a bank account fundamentally changes your protection landscape. Credit card purchases offer chargeback rights. Bank transfers don't. If someone scams you using a credit card-linked payment, you can dispute the charge with your card issuer. With a bank-linked or balance-funded payment, there's no chargeback mechanism at all. This is why so many scammers push people to pay from their Cash App balance or bank account — they know you have zero recourse.
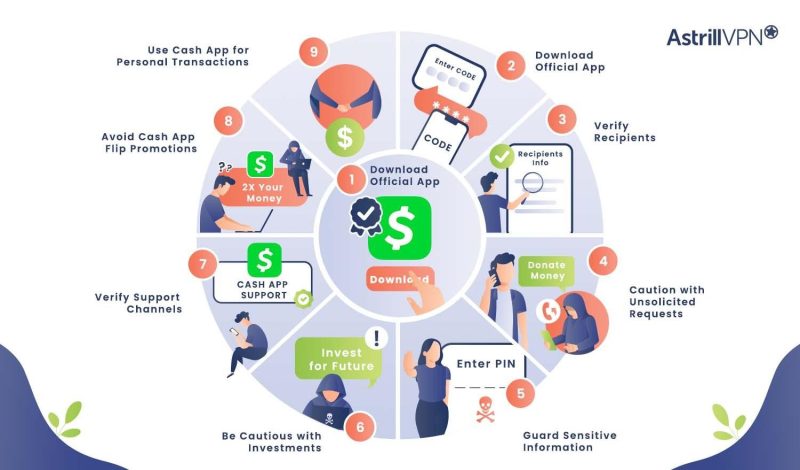
Some practical steps that have worked for people I know: enable the "$" pin lock on your Cash App, which requires a code before any transaction can go through. This stops the "let me quickly send you $5" moment where someone's finger slips while they're distracted. Turn on two-factor authentication using an authenticator app rather than SMS, because SIM-swapping is a real vector and scammers have used it to bypass phone-based 2FA and access victim accounts directly. Restrict who can send you money by setting your Cashtag so only people you approve can initiate payments. The hard truth about verification services and "Cash App scanner" apps that pop up on Reddit and YouTube is that almost none of them work. They can show you whether a Cashtag is real or whether a transaction ID exists in Cash App's system, but they can't detect whether the person on the other end is a scammer. No third-party tool can do that. The only reliable detection is behavioral: if the situation feels urgent, private, or unusual, it probably is. Scammers manufacture urgency because urgency bypasses your critical thinking. If someone you don't personally know in real life asks you to send money on Cash App for any reason — rent split, concert tickets, a "favor," an investment opportunity — stop and run through this checklist. Do you know this person's full name? Have you spoken to them on a voice or video call? Do they have a verifiable digital footprint outside of whatever messaging app you're currently using? If you can't answer yes to all three, you're talking to someone whose identity is unverified. That's not paranoia. That's basic operational security that should apply to any financial transaction, regardless of platform.
The downside to everything I just said is that no tip is foolproof. Scammers adapt fast. They've moved from email to text to Instagram DMs to Telegram groups to Discord servers. They clone real business websites. They use AI-generated voices on phone calls to sound like friends in distress. The only constant is that they all rely on one thing: you acting before you verify. Slow down. Verify independently. Don't send money because someone made you feel like you need to send money right now.