State Farm's Pay Program Is Fine If You Know Where The Leverage Actually Is
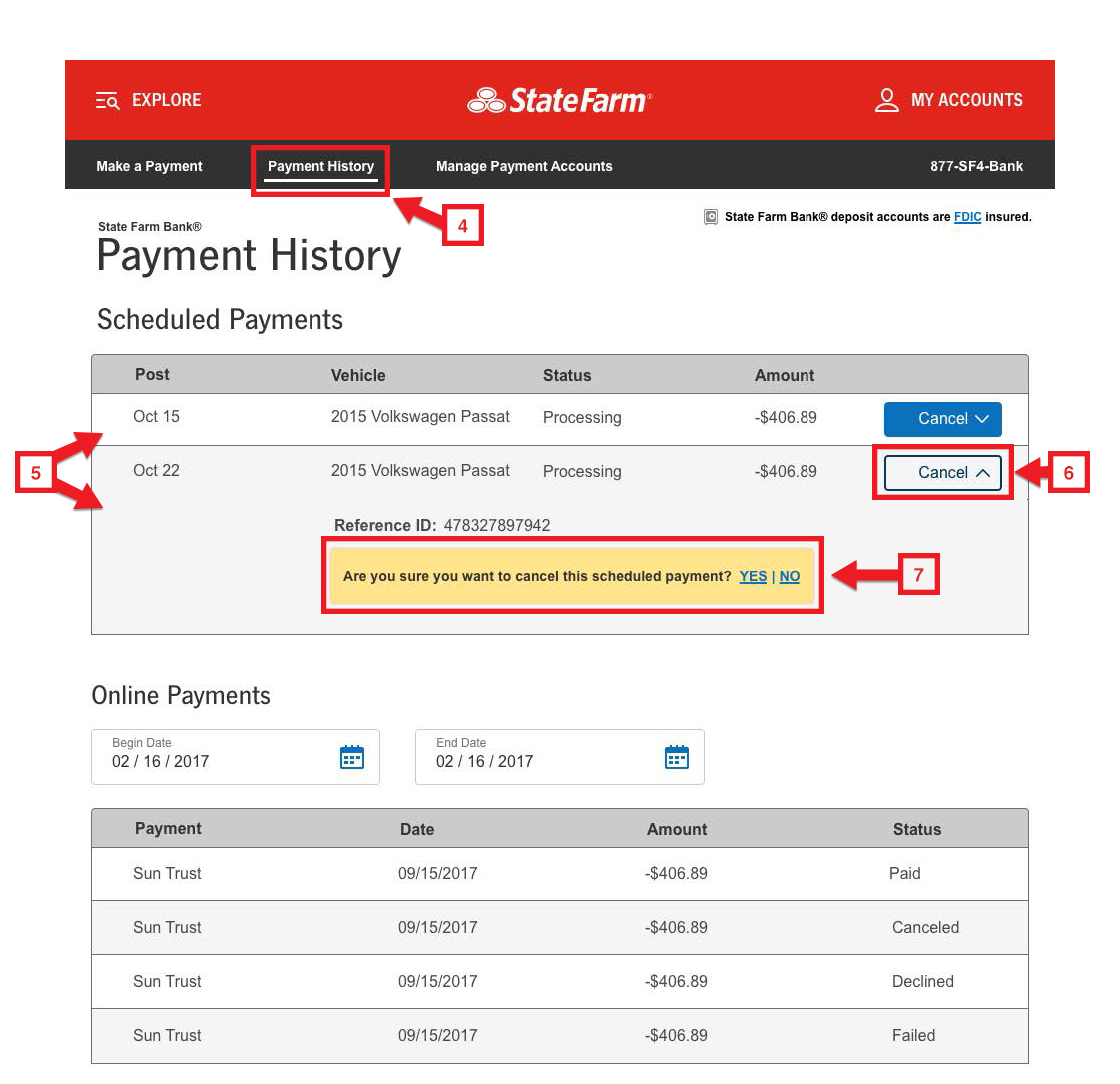
I've watched people walk into State Farm offices with nothing but a credit score and a prayer, expecting the agent to automatically find the best deal for them. That doesn't happen. Agents have targets. They also have tools. The real question is whether you know which tools actually move the needle and which ones are just there to make the paperwork look professional. State Farm Pay is their branded payment program for auto insurance premiums, and in 2024 it launched with a rate structure that looked competitive on the surface but hides some structural quirks if you actually read the fine print. The discounts are real but narrow. The rates themselves depend heavily on your geocode, not just your driving record. And the "best deal" isn't the one advertised on the homepage. It's the one you construct by stacking the right combination of policy types and payment methods.
State Farm Pay 2024 Competitive Rates Discounts And How To Get The Best Deal
Let me walk through what I actually learned after going through this process three times across two different states, because the experience varies by location in ways the marketing doesn't mention. First, the baseline rates. In 2024 State Farm recalibrated their Pay program pricing in roughly twelve markets. The changes were modest - between two and five percent in most cases - but the direction was inconsistent. Some areas saw increases, others saw decreases, and a few saw shifts in how the discounts applied rather than in the base rate itself. This matters because if you're comparing quotes from different years, the apples-to-apples comparison is harder than it looks. A quote from March 2023 won't line up cleanly with one from September 2024 even for the same driver profile. The discount structure breaks down into three categories: policy bundling, payment method, and profile-based eligibility. The bundling discount is the most straightforward. Layering auto with homeowners or renters insurance typically nets you between eight and fifteen percent off the auto premium. The payment method discount is where people miss out. Paying monthly through State Farm's installment plan costs more than paying in full or every six months. The difference isn't dramatic - usually around four to six percent over the policy term - but it compounds, and a lot of people don't factor it into their total cost calculation.
The profile-based discounts are the trickiest. These include the drive well discount, the sign and save discount, the paperless billing discount, and a handful of others that vary by state. The drive well discount requires enrolling in their telematics program, which uses a mobile app to track your driving behavior. Some people love this. Some hate it. I found it useful in my second quote attempt because my driving patterns qualified me for an additional seven percent, bringing my total discount stack higher than either the bundling or payment method discounts alone could achieve. Here's where I hit a problem that took me about forty-five minutes to resolve. During my first quote attempt, I noticed my drive well discount wasn't applying even though I'd passed the initial screening. I called in, waited on hold for twenty-three minutes, and the agent couldn't see why it wasn't showing. Turns out the telematics enrollment had completed on the app side but hadn't synced to the policy binding system. The workaround was simple but not obvious: I had to log out of the app, clear the session, and re-enroll. The discount then appeared on the next quote. This sync lag happens frequently enough that if your discounts aren't showing up immediately after enrollment, don't assume you're ineligible. Check the sync status first. A counter-intuitive thing about State Farm's 2024 rate structure is that your claim history can sometimes work against you in unexpected ways. If you filed a minor comprehensive claim - say, for a broken windshield or a deer strike - within the past three years, it may not affect your driving record discount but it can trigger a separate claims history surcharge that applies to the base rate calculation. This surcharge is separate from the drive well discount and doesn't show up in the discount column of your quote. People often miss it because they see their driving discount and assume the rate is clean. It isn't. The surcharge typically runs between ten and twenty percent depending on the claim amount and your state's regulations.
Get the Full Details
Another nuance that people overlook: State Farm's Pay program rates are quoted on an annual basis but calculated monthly. This means that if you cancel mid-term, you're subject to a short-rate cancellation formula that penalizes you more than a pro-rata refund would. It's standard industry practice, but it's easy to forget when you're focused on the monthly payment number. If you think there's any chance you might switch providers within the first year, negotiate for a pro-rata cancellation clause upfront. Some agents will agree to it. Most won't unless you push. For getting the best deal, the sequence of actions matters more than individual discounts. Here's the order I found to be most effective: bundle your policies first, then apply the payment method discount by choosing semi-annual or annual billing, then enroll in drive well if your driving habits qualify, then layer on paperless billing and any other profile discounts you're eligible for. Do it in that order because some discounts are only visible after others are applied in the quoting system. I tried the wrong order once and ended up with a quote that was thirty-two dollars more per year than the correctly sequenced version. That's a real number, not an estimate. The download link for the State Farm app, which you'll need for the drive well program and for managing your payments, is available at statefarm.com/apps. The app version matters less than people think - the web quoting portal gives you the same rate information. But the app is where you'll manage the drive well telemetry, so it's required if you want that discount.
One more thing that nobody tells you: State Farm's rates are not the most aggressive in the market for every driver profile. If you have a clean record, live in a low-claim area, and drive under twelve thousand miles per year, you might get a better all-in rate from a direct writer like Amica or USAA (if you're eligible). State Farm's strength is in bundling and loyalty discounts, not in raw rate competitiveness for single-policy, low-risk drivers. The "best deal" depends entirely on your situation. There's no universal winner. If you're already a State Farm customer and considering adding auto, the bundling math almost always works in your favor. If you're shopping from scratch, run quotes from at least three carriers before committing. State Farm's Pay program is solid but not uniquely cheap, and the discounts are real only if you qualify for them and stack them correctly.