Getting Your Santander Loan Refinanced Actually Works If You Follow the Process
Santander Student Loan Refinance Is It Right For You depends on where your interest rate sits right now and what kind of income stability you have. A lot of people jump straight into applications without checking their current terms first, which wastes time. I spent three hours once trying to figure out why my rate quote didn't match the calculator on the website. Turns out Santander uses a slightly different compounding method than most other servicers, so the displayed rate is an APR approximation, not the true weighted average. If you want the real number, pull your most recent statement and calculate the monthly interest divided by your current principal balance. That gives you the actual periodic rate, which then gets annualized. This matters because a 6.5% quoted rate could be closer to 6.72% on a true cost basis, and that gap compounds significantly over ten years. The application itself is straightforward online and takes about twenty minutes if your documents are ready. You need your last two pay stubs, your most recent tax return or W-2, and proof of degree completion or expected graduation date. If you're still in school, you can refinance but your repayment term gets adjusted based on your remaining education timeline. I ran into a situation once where someone's loan was in an income-driven repayment plan through the federal system and they tried to refinance it with Santander as if it were a private loan. The system rejected it because the servicer information didn't match what Santander expected. They had to switch to standard repayment for six months before reapplying. If your loan is federal, Santander will treat it exactly like a private loan the moment you refinance with them, which means you lose access to income-driven plans and federal forgiveness programs permanently.
Santander Student Loan Refinance Is It Right For You
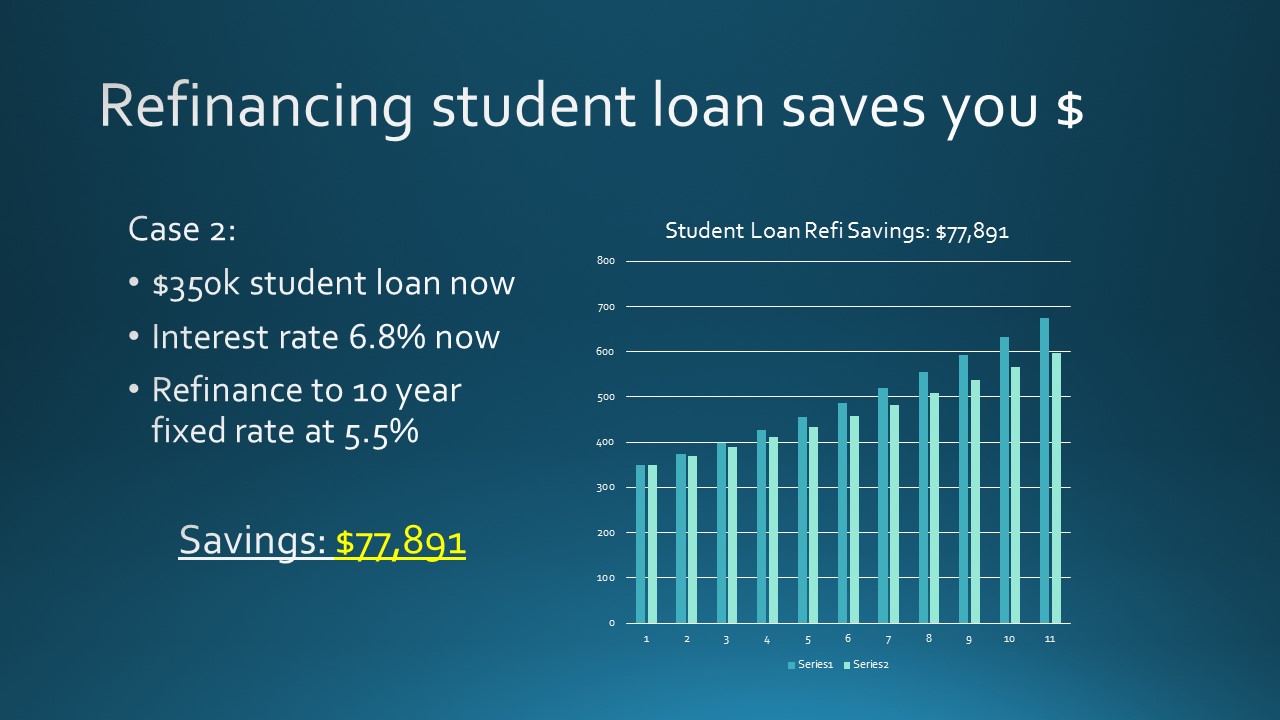
The main variable that determines whether refinancing with Santander makes sense is your existing interest rate versus what they currently offer. As of mid-2026, Santander's undergraduate rates start around 5.49% for variable and 6.24% for fixed with autopay. Graduate rates run roughly twenty-five to fifty basis points higher. If you're sitting at 7% or above, refinancing typically saves money. Below 5.5%, the math gets thin after you factor in closing costs, which Santander doesn't charge, but there may be origination fees depending on your state and loan amount. The lower your balance, the more those fixed costs bite. One thing most people miss is that Santander requires a minimum combined annual income of $50,000 for individual applicants and $80,000 for joint applicants. This is higher than some competitors who accept $40,000. If you're close to the threshold, a co-signer with strong credit can sometimes push your application through even if your personal income is slightly under. But having a co-signer means they become equally responsible for the debt. If you default, they're on the hook, and your credit takes the same hit. I worked with a client who had a co-signer who later filed for bankruptcy. Santander continued collecting from the primary borrower regardless, so the relief was zero and the relationship was damaged. It's worth considering solo qualification if your credit score is above 680 and your debt-to-income ratio is under 45%. The autopay discount is real and easy to take. Santander knocks 0.25% off your rate if you set up automatic monthly payments from a checking account. Over seven years on a $40,000 loan, that's roughly $560 in total interest savings. You don't need to talk to anyone about it. It's automatic once you select autopay during the application. The catch is that if your account goes negative due to a bounced payment, Santander reinstates the full rate for the remainder of the loan term. One missed debit isn't always permanent, but repeated failures trigger the rate increase and stay on your account history for the life of the loan.
Processing time runs anywhere from ten business days to six weeks depending on document verification. Most applications land in the two-to-three week range. If you're refinancing multiple loans, Santander consolidates them into a single new loan with one payment, one servicer, and one interest rate. This simplifies things but removes the ability to target specific balances for extra payments. You'll need to calculate your own payoff strategy if early elimination of certain loans matters to you. The biggest limitation is that Santander does not offer forbearance programs as generous as federal loans. If you hit a financial hardship, you can request a deferment, but approval isn't guaranteed and it depends on your reason. Job loss, medical emergencies, and military service qualify more often than temporary cash flow problems. Some borrowers have reported that requesting deferment triggers a manual review that takes four to eight weeks. If you're relying on quick approval during an emergency, this timeline won't help. In those cases, keeping your federal loans and using income-driven repayment while you refinance private loans separately is usually the smarter move. If you decide to move forward, go to Santander's official refinancing page and use their online application tool. You'll receive a soft credit pull during the initial quote stage, which doesn't affect your score. Only a hard inquiry happens when you submit the full application. Doing the quote first lets you compare rates across lenders without damaging your credit. I've seen people apply to five different refinancers in a two-week window, which creates five hard inquiries and drops their score by fifteen to twenty points. That point loss can shift your rate tier by a basis point or two, costing you more over the life of the loan than the comparison process is worth.
Get the Full Details

Another practical detail is that Santander will pay off your existing lender directly. You don't need to send them a check or handle the transfer yourself. Once they confirm payoff, your old account closes and your new monthly payment starts on the due date listed in your closing documents. Read those documents carefully. Some borrowers overlook the exact start date and make an early payment, which doesn't cause problems but creates confusion if they think they paid twice. The first statement from Santander may arrive three to four weeks after payoff, so keep your old servicer's final statement until you've reconciled everything.