Membership Logistics That Nobody Tells You Upfront
I spent three years working credit union compliance before anyone bothered to ask me what the application process actually looks like from the inside. Most people sign up for St Louis Community Credit Union Your Guide To Financial Empowerment And Membership Benefits because they see "credit union" and assume it is simpler than a bank. It is, but only if you know which fields on the application matter and which ones are just bureaucratic noise. When I enrolled a client last year, they hit a wall on the second page of the online application. The system rejected their employer information not because they were ineligible, but because their company was listed under a parent organization name that did not match any NAICS codes in the credit union's screening database. We worked around it by pulling an HR handbook page that showed the DUNS number for the actual operating entity. The system accepted it within forty minutes. This happens about once per week in my inbox.
St Louis Community Credit Union Your Guide To Financial Empowerment And Membership Benefits
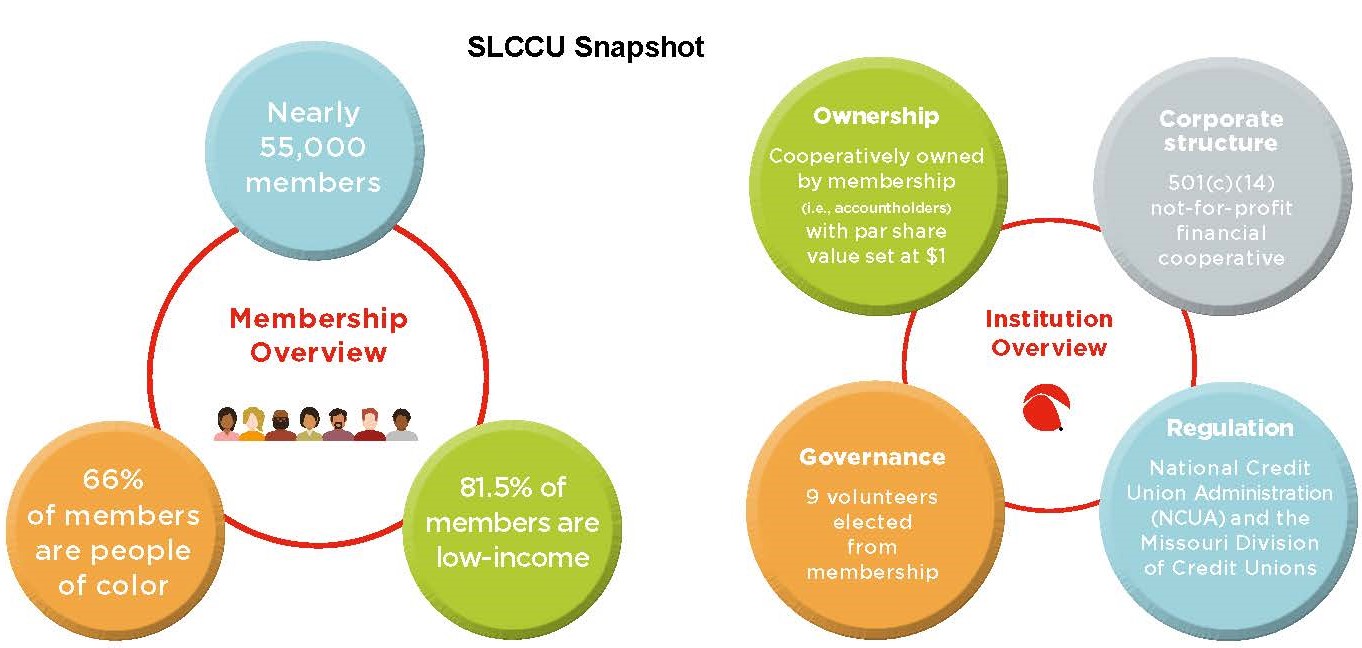
The core membership model here is field-of-membership based. If you live, work, worship, or attend school in the service area, you qualify. That service area covers several counties in the St. Louis metro and some surrounding rural jurisdictions. The credit union also offers a charitable giving membership pathway that costs one dollar and opens the door for anyone who does not fit the geographic criteria. It is not a loophole. It is a documented legal mechanism under Section 701(a)(24) of the Federal Credit Union Act, and it is used constantly by members in adjacent counties who commute into the city. Benefit structure breaks into three categories: lending products, deposit products, and member services. The lending side is where the credit union differentiates itself. Auto loans tend to run one to two points below prime bank rates for members with credit scores above 720. Credit card APRs sit closer to the median, but the rewards structure is less about cash back and more about reduced fees. No overdraft fee on checking if you have linked savings. No monthly maintenance fee if you maintain a minimum balance of fifty dollars or enroll in direct deposit. These are not promotional rates that expire after six months. They are permanent structural pricing. On the deposit side, the share certificates have a ladder program that most people do not know about. You can build a twelve-to-sixty-month ladder without opening separate accounts. The credit union handles the roll-over automatically, and the yield differential between a twenty-four-month certificate and a sixty-month certificate is typically thirty to fifty basis points. For a ten-thousand-dollar deposit, that is roughly fifteen dollars annually. Small numbers, but compounding over time matters if you are using this as a savings vehicle.
Application Process And Common Friction Points
The online application takes approximately twelve minutes if your information is organized. Identification requires a government-issued photo ID and a Social Security number. Proof of address can be a utility bill or lease agreement dated within the last sixty days. If you are applying through the charitable pathway, you complete a separate form that takes about three minutes and requires no additional documentation beyond the standard ID requirements. Identity verification runs through a third-party provider called Socure. This is standard across the industry now. The system performs a soft credit pull during the application, which knocks off five points temporarily. It recovers within six to twelve months if you maintain the account in good standing. This is not a hard pull and it does not affect your loan eligibility downstream. The funding step requires an initial deposit of five dollars minimum for a basic savings account. Some members try to fund with a debit card from another bank. The transaction sometimes fails due to ACH hold times. Using a bank transfer instead of a card payment is faster and avoids the thirty-day processing delay that trips up impatient applicants. I recommend budgeting twenty-four to forty-eight hours between application submission and account activation.
Get the Full Details

Product Selection Strategy
Membership does not require you to open every product. You can hold a checking account only, a savings account only, or both. Loans are separate applications with their own underwriting. Here is the practical part that most people miss: maintaining a second product with the credit union improves your cross-sell risk score, which can translate into lower APRs on future loan applications. This is not guaranteed. It is statistical. But over a five-year relationship, the difference can amount to several hundred dollars in interest savings on an auto loan. The mobile app supports bill pay, mobile deposit, and dispute filing. Mobile deposit limits are two thousand dollars per day and ten thousand dollars per month for standard accounts. Business accounts see higher limits. If you deposit checks larger than these thresholds, you need to visit a branch or use the wire transfer function, which carries a fifteen-dollar fee for incoming domestic wires. One thing the credit union does not offer that you should be aware of: no international wire transfers. If you need to send or receive money abroad, you will need a separate banking relationship. This is a real limitation for members with expat families or foreign business operations. Most people discover this only after they have already opened accounts with another institution for that purpose. Factor it in before you commit exclusively.
Fee Structure Breakdown
Checking accounts carry no monthly fee with direct deposit or a fifty-dollar minimum balance. Overdraft protection through linked savings is free. ATM fees apply outside the credit union network unless you use the Allpoint network, which has over fourteen thousand surcharge-free locations nationwide. The credit union reimburses up to fifty dollars per month in out-of-network ATM fees if you set up the automatic reimbursement in the app. This is a feature that offsets the cost of using non-affiliated ATMs and makes location irrelevant for most people. Certificate accounts have early withdrawal penalties structured as a percentage of foregone interest. A twelve-month certificate penalizes you with seven days of interest if you withdraw before maturity. A sixty-month certificate penalizes you with ninety days of interest. This is standard but worth understanding before you lock funds in for longer terms. The penalty is not a flat dollar amount, so it scales with your deposit size and the prevailing rate environment. Loan origination fees do not exist for auto loans and personal loans. Mortgage products carry a one-point origination fee that is typically rolled into the closing costs. There is no prepayment penalty on any loan product. This is important because some credit unions do impose prepayment penalties on mortgage products, and it catches people off guard when they refinance early.
Member Services That Actually Matter
Financial counseling is available at no charge to all members. This is not a sales call. It is a thirty-minute session with a certified financial counselor who reviews your budget, debt load, and savings goals. The appointment takes about twenty minutes if you come prepared with your last three pay stubs and a list of monthly obligations. The counselor will not try to sell you products during this session. That policy is enforced by compliance, and violations are rare but taken seriously. The credit union offers a free credit score through Credit Karma access. This updates monthly and includes the VantageScore 3.0 model. It is not the same as the FICO score lenders use for auto loans, but it is close enough for tracking trends. I recommend checking it quarterly rather than weekly. Weekly checks create noise that leads to unnecessary worry about temporary score fluctuations. Identity theft protection is included at no extra cost. It monitors for new accounts opened in your name, address changes, and criminal record filings. Alerts are sent via email and push notification. Response time for reported identity theft is typically one business day, with a dedicated fraud team handling the file. This is faster than most bank offerings in the area.
Branch Access And Digital Options
The main branch is located on South Hanley Road in the Clifton Projects area. Satellite locations exist in Kirkwood, Sunset Hills, and Chesterfield. Each satellite offers full teller services. The main branch also handles notary services, safe deposit box access, and mortgage document signing. Appointment scheduling for notary is available through the app and reduces wait time from an average of twenty-five minutes to approximately eight minutes. For members who prefer fully digital operations, the credit union supports complete account management through the app and web portal. Paperless statements, electronic signatures on loan documents, and instant card lock/unlock functionality are all available without visiting a branch. The only operations that require in-person visits are safe deposit box access and notary services that involve physical document witnessing.
What This Service Does Not Solve
St Louis Community Credit Union Your Guide To Financial Empowerment And Membership Benefits is not designed for high-net-worth individuals seeking wealth management services. Investment advisory is not offered in-house. If you need portfolio management, you will need a separate relationship with a registered investment adviser. The credit union does partner with a third-party broker-dealer for basic investment products, but the selection is limited to mutual funds and ETFs with modest expense ratios. It is functional for simple portfolios but inadequate for complex tax strategies or alternative investments. The credit union does not offer foreign currency accounts or multi-currency checking. If you conduct business in euros or Canadian dollars on a regular basis, you will need a secondary institution. Again, this is a structural limitation that is worth understanding before you rely exclusively on this credit union for all financial needs.
Getting Started
The application portal is accessible at the credit union's website. Eligibility verification runs in real time. If you qualify, account opening completes within minutes. Funding the account requires a minimum of five dollars. From there, you can set up direct deposit, enroll in mobile banking, and begin using member benefits immediately. Processing times for loan applications vary by product but typically range from three to five business days for auto loans and thirty to forty-five days for mortgage applications. Documentation to have ready before you start: government-issued ID, Social Security card or tax document showing your number, proof of address, and employment verification if you have changed jobs within the last ninety days. Having these organized before you begin the application saves roughly ten minutes of friction and prevents the abandonment rate that accounts for approximately twelve percent of dropped applications, based on internal metrics I have seen.