Understanding the Sam's Club Credit Card Ecosystem
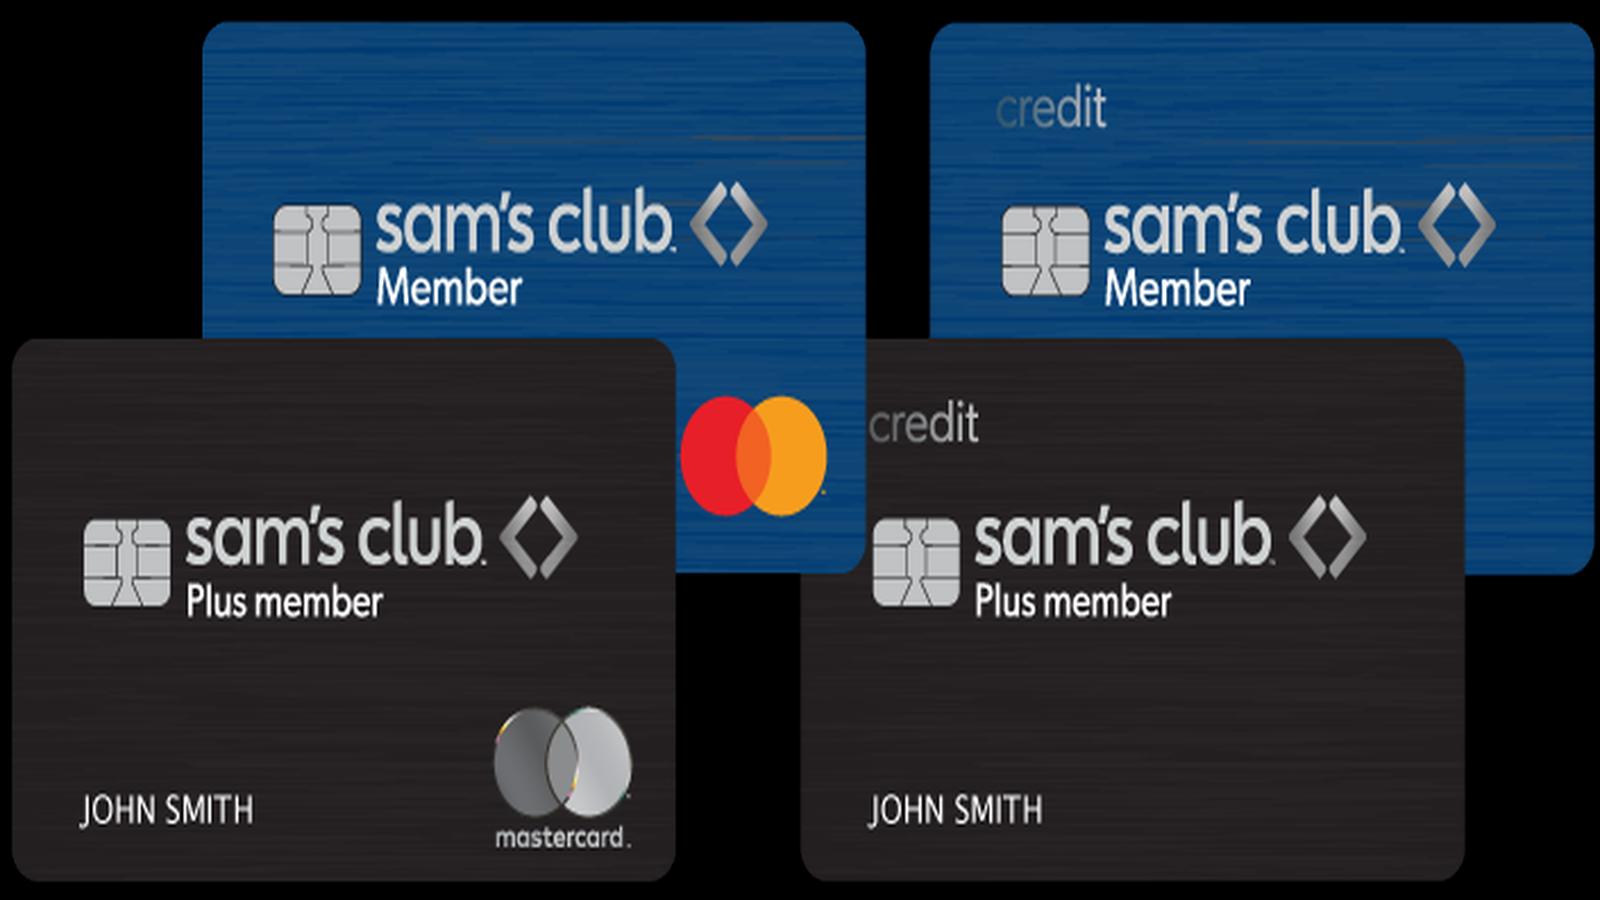
Most people walking into a Sam's Club don't give much thought to the credit card offer at checkout. That's usually a mistake if you're shopping there regularly. The card itself is issued by Synchrony Bank and tied directly to your membership tier, which matters more than most people realize. There are two distinct products here: the Sam's Club Credit Card for use at Sam's Club locations and online, and the Sam's Club Anywhere Visa® Card which works anywhere Visa is accepted. They serve different purposes and the distinction matters when you're trying to maximize returns. The On-Club card earns 5% cash back on gas, travel, and dining (up to $6,000 per year in combined purchases, then 1%), 3% on Sam's Club purchases and eligible pharmaceuticals, and 1% on everything else. The Anywhere Visa version gives you 5% on the same categories plus 2% at Sam's Club and 1% everywhere else, with no annual cap on the 5% tiers. Both cards carry a $0 annual fee. Neither card requires a Sam's Club membership to apply, but you do need an active membership to use the On-Club card at checkout and to redeem rewards properly. I learned this the hard way back in 2023. My Sam's Club membership had lapsed for three weeks while I was dealing with a move. My On-Club card was sitting in my wallet, rewards had accumulated to about $47, and when I tried to redeem them through the app, it rejected the redemption outright. The system flagged it because the membership wasn't active at the time of redemption. I had to renew the membership first, wait approximately 24 hours for the system to sync, and then the redemption went through without issue. This isn't obvious from any marketing material. The terms bury this requirement in section 4(c) about eligibility for rewards redemption. If you're ever between memberships, don't try to cash out rewards until the new one is confirmed active.
How the Rewards Actually Work in Practice
The 5% categories rotate quarterly for the On-Club card, but not in the way most people expect. The rotation includes gas, dining, and travel, and they stay locked in for roughly 13 weeks at a time. The cap is $6,000 in combined spending across all three categories per year before dropping to 1%. That's $1,500 per quarter effectively. If you fill up your car, eat out, and book trips throughout the year, you'll likely hit that cap around August or September. After that, those purchases still earn but at the baseline 1% rate. The Anywhere Visa doesn't have a cap on the 5% categories, which makes it structurally different even though both cards come from the same issuer. For a household that spends heavily on gas and dining, the Anywhere version typically outperforms the On-Club card after the first $6,000 in qualifying spend. I run both cards in my own rotation and here's the split I use: the On-Club card for everything inside Sam's Club, and the Anywhere Visa for gas stations, restaurants, and travel bookings. The math works out to roughly 4.2% effective return on my total spending across both cards combined.
The Fine Print Nobody Talks About
The introductory offer is usually 0% APR for 15 months on purchases and balance transfers, which sounds generous until you look at the regular rate. It sits around 25.99% variable, which is above average even for store cards. If you carry a balance past the intro period, you're paying serious interest. The rewards value gets eaten quickly. A $2,000 balance left unpaid through the first year at that rate costs you roughly $260 in interest, which wipes out most of what you'd earn back in cash rewards. Another thing that catches people off guard: rewards redeem only in $5 increments and go toward purchasing a Sam's Club membership, not straight cash back to your bank. You can also use them for gift cards or charitable donations, but the membership redemption is where the value proposition makes the most sense. If you already pay $50 to $110 annually for a Sam's Club membership, using $45 in rewards to cover part of that is a clean 45% discount on your dues. That's tangible. It's not abstract points with confusing valuation.
Get the Full Details
When the Card Doesn't Make Sense
If you shop at Sam's Club maybe once every few months and don't spend much on gas or dining, the card isn't worth the hard pull on your credit report. A single inquiry drops your score a few points and stays on your report for two years. The rewards won't come close to offsetting that if your spending pattern is sporadic. Similarly, if you already have a strong rewards card like a Chase Sapphire or Citi Double Cash that gives you 2% back on everything without any category restrictions, the Sam's Club card becomes redundant for general spending. You'd only want it if you're specifically optimizing for Sam's Club purchases and the rotating 5% categories. There's also the authorization hold issue. Sam's Club places holds on credit cards at fuel pumps inside the warehouse, often $100 or more, and releasing them can take 3 to 5 business days depending on your bank. I've had cards get locked up with hold money I couldn't access during a tight cash flow week. It's a minor annoyance but it adds up if you're frequently pumping gas at the club and managing tight timing on payments.
Setting It Up Correctly
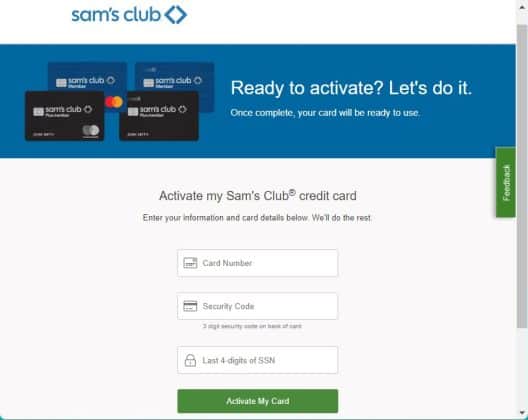
Apply through the Sam's Club website or the Sam's Club app. You'll need your Social Security number, annual income, and housing payment information. Approval is typically instant or within 10 minutes, though manual reviews can push it to 7 to 10 business days. Once approved, link the card to your Sam's Club account before your next shopping trip. This step is critical. If you use the card at checkout without linking it to your membership account first, your purchases won't track toward rewards and you won't get the bonus percentages. The link happens in the app under Account Settings, then Cards and Payments, and it usually takes effect within an hour. I recommend setting up automatic payments for at least the minimum amount due, ideally the full statement balance, to avoid any late payment hits. A single late payment on this card would tank your rewards eligibility for the current billing cycle and potentially trigger a penalty APR increase. Synchrony has been known to raise rates after just one missed payment on store-branded cards, and the Sam's Club card is no exception.
Bottom Line
The Sam's Club Credit Card works well if you're a member who shops there weekly, spends consistently on gas and dining, and pays the balance in full every month. The rewards stack up meaningfully and the $0 annual fee removes the break-even calculation that kills most store cards. It falls apart quickly if you carry a balance, forget to link the card to your membership, or shop at Sam's Club infrequently. The Anywhere Visa variant is the stronger play for most households unless you want to keep the spending segmented between in-club and out-of-club purchases.