Getting Started in the Bay Area Tech Ecosystem
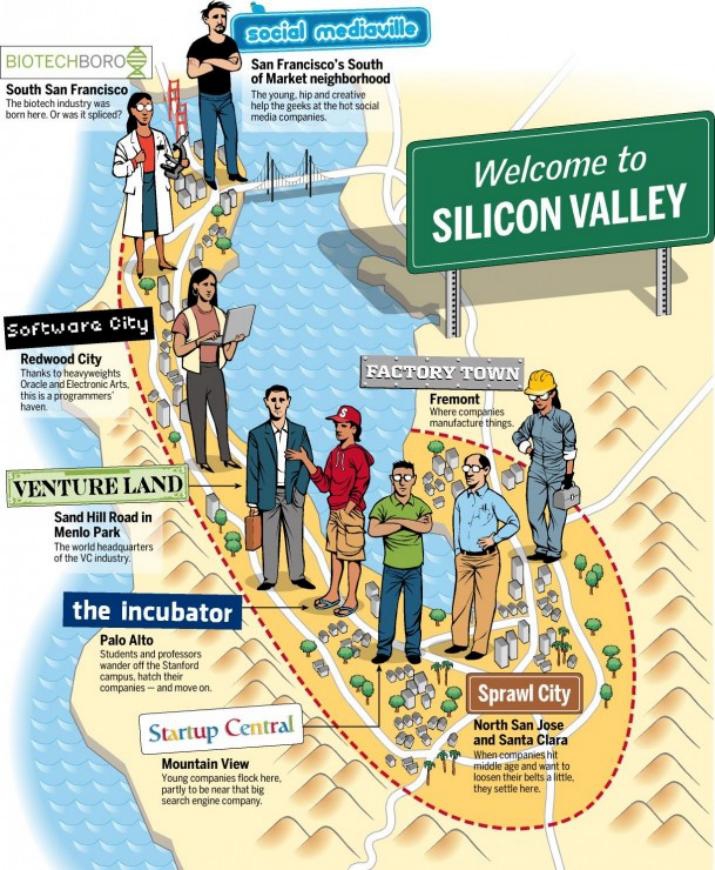
Most people think Silicon Valley is just a geographic location. It isn't. It's a dense network of capital, talent pipelines, institutional knowledge, and repeat founder cultures that operates as an ecosystem. If you move here without understanding how the pieces actually connect, you will waste money and time. I spent seven years working across seed-stage and Series B companies in the area, and the gap between what people expect and what actually happens is massive. The region produces outcomes at a scale that seems almost irrational from the outside. But the mechanics are straightforward once you see them. Venture capital firms cluster here because deal flow is denser. When five promising startups in the same vertical are all within twenty miles of each other, due diligence moves faster, co-investments happen more often, and portfolio companies learn from each other. That density is the real product, not the weather or the coffee shops. What most newcomers miss is that Silicon Valley is less about ideas and more about execution velocity. The typical cycle from idea to funded prototype to first revenue happens faster here than anywhere else on Earth, and the reason is infrastructure. There are people who specialize in incorporation, cap table management, patent filings, and fundraising decks. You can hire someone who has done this fifty times for a company just like yours. In most other regions, you are figuring it out alone. That single factor accounts for more successful exits than any amount of raw technical talent.
I ran into this firsthand when advising a hardware startup in 2022. They were building a new sensor for industrial monitoring and needed to file provisional patents before attending a major trade show. The standard route through a large law firm would have taken six weeks and cost around $12,000. Instead, I introduced them to a boutique IP firm in Palo Alto that specializes in hardware patents for seed-stage companies. They filed clean provisional applications in eleven days for roughly $3,400. The workaround was knowing which firms actually work with pre-revenue hardware teams versus firms that only handle mature tech companies. Without that connection, the startup would have missed their filing window and lost priority on their core patent claims.
The Capital Stack and Where Money Actually Comes From
There is a common misconception that Silicon Valley is dominated by famous venture capital firms like Sequoia or Andreessen Horowitz. Those names exist, but they invest in later stages and in companies that are already validated. The real engine of early-stage entrepreneurship here is a layered capital stack that most outsiders never see. At the bottom are bootstrapped founders and friends-and-family rounds. Then come micro-VCs and angel syndicates, many of which operate out of converted houses in Palo Alto or shared office spaces in San Mateo. These groups write checks between $25,000 and $250,000. Above them are seed funds, followed by Series A through C investors. Each layer has different expectations, different decision timelines, and different demands on your company. A critical detail that beginners consistently overlook is that Silicon Valley investors expect you to understand your unit economics before they hand over significant capital. This is not a universal truth across all venture ecosystems. In some regions, investors will fund based on vision and traction alone. Here, the math has to work on paper first. If your customer acquisition cost exceeds your lifetime value by more than a factor of three, you will not get a follow-on meeting. I have seen perfectly good engineering teams shut down after Series A because their gross margins were too thin to support the growth path their investors expected.
Get the Full Details
Another thing worth noting is that equity dilution here is aggressive by design. A typical Series A round will ask for 20 to 25 percent of the company. This is standard, not predatory. The expectation is that future rounds will further dilute early stakeholders, and that is factored into the original cap table. If you resist reasonable dilution terms in the early stages, you will find that the remaining investor pool shrinks dramatically. Vendors and accelerators both operate on this principle.
Talent Acquisition in a Competitive Market
Hiring in Silicon Valley is simultaneously the easiest and hardest part of operating here. The talent pool is deep. You can find engineers who have shipped production systems at Google, Meta, or Stripe within a single weekend of networking events. The problem is that everyone else is also looking for those same people, and the compensation packages required to attract them have risen sharply over the past decade. A senior software engineer with three to five years of experience will typically command between $180,000 and $260,000 in total compensation, including base salary, bonus, and equity. Senior engineers with systems-level expertise or deep domain knowledge in areas like distributed databases, ML infrastructure, or cybersecurity can expect offers well above $300,000. This is not, and it applies to most roles, not just engineering. One effective workaround I use when advising early-stage companies is to structure compensation differently. Instead of competing on base salary alone, you can offer meaningful equity grants with vesting schedules that extend beyond the standard four years. Some candidates, particularly those who are themselves founder-material or deeply aligned with the mission, will accept slightly lower cash compensation for a larger ownership stake. This approach does not work universally. Many engineers prefer cash stability, especially if they have mortgages or families. But for the right candidates, it is a legitimate strategy.
Operational Pitfalls That Kill Startups Before They Scale
The most common reason startups in this ecosystem fail is not lack of funding or lack of market demand. It is operational drift. The company grows fast enough to hire people, but not fast enough to build the internal structures that handle that growth. I have watched this happen repeatedly. One specific pattern involves pricing strategy. Founders in Silicon Valley often price their products too low in the early stages because they are trying to maximize adoption. This creates a false signal. High user numbers with low per-user revenue look attractive to some investors, but they mask a fundamental problem: the business model may not be viable at scale. When you eventually raise the prices to sustainable levels, you lose the very users you were optimizing for, and the churn data looks catastrophic. The fix is to establish a pricing floor before you reach critical mass, even if it means slower initial growth. Revenue per customer matters more than total customer count in the long run. Another frequent failure mode is over-reliance on a single investor or a single enterprise customer. I worked with a company that derived 70 percent of its revenue from one buyer. When that buyer renegotiated its contract and cut the spend by half, the company went from profitable to insolvent in ninety days. The investor who had been supporting them could not justify doubling down on a deteriorating account. Diversification is not a buzzword here. It is a survival requirement.

Building Legitimate Presence Without Falling for Hype
There is an entire industry built around Silicon Valley access. Incubators, accelerators, networking events, and mentorship programs all charge fees or demand equity in exchange for introductions. Most of them provide genuine value. Some of them are extraction mechanisms that prey on inexperienced founders. The filter is simple. Any program that guarantees funding, promises specific investor introductions, or demands more than a standard 7 percent equity stake for a three-month accelerator should be treated with immediate skepticism. Legitimate accelerators like Y Combinator or Techstars have transparent terms and a track record you can verify independently. Unknown programs with impressive-sounding names and vague success stories are the ones to avoid. If you are evaluating whether to participate in any Silicon Valley program, ask for their published placement data. Reputable operators will provide it. Those who deflect or give vague answers are not going to help you build a company. I have seen too many founders sign agreements with programs that offered nothing beyond a shared workspace and a LinkedIn endorsement. The cost was real equity that was never redeemed.
When Silicon Valley Is Not the Right Move
Operating here has real costs. The burn rate for a small team in San Francisco or Palo Alto is 40 to 60 percent higher than in most other U.S. tech hubs. Office space, salaries, and even basic living expenses compress your runway significantly. A company that could raise $2 million and last eighteen months in Austin or Denver might survive only nine to twelve months in the Bay Area with the same budget. For certain types of businesses, this is simply not worth it. Consumer apps, B2B SaaS with remote teams, and companies that do not require proximity to venture capital or specialized talent pools can operate just as effectively from elsewhere. The network effects of Silicon Valley matter most for hardware companies, deep tech ventures, and businesses that need to raise significant venture capital quickly. If your company does not fall into those categories, the geographic advantage may be outweighed by the increased operational costs. The bottom line is that Silicon Valley is an accelerator, not a guarantee. It amplifies whatever you bring to it. Good ideas get better funding and faster iteration. Weak ideas get exposed more quickly because the scrutiny is higher and the competition is fiercer. Understanding that distinction before you commit resources is the difference between building something sustainable and burning through your runway on hype.