Why Everyone Is Getting Screwed On Paper Trails Now
Fake bank statements are everywhere. I run a small compliance outfit handling loan applications and mortgage docs for people who can't quite qualify, and I can tell you the volume has shifted in the last eighteen months. Not a little. The kinds of PDFs landing on my desk used to have obvious tells within the first thirty seconds. Now they don't. The watermarks match. The routing numbers are correct. The fonts are right. And then you look at the transaction timestamps or the spacing on line items and something is just off by a fraction of a percent. People don't usually create these to commit major fraud. More often it's someone applying for a car loan who got paid in cash and needs the numbers to look like a steady paycheck. Or a freelancer trying to get approved for an apartment and fudging the deposit amounts because their actual income jumps around too much between months. The motive is almost always minor. The systems they're tricking, though, are not.
Rising Tide Of Fake Bank Account Statements A Growing Concern
The trend I'm tracking isn't new in concept, but the delivery mechanism has changed. Ten years ago you needed Photoshop and patience. Today there are templated generators that spit out perfectly formatted CSV-to-PDF outputs with correct bank headers, account numbers that follow the right check-digit algorithm, and transaction histories that simulate months of activity in under three minutes. The templates are shared in private Discord servers and Telegram channels. Some of the best ones cost twenty dollars a month. That's it. That's the entire product. I checked one of these services last quarter. Not for me, for verification. The output looked identical to a Chase PDF I had on file from a real client. Same green color bars on the header. Same footnote language about electronic authentication. I spent maybe four minutes looking for the tell before I found it — the decimal alignment on the "Opening Balance" line was one pixel off from standard rendering. Most processors wouldn't catch that. A human with experience might, if they were actively looking. But the average underwriter sees a bunch of numbers and nods. They don't measure pixel alignment. What makes this worse is that the banks and lenders don't always care. Yes, they say they verify. But the actual verification step is often outsourced to third-party data aggregators like Plaid or MX, which pull from open banking APIs. Those APIs return real data from real accounts. The fake statement problem shows up in the gap between what the API returns and what the applicant submits as supporting documentation. If the document doesn't match the API feed, some lenders flag it. Many just file it and move on. The ones who don't flag it are the ones making money off processing volume, and they're fine with that.
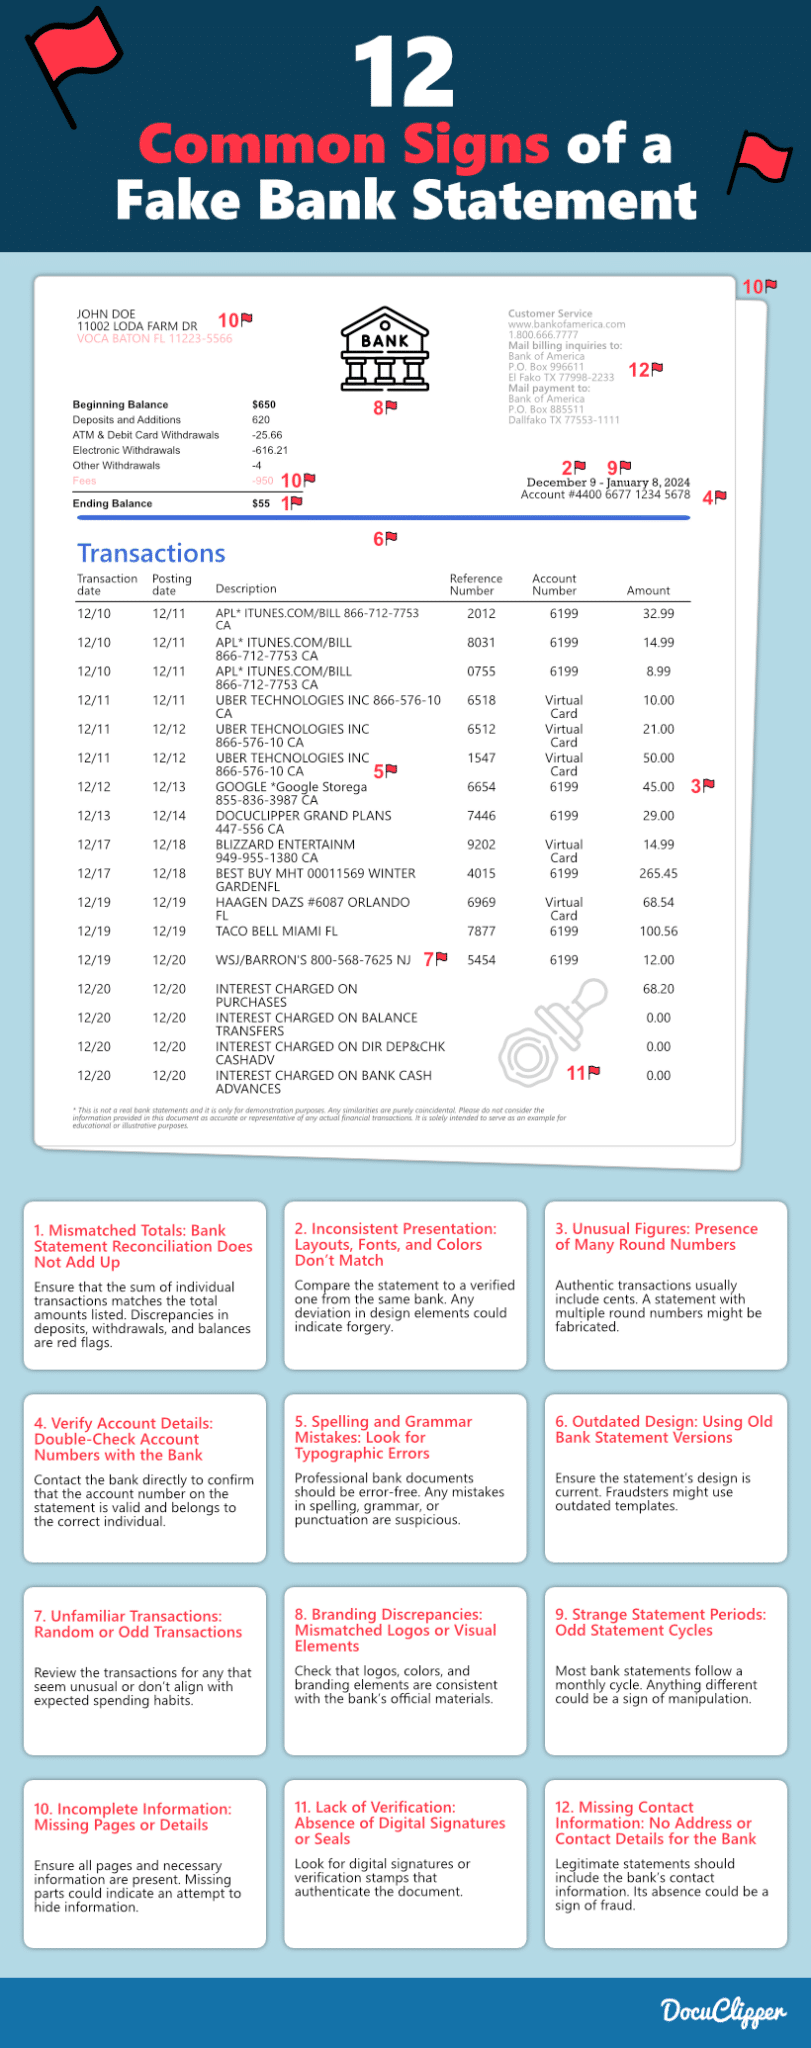
I had a case last November where a borrower submitted a statement that was mathematically perfect but temporally impossible. The deposit on the 15th was exactly $4,312. The deposit on the 30th was exactly $4,312. The 1st was $4,312. This was supposed to be a self-employed contractor. Nobody gets paid the same round dollar amount on different schedule dates every single month for twelve months. The rounding pattern was too clean. I rejected it and asked for W-2s instead. The application collapsed. The borrower came back three days later with a new statement where the amounts varied by $12 to $87 between months, which should have been a bigger red flag, honestly, because real humans are messier than that. But the processor accepted it because the formatting was better. That's the real problem. The quality bar keeps rising while the detection tools stay the same. The software used to catch fake statements — image forensics, font analysis, metadata scanning — was built for a different era of document forgery. Modern generators account for those detection vectors. They render at the correct DPI. They embed the right XMP metadata. They use the actual bank's typeface library. What they still can't do is simulate the behavioral randomness of real financial activity. And that's where the cracks appear if you know where to look. Here's what I've found after reviewing probably two thousand statements over the past few years. The tell is never in the header. It's in the transaction granularity. Real bank statements have small, weird, useless transactions. A $0.47 charge at a laundromat. A $12.99 subscription refund that appears three months after the original charge. A $0.01 balance adjustment labeled "interest correction." Fake statements don't have these because the person generating them doesn't think about them. They include the big deposits and the expected bills. They leave out the noise. The noise is the real data.
Get the Full Details
Another thing nobody mentions: check the date format consistency. Some generators produce statements where the monthly sections use MM/DD/YYYY and the transaction lines within use DD-Mon-YYYY. The bank's actual template doesn't switch mid-document. A real institution maintains one formatting standard throughout. A template generator might pull from different source files and not notice the mismatch. It happened on a Wells Fargo document I reviewed last spring. The header said one thing, the body said another. I caught it because I was already looking at formatting. An automated system would never notice. If you need to understand this from the other side — say you're trying to produce a statement that won't get flagged — the countermeasures are straightforward but tedious. You'd need actual account data from a real statement as a base template. Fill in the deposits with amounts that don't repeat. Vary the transaction descriptions. Include at least three to five truly random small charges per month. Make sure the dates align with a real calendar. Check that the routing number matches the account number's bank code. Get the footer disclaimer text exactly right. It takes maybe forty-five minutes to do properly, and if you mess up one detail the whole thing looks fake because it looks too perfect. Over-correcting is the most common failure mode. People add so many "realistic" details that the statement becomes a caricature of what a real one looks like. The tools themselves are getting better at this. I've seen versions now that use AI to generate the random transaction noise. Which is ironic, because the same AI that helps people make fake statements also helps banks detect them. There's no real arms race win here. It's just a loop.
What you should actually do if you're worried about this, whether you're a lender or just someone trying to verify a document yourself, is stop looking at the document and start looking at the source. Ask for the raw API data if you're a lender. If you're a human being checking a friend's statement for a rental application, ask them to show you the mobile banking app alongside the PDF. The app won't lie. The PDF can. The friction of that request alone deters most people from using fakes in the first place because they're not prepared to produce the live account in real time. I keep a spreadsheet of the patterns I've seen. Not because it's useful for anything beyond my own reference, but because the variety is genuinely surprising. Someone once submitted a statement that was a perfect forgery except the account holder's name was spelled correctly in the header but had a typo in the transaction detail section. Another had a routing number that belonged to a credit union that had been merged out of existence in 2019. These aren't sophisticated operations. They're people who found a template online and filled in their details without checking the fine print. The fake statement industry is mostly hobbyists and desperation, not organized crime. That makes it harder to regulate and easier to ignore, which is probably why it's growing so fast. The bottom line isn't dramatic. It's just that the cost of producing a convincing fake has dropped to basically zero, and the cost of verifying one hasn't dropped at all. The people who need fake statements the most are the ones least likely to be caught by current systems, and the systems that would actually catch them are the ones that most lenders have stopped using because they slow down approval timelines. Speed wins. Always does.