Understanding Reid Hoffman's Financial Position
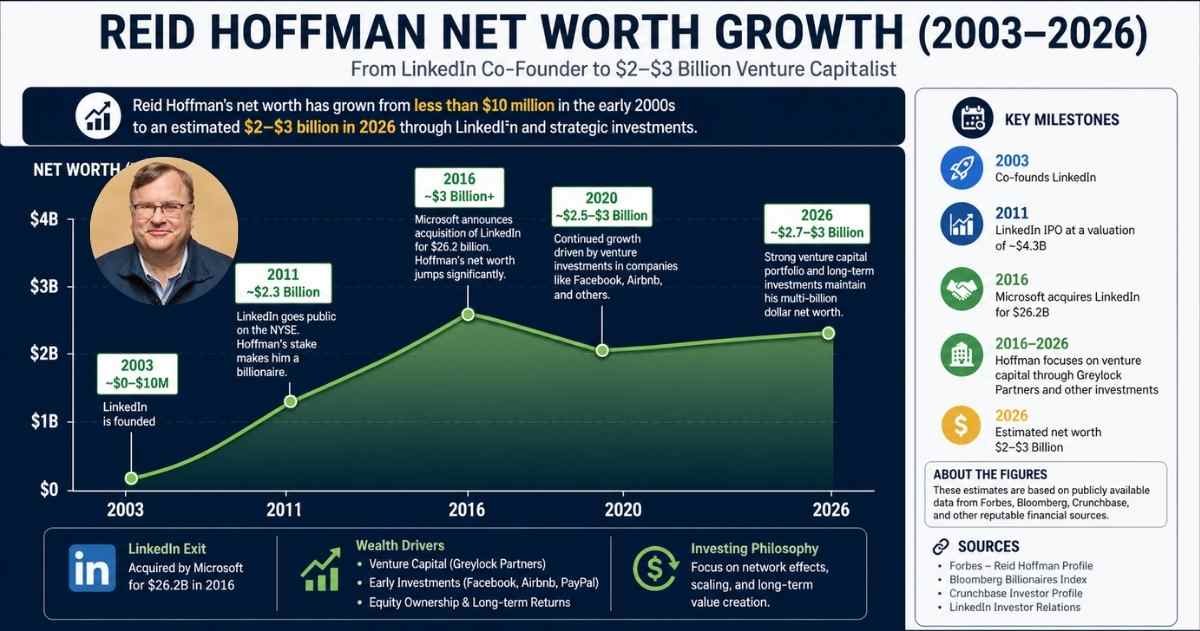
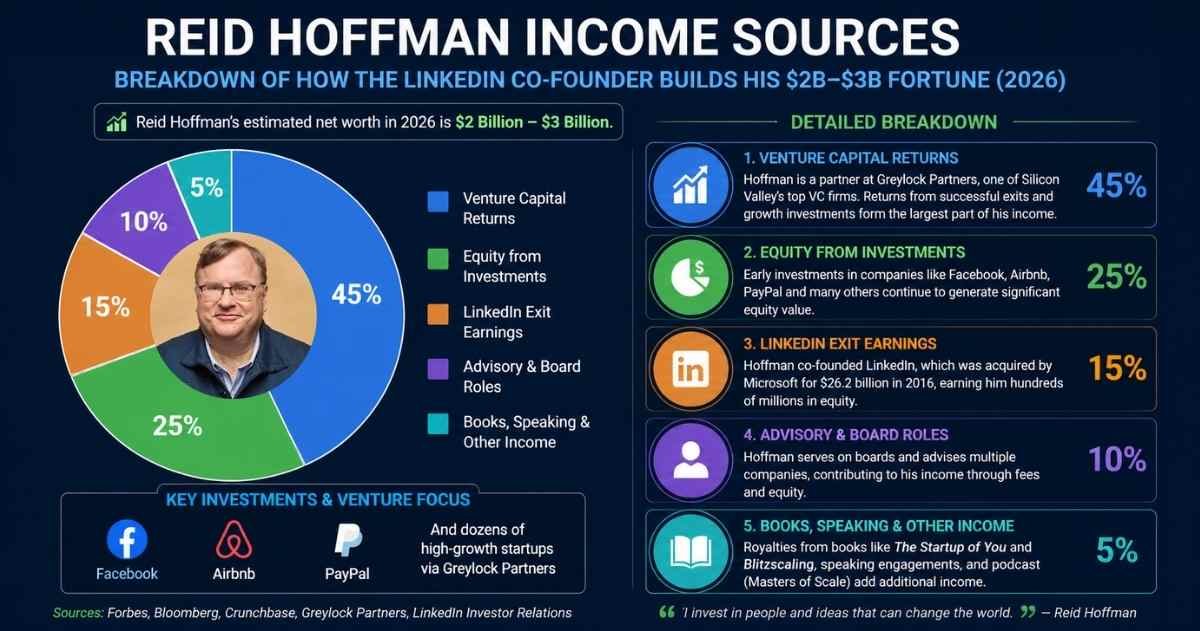
The numbers floating around the internet about Reid Hoffman net worth How Much Is Reid Hoffman Worth The Mastermind Behind Linkedins Billiondollar Network tend to bounce between $800 million and $1.6 billion depending on which site you check and what stock price was used that week. The variation exists because most of his wealth is tied up in illiquid assets, private company equity, and venture fund interests that don't have a fixed daily market price. Forbes and Bloomberg will cite different figures on any given day, not because they have conflicting information, but because their methodology for valuing late-stage private holdings differs slightly. The core of his wealth breaks down into several distinct buckets. The biggest single component is his stake from the LinkedIn exit. When Microsoft acquired LinkedIn in 2016 for approximately $26.2 billion, Hoffman held roughly 14-16% of the company at various points depending on when options vested and shares were sold. This single transaction generated somewhere in the neighborhood of $3 to $4 billion in paper value before taxes and before he started disposing of positions. He didn't sell everything at once. Most executives in that position sell gradually over several years to manage tax brackets and market exposure. Beyond LinkedIn, his income streams come from three main sources. First is his role as a general partner at Greylock Partners, where he's been a partner since 2000. Greylock manages roughly $8 billion in committed capital across multiple funds, and partners earn carry from successful exits. Second is his personal angel investing through the Hoffman Family Foundation and direct checks, which includes early stakes in companies like PayPal, Facebook, Airbnb, Zynga, and Dropbox. Third is his work on the advisory and board side, though that generates relatively modest income compared to the equity plays.
Reid Hoffman Net Worth How Much Is Reid Hoffman Worth The Mastermind Behind Linkedins Billiondollar Network
Here's something most people miss about how venture capital net worth actually works in practice. When you see a figure like "$1 billion+" attached to someone like Hoffman, it doesn't mean he has a billion dollars in cash or even in publicly traded stock. A significant portion sits in illiquid private company shares that can't be sold without a liquidity event or a secondary transaction. These valuations come from the last funding round, which could have been 18 months ago, and the actual liquidation value might be substantially different depending on market conditions at exit time. I've worked with founders and executives who needed to understand this distinction when structuring compensation packages and personal financial planning. The gap between reported net worth and spendable liquidity is where most people get surprised. You might be worth a billion on paper but have maybe fifty to eighty million in actual liquid or near-liquid assets depending on vesting schedules, lock-up periods, and tax obligations. Hoffman's situation is probably less extreme than a typical startup founder because his wealth is more diversified across public and private holdings, but the principle holds. The PayPal Mafia connection is relevant here too. Hoffman co-founded PayPal and sold it to eBay for $1.5 billion in 2002. He walked away with roughly $100 million before taxes, which is already substantial but nowhere near the LinkedIn payout. That earlier exit is what funded his early angel activity and gave him the track record that landed him the Greylock partnership. The compound effect of reinvesting those PayPal proceeds into early-stage bets over fifteen years is what created the bulk of his later wealth.
Where the Valuation Gets Messy
Private company equity valuation is the biggest source of uncertainty. Hoffman holds stakes in companies that haven't gone public, and the reported values are based on the most recent funding round price. If a company raised at a $10 billion valuation two years ago and hasn't grown much since, that's still the number on paper. If the company is struggling, the real value could be much lower. If it's booming, it could be higher. There's no daily mark-to-market. Tax considerations also play a role in how much actual wealth he retains versus what gets reported. Net worth figures typically show pre-tax value of assets, not what he'd walk away with if liquidating everything. Capital gains taxes, state taxes, and potentially qualified small business stock exclusions under Section 1202 all factor into the real number. Some of his holdings may qualify for favorable tax treatment if they meet the requirements, which could meaningfully change the after-tax picture. The Malala Fund and his philanthropic activities through the Hoffman Family Foundation represent another adjustment. He and his wife Priscilla Chen have committed significant portions of their wealth to charitable causes, including education initiatives and global development work. This doesn't change the gross net worth number, but it does affect the net available wealth and how much stays in investment vehicles versus getting distributed.
Get the Full Details
What Actually Moves the Number
LinkedIn's performance as a publicly traded company before the Microsoft acquisition was a major driver. The stock went public at $42 per share in 2011 and traded in the $60-$80 range for several years before the acquisition talks. Hoffman's shares would have appreciated substantially during that period. The acquisition itself at $196 per share represented roughly a 2.5x multiple from the IPO price, which is solid but not extraordinary for a tech company of that era. Greylock's fund performance directly impacts his compensation. The firm's returns on portfolio companies like Slack, Snowflake, DoorDash, and UiPath would generate significant carry distributions. Venture capital carry is typically 20% of profits above a hurdle rate, and when you're managing multi-billion dollar funds with multiple vintages, the carry can be substantial. However, carry only materializes when exits happen, which creates lumpy income streams that don't show up evenly year to year. Recent market conditions matter more now than they did five years ago. The 2022-2023 market downturn depressed valuations across the venture space, which would have knocked down the paper value of many private holdings. If Hoffman's private equity positions are marked down, his reported net worth takes a hit even though the underlying businesses may still be operational and generating revenue. This is why figures vary so much between sources and over time.
Common Misconceptions
One thing people get wrong is assuming that being a venture capitalist automatically makes you wildly wealthy. Most VCs never see a liquidity event large enough to change their life. The power law distribution in venture capital is extreme, and the handful of hits cover the losses from everything else. Hoffman succeeded because he was in the right firm at the right time with the right network, and because he took personal investor risk on top of his GP commitments. That's different from the average LP or junior partner at a mid-tier firm. Another misconception is conflating revenue with net worth. LinkedIn generates billions in annual revenue, but that's Microsoft's revenue now, not Hoffman's. His benefit came from owning equity in the company before the acquisition, not from any ongoing royalty or salary tied to LinkedIn's current performance. The same logic applies to any company he invested in personally—his return depends on the exit multiple, not the ongoing business revenue. Some sources also overstate his involvement in specific companies. Being an early investor or having a board seat doesn't mean you control outcomes. Many of his most successful bets, like Airbnb or Dropbox, were led by other investors or grew largely independent of his direct input. His edge is mainly in deal flow and timing, not operational control.
The Practical Takeaway
If you're trying to understand where a figure like Hoffman's net worth actually comes from, the answer is straightforward: LinkedIn equity plus compound venture returns over twenty-five years, not any single brilliant move. The LinkedIn exit provided the capital base, and the subsequent angel and fund investments multiplied it. The reported numbers should be treated as estimates with a wide confidence interval, not precise measurements. The most useful way to think about it is that Hoffman converted a successful entrepreneur exit into venture capital leverage, then used that leverage to build a diversified portfolio that benefited from the largest wave of tech company creation in history. That's a specific combination of timing, skill, and network access that doesn't generalize well to other people trying to replicate it. The net worth figure is just the trailing indicator of that process, and it will keep fluctuating as private valuations get marked and public positions move.