What a Mortgage Recast Actually Is
A recast is not a refinancing. Your interest rate stays the same. Your loan term stays the same. You simply make a large lump-sum payment toward principal, the lender reamortizes the remaining balance over the original schedule, and your monthly payment drops. That is it. There is no new application, no credit check, no closing costs, no appraisal. Most lenders charge a flat fee somewhere between 500 and 1000 dollars, sometimes a percentage of the recast amount, sometimes nothing at all depending on the servicer. The difference between a recast and a refinance is important because people routinely confuse the two and waste weekends filling out paperwork for something they did not need. A recast leaves your existing loan intact. A refinance replaces it entirely. If you already have a 3.25 percent rate in 2026, refinancing probably makes no sense unless you are pulling cash out or dropping into a significantly shorter term. Staying put and paying down principal is usually the smarter move.Recast Mortgage Calculator How To Recast Your Mortgage And Save Thousands
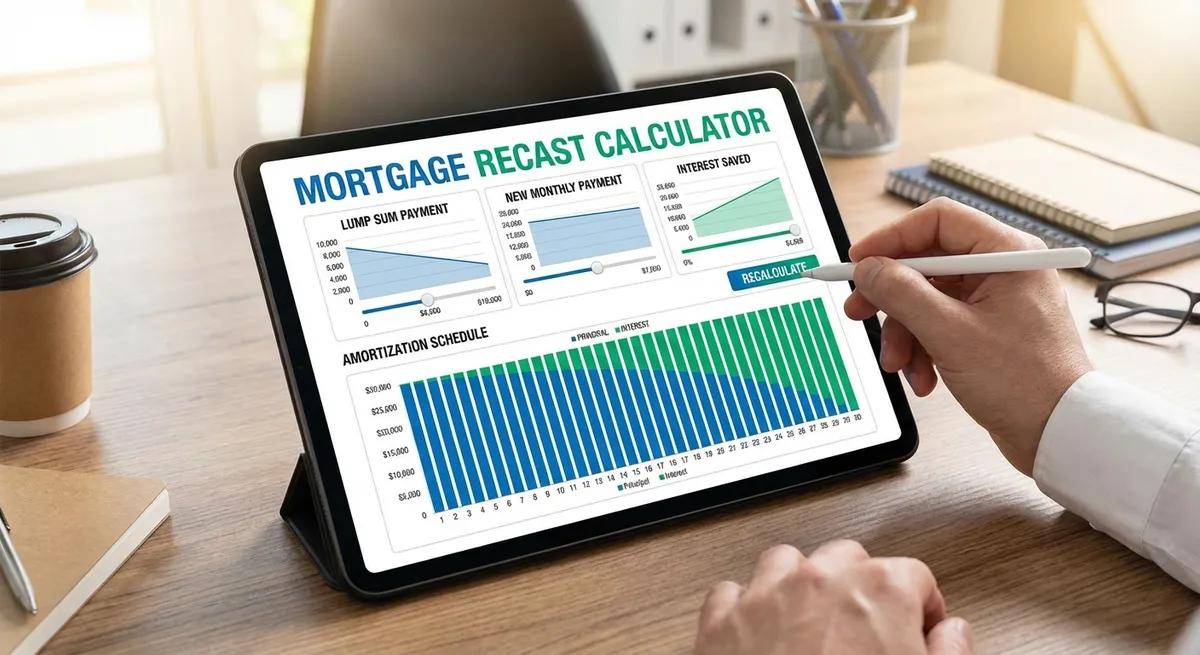
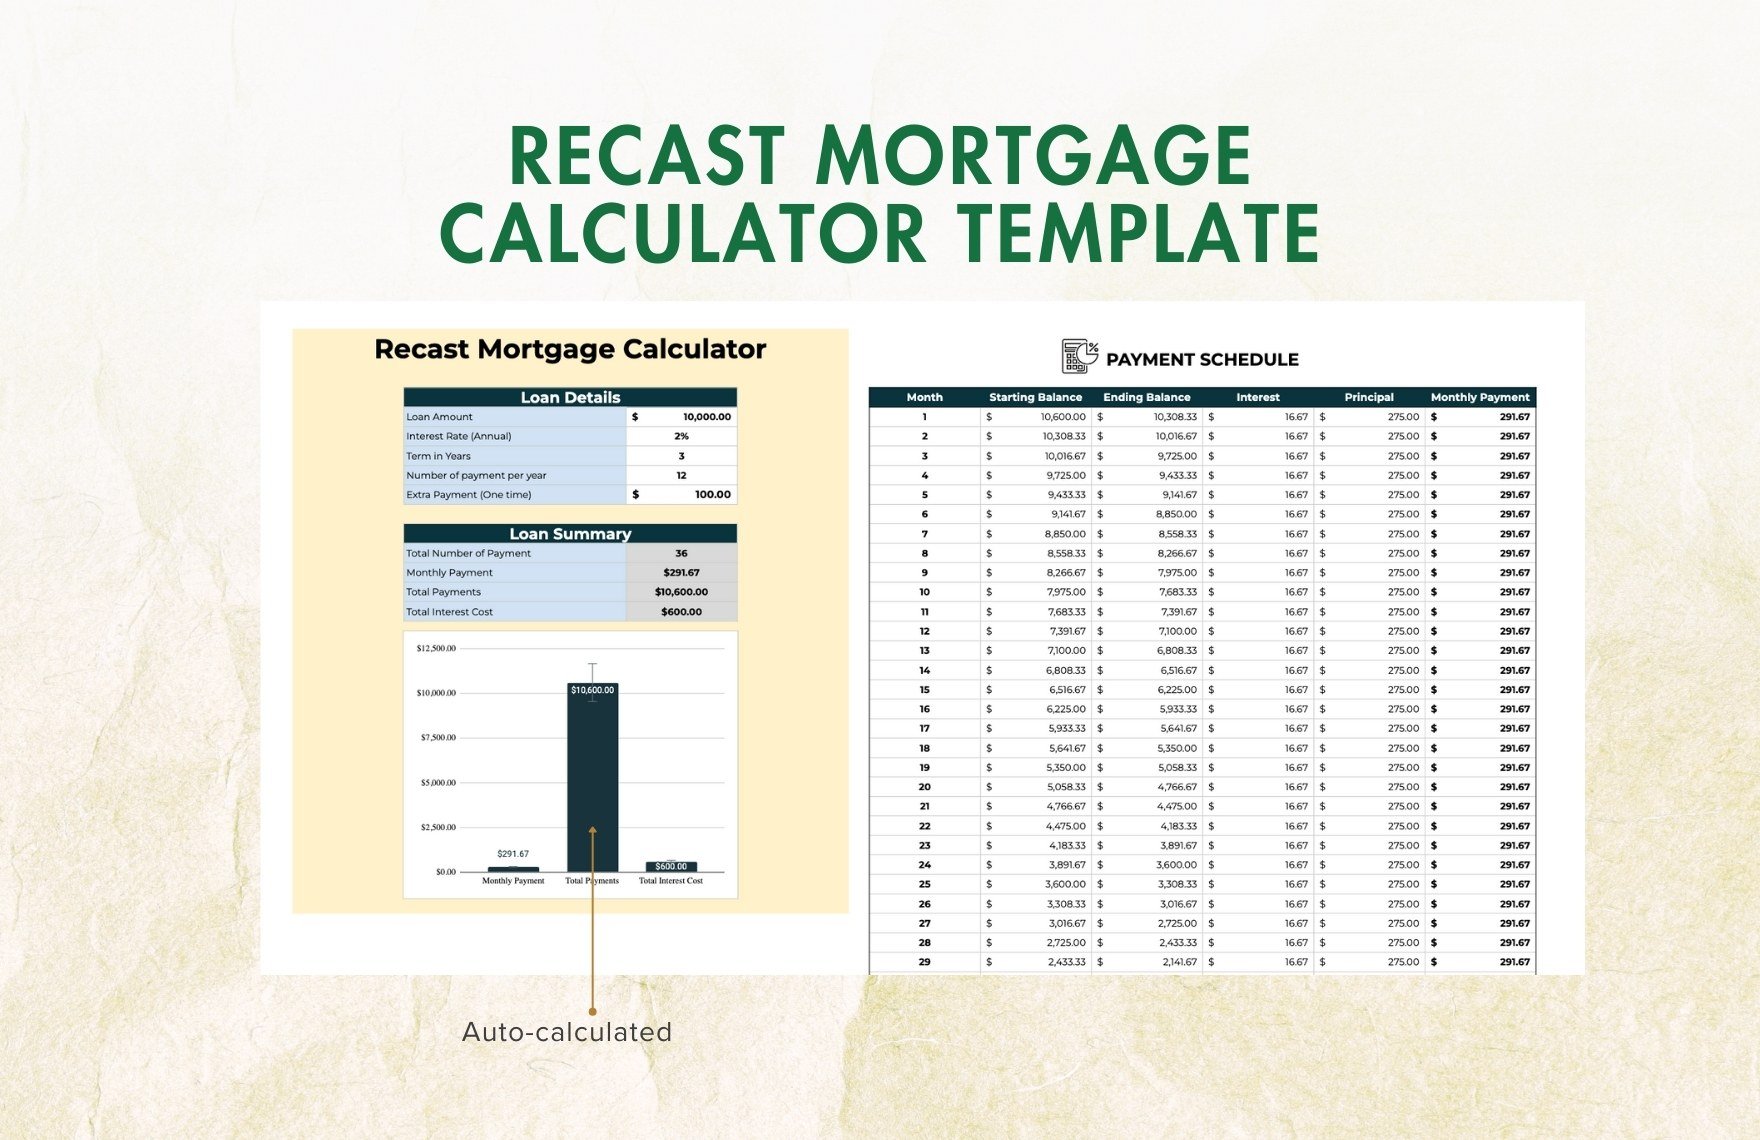
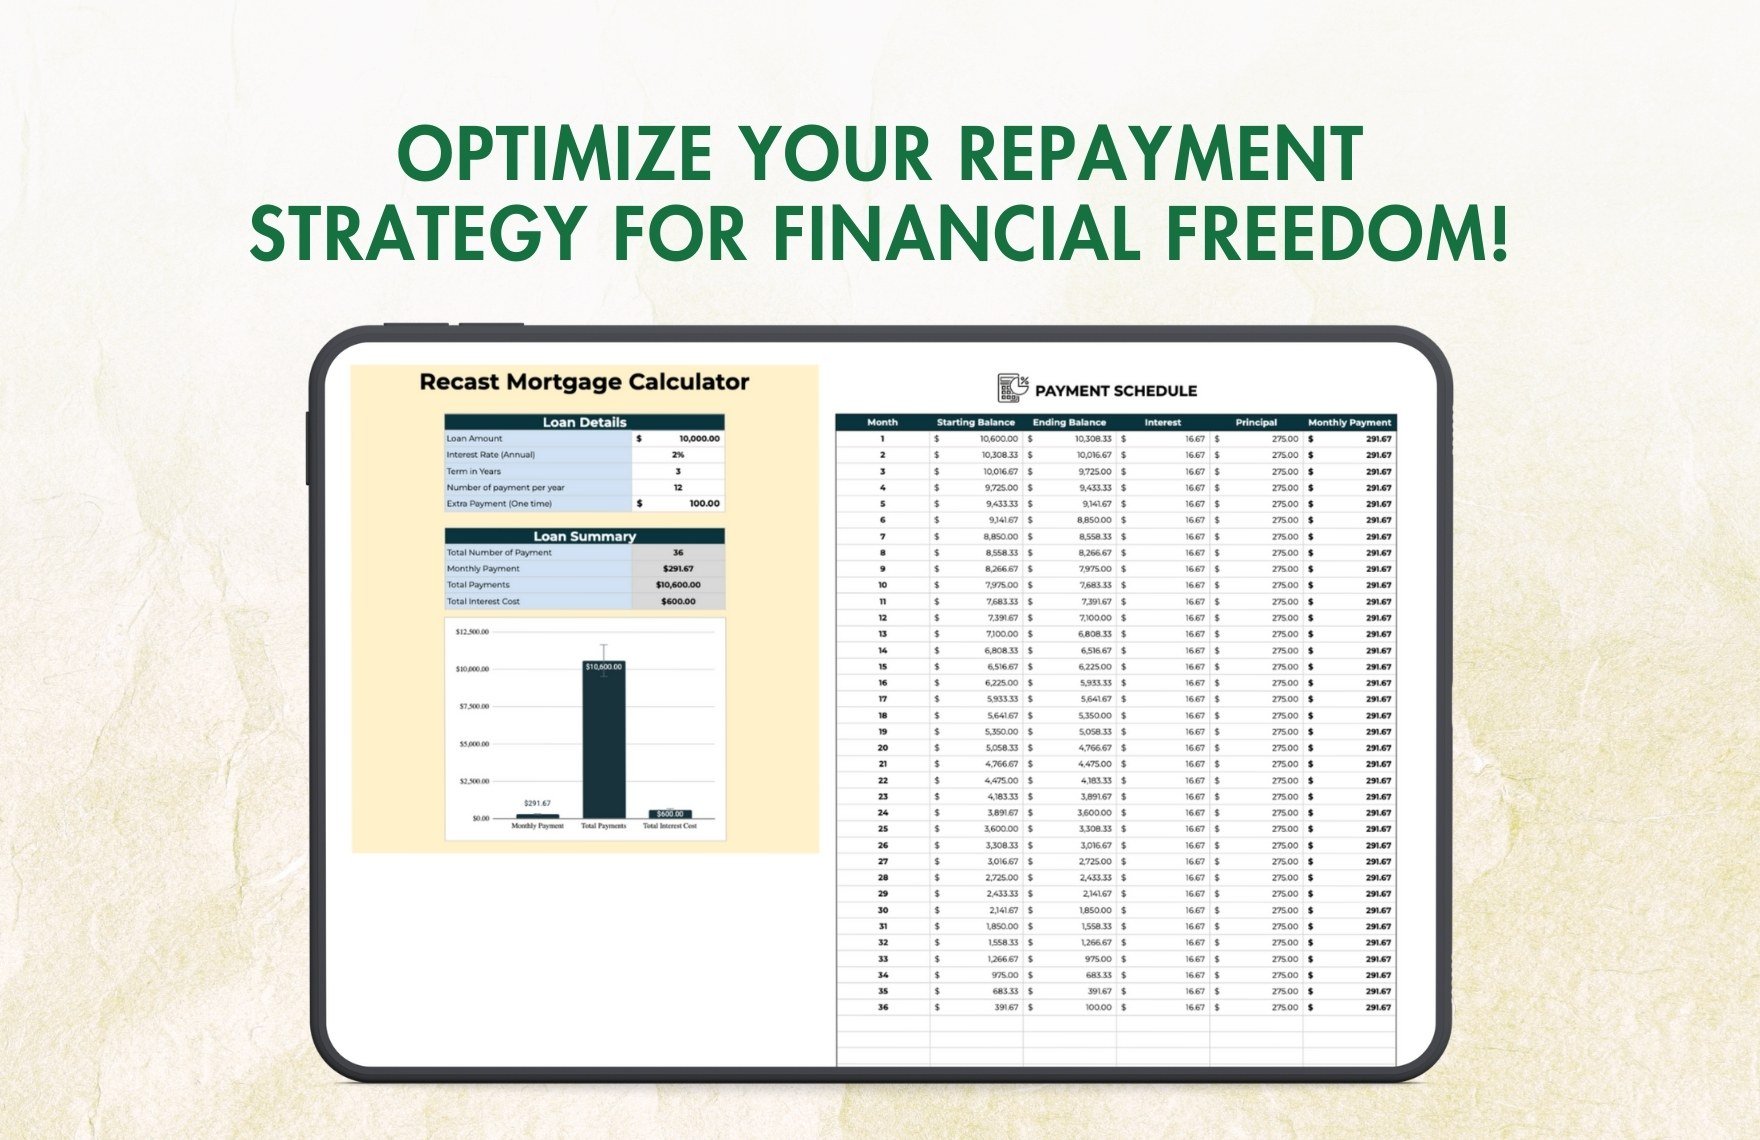
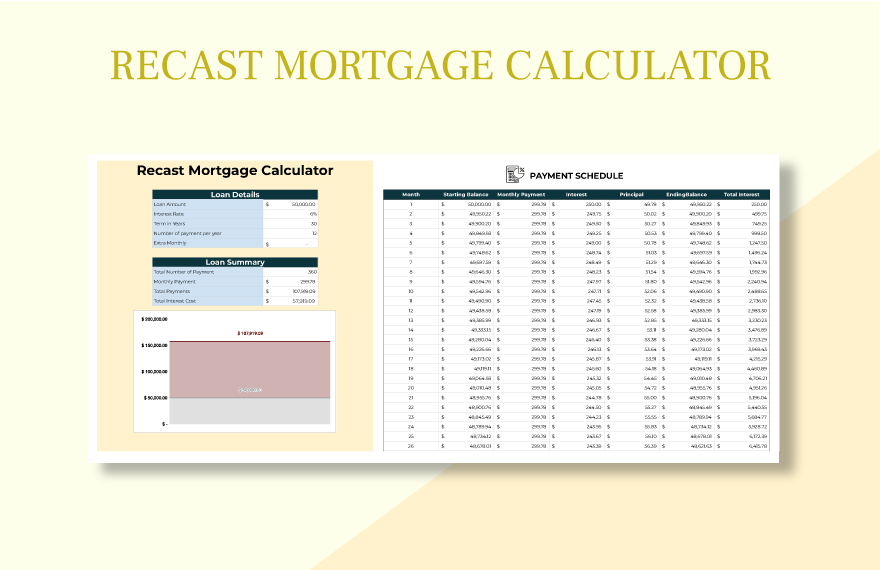
You need a calculator that does more than divide your extra payment by the remaining balance. The actual formula is a full amortization recalculation: take your current principal, subtract the lump sum, keep the original interest rate and original maturity date, and recompute the monthly payment. A proper tool shows you the before and after numbers side by side. It also shows how much interest you save over the life of the loan.Here is the calculator I use when I need a quick answer without opening Excel. It handles the standard cases and flags when something looks off. I keep a simplified version in this file: Download: recast_mortgage_calculator_v2.xlsx
It is a straightforward spreadsheet. No macros. No subscription. Just fill in your numbers and it does the math. If your loan has prepayment penalties, escrow adjustments, or a balloon payment built in, you will need to adjust the columns manually or contact your servicer directly. The spreadsheet does not handle those edge cases automatically.
How to Actually Recast Your Mortgage
You do not apply for a recast the way you apply for a refinance. Most lenders require you to submit a written request. Some allow it through an online portal. Others require a printed form mailed to the servicing department. The process typically takes two to four weeks from submission to the new payment statement.The steps are straightforward:
Get the Full Details
- Call your servicer and ask if they offer recasts and what their fee is
- Ask for the minimum lump-sum requirement. Many lenders require at least 5,000 dollars or 10 percent of the current balance, whichever is greater
- Submit your recast request in writing with the payment amount
- Send the lump-sum payment. Do not send it until the servicer confirms receipt of your request, or you may end up just reducing principal with no reamortization
- Wait for the new payment breakdown. Your next statement should show the recalculated monthly amount
When a Recast Makes Financial Sense
A recast works best when you have a chunk of cash sitting idle and your current rate is below what refinancing would offer. Say you owe 320,000 dollars at 3.5 percent with 25 years remaining. You have 50,000 dollars available. A recast drops your payment from roughly 1,515 dollars per month to about 1,280 dollars. You save roughly 235 dollars a month and around 42,000 dollars in total interest over the life of the loan. The fee is usually under 1,000 dollars. The math is clean. It stops being attractive when your rate is above 6 percent and rates have dropped since you locked in. At that point, a refinance might lower your payment more than a recast ever could, even after closing costs. Run both scenarios through a calculator before deciding. Also consider whether the 50,000 dollars might earn more in a high-yield savings account or short-term bond ladder than the interest you are saving on the mortgage. If your mortgage rate is 3.25 percent and you can get 4.5 percent risk-free elsewhere, the recast saves you less than the alternative investment earns.Another scenario where a recast fails entirely: loans with prepayment penalties. Some contracts charge a percentage of the outstanding balance if you pay down principal beyond a certain threshold within the first five to seven years. A 50,000 dollar recast on a loan with a 2 percent prepayment penalty inside its penalty window would cost you an additional 1,000 dollars. Check your loan documents for a prepayment clause before you do anything.