The Monthly Tax Bill That Makes You Question Your Life Choices
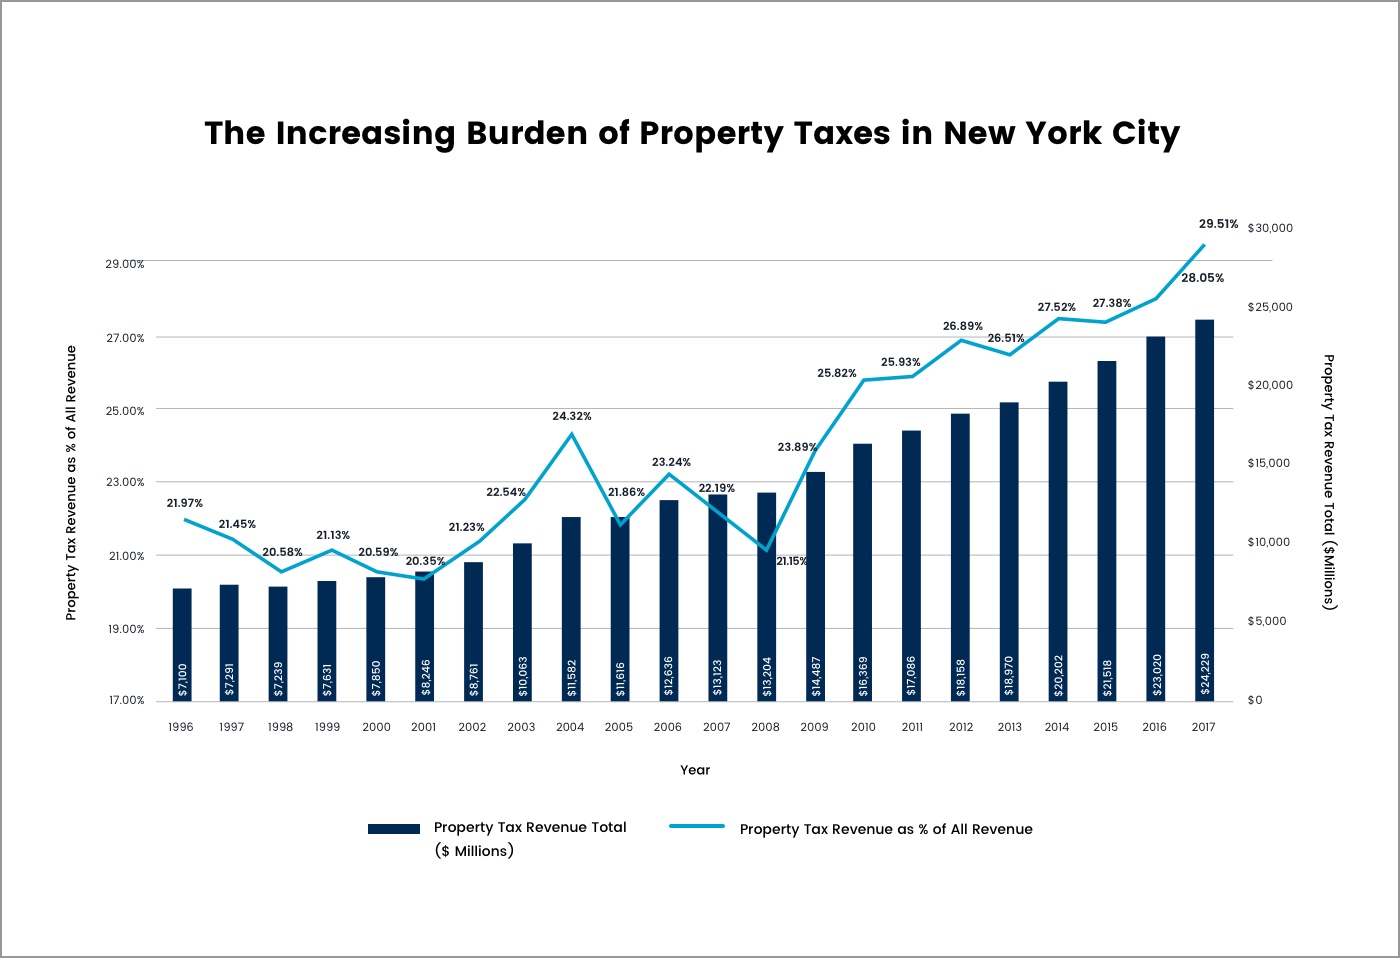
Your NYC property tax bill arrives once a year, but it's really twelve separate anxieties stacked into one envelope. Most people walking into their first co-op or condo sale have no idea what they're signing up for. They see the square footage and the view of the river and think about whether the kitchen has enough cabinet space. They don't calculate the tax impact because nobody sits them down and does the math before the closing table. I closed on a studio in Manhattan three years ago and found out three months later that my common charges included a line item called "tax increment" that was $840 a month. That's not the property tax. That's the building's property tax divided among all units, pass-through style. On top of that, my actual tax bill from the city came to another $2,100 once a year. So the real number was closer to $12,000 annually just in taxes, not including mortgage insurance or the rent stabilization gaps that appear in older buildings. The listing price never mentioned any of this.
Real Estate Taxes NYC The Untold Cost Of Owning Property In Americas Priciest Market
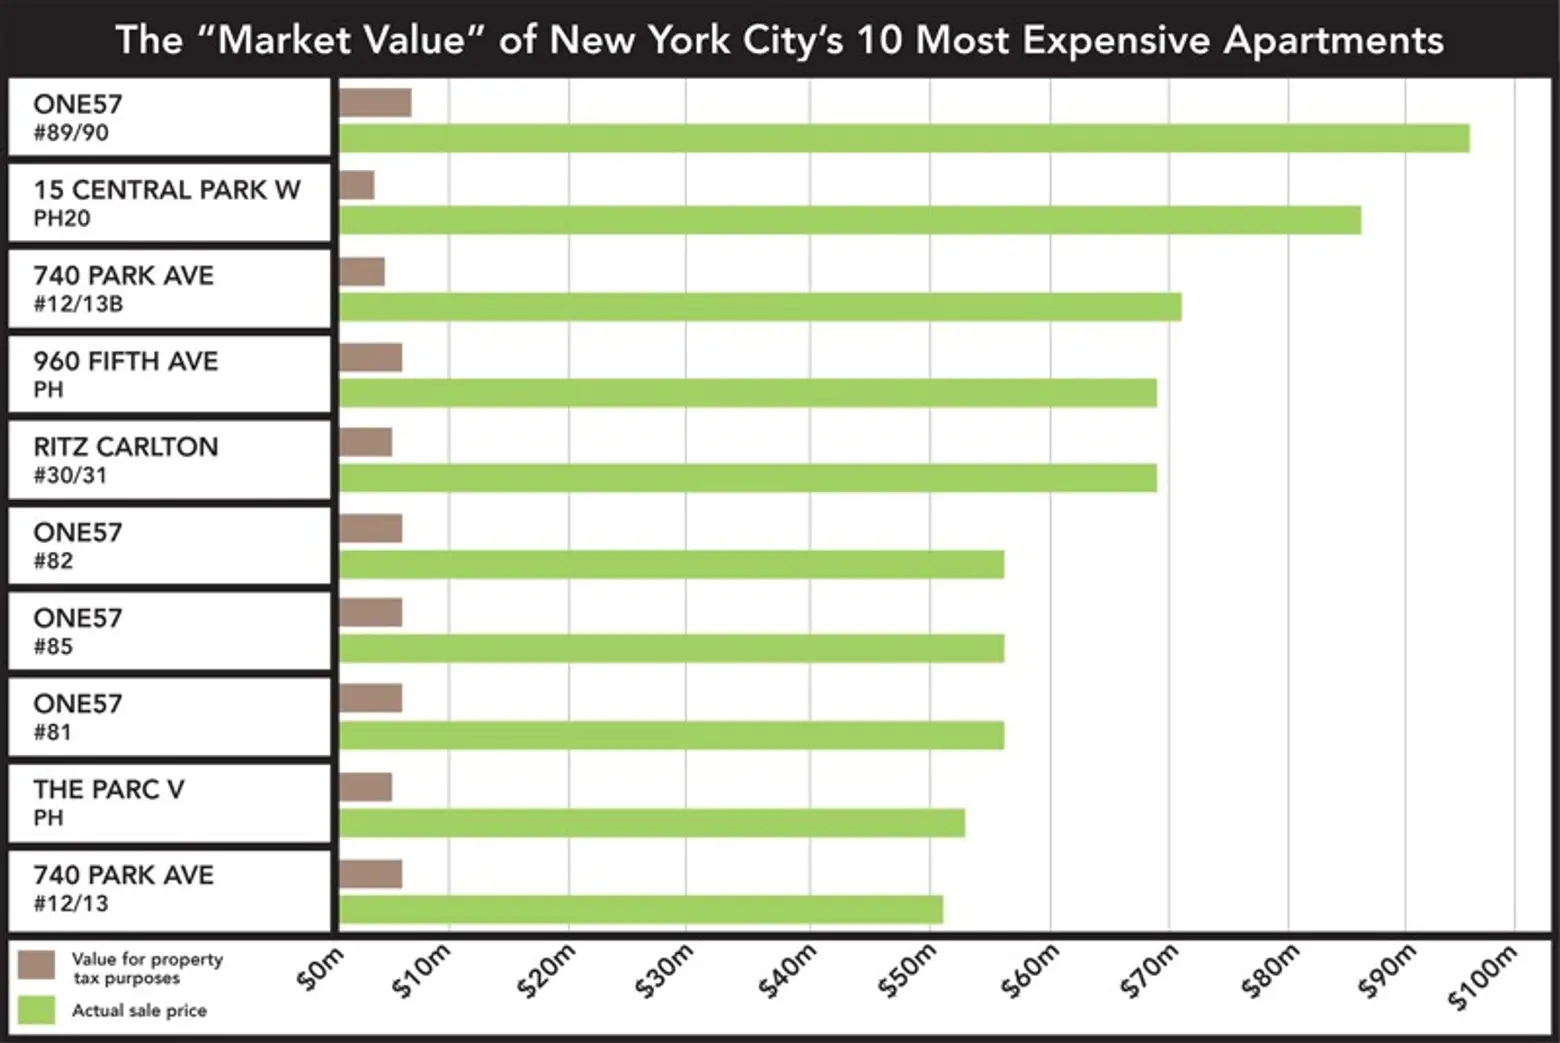
Class A vs. Class B vs. Class C: the classification system most buyers ignore NYC assesses properties into different classes and each one gets taxed at a completely different effective rate. Residential co-ops and condos are Class 2 properties. That means the assessed value is a fraction of market value — roughly 6% to 22% depending on the borough and the building's income history. The tax rate then gets applied to that assessed value, not the purchase price. So a $1.2 million condo in Queens might have a tax bill that looks deceptively low compared to a $400,000 townhouse in Brooklyn, simply because the assessment ratios and zoning classifications differ. The problem is that assessment values don't update every year. NYC does a revaluation cycle every few years, and when it hits your building, your tax bill can jump 30% to 60% overnight. I knew a buyer in 2019 who purchased a condo in Astoria with a $4,200 annual tax bill. Two years later, during the reassessment window, it went to $7,800. The monthly common charge adjusted accordingly. There was no warning period where you could back out of the purchase. The seller had already moved on and the buyer was stuck.
Maintenance pass-throughs are where the actual cost hides In a co-op, you don't pay property tax directly to the city. The cooperative corporation pays it as one big bill, then allocates a share to each shareholder based on their percentage interest in the building. This is reported on your Form 1098, and yes, you can deduct it on your federal return. The catch is that the allocation formula inside your co-op's bylaws might not match the actual tax burden per square foot. Some buildings allocate based on square footage. Others use a fixed percentage per unit regardless of size. A few use a hybrid that rewards smaller units disproportionately. I spent two weeks last year going through the offering plan of a Midtown West co-op and realized the smallest units — the studios — were being allocated 14% of the total tax bill despite being only 8% of the building's total square footage. The bigger units were subsidizing them slightly, which is why the owners of those larger apartments always complain about the allocation. It's a structural issue baked into the building's original prospectus. The apartment type tax exemption and its narrow escape route
Get the Full Details
NYC offers an Apartment House Tax Exemption for newer residential buildings, commonly called the 421-a program or its successor, the J51 exemption. Buildings constructed or substantially renovated under these programs receive a phased reduction in property taxes over 10 to 45 years, depending on the income level of the units and the zone. When the exemption expires, the tax bill resets to full value. This is the single biggest source of uncertainty in NYC property ownership. I worked with a client in 2022 who was considering a condo in the Bronx. The listing showed a tax bill of $3,400 annually. That looked reasonable. We pulled the DOB construction record and the HPD tax exemption file and discovered the building was still in year 8 of a 45-year exemption phaseout. At year 10, the bill would double. At year 20, it would triple. By year 45, it would hit the full assessed value rate. The seller knew this. The listing agent did not disclose it in the offering plan summary. The buyer found out during the due diligence period and walked away. It happens constantly and nobody talks about it because the current low number looks good on paper until you read the fine print. Tax abatement wind-down schedules vary by borough and sometimes by street
Not every building in the same zip code exits its abatement at the same time. NYC does this on a parcel-by-parcel basis. Two buildings on the same block in Long Island City can have completely different phaseout schedules. One might lose its exemption next year while the neighbor across the street still has twelve years remaining. This creates unpredictable common charge spikes that rip through entire buildings unevenly. You can pull the tax lot information from the ACRIS system — the Automated City Register Information System — and look up the specific abatement status for each parcel. It takes about twenty minutes per building if you know what you're looking for. Most buyers never do this.
How to Calculate Your Actual Annual Tax Burden Before Buying
Step one: pull the property tax card from BIN or BBL Every parcel in NYC has a Borough-Block-Lot number, or a Building Identification Number if you want the physical structure record. You can look these up free on the ACRIS portal or the Department of Finance GIS map. The tax card shows the assessed value, the current tax class, the exemption status, and the tax rate applied. It also lists the previous year's tax payment. Cross-reference the assessment with the sale price. If the assessed value is 5% of the purchase price, you're looking at a Class 2 residential rate. If it's higher, something is misclassified or there's a commercial component mixed in. Step two: find the exemption expiration date

Search the HPD tax exemption database using the BBL. It will tell you the program type, the start date, the end date, and the annual benefit amount. If the database shows no record, the building is on the full tax roll. If it shows an end date five years from now, budget for the step-up. HPD publishes the phaseout schedule, so you can calculate the exact dollar increase each year. Do this before you make an offer. I've seen people write LOIs on buildings with two years of exemptions left, fully expecting to stay in the unit for a decade, and then get blindsided by a $4,000 annual increase they couldn't absorb. Step three: request the last three years of common charge histories The seller or the managing agent must provide these during the condo or co-op board application process. Look at the trend line. Are common charges climbing at 3% annually or 12%? A building that jumped common charges 18% in a single year almost always has a tax exemption expiring or a special assessment tied to a capital project. Check the board meeting minutes if you can get them. The mention of "tax escrow deficiency" or "DOF reassessment notification" in a three-line agenda item is the red flag you need to act on immediately.
Step four: run the numbers through a simple spreadsheet Input the current tax bill, the exemption end date, the projected annual increase, and your expected holding period. Compare that to the net operating income if you're buying a rental. For an owner-occupied unit, compare the total annual housing cost against your after-tax income and your current rent. If the tax-inclusive cost exceeds 40% of your gross monthly income, you're overextended by standard lending ratios. This is a blunt threshold but it catches most buyers who are focused on the purchase price and ignoring the carrying cost.
Edge Cases That Cost People Money
The partial exemption trap in mixed-use buildings If your building has retail space on the ground floor, the residential portion and the commercial portion are assessed separately. The commercial assessment usually carries a higher effective tax rate. When the residential exemption phasing out, the commercial side doesn't get any relief, and the building's overall tax burden shifts. Some co-ops handle this by adjusting the allocation formula every few years. Others don't, and the residential shareholders absorb the commercial tax increase implicitly. I encountered this in a Harlem co-op where the ground floor retail lease expired and the new tenant renovated the space into a full restaurant. The commercial assessment jumped 40%, and the board increased the residential tax allocation by $120 per month per shareholder without a formal vote. It was buried in the quarterly financial statement footnotes. The shareholders who noticed it were the ones who fought back. Most never saw it. The brownstone differential assessment myth
Many buyers assume brownstones in historic districts get a tax break because of their designation. That's not true. The landmark commission has no authority over property tax assessment. In fact, historic district status can make improvements more expensive, which increases the assessed value of the building when renovations trigger a reassessment. A brownstone in Cobble Hill that gets a new roof, updated plumbing, and a finished basement will see its assessed value rise significantly. The tax bill follows. The historic designation itself does nothing to lower the tax. I advised a buyer in 2021 who thought the landmark status was a protective factor. It wasn't. It was the opposite. The renovation costs alone pushed the assessment up by $18,000, translating to an extra $720 in annual taxes. Property tax litigation is rare but devastating when it happens If your building's assessed value is incorrect, the co-op corporation or condo board can appeal to the Office of Real Property Services (ORPS). This is a formal process that requires appraisals, comparable sales data, and a hearing before a panel. It takes six to eighteen months. I was involved in a case in Queens where a mid-size co-op appealed its assessment and saved $220,000 annually across the building. That's about $800 per shareholder per year. But the process cost $45,000 in legal and appraisal fees upfront, and the board had to vote unanimously to pursue it. Two shareholders blocked the vote because they were worried the appeal would trigger a full reassessment that could increase their individual shares. The building lost $220,000 in savings over three years because of one person's fear. These internal politics are as important as the math.
Seller disclosures are unreliable in NYC New York State requires sellers to fill out a property condition disclosure form, but it doesn't ask about future tax increases or exemption phaseouts. The standard buyer's attorney will request the last three years of tax bills and the offering plan, but many skip the ORPS exemption lookup entirely. I've seen this happen repeatedly. The buyer's lawyer is overworked, the deal is moving fast, and the exemption detail gets overlooked. By the time the buyer discovers the tax step-up, they're already closing. The remedy is to make your contract contingent on reviewing the tax exemption status and the board's capital plan. It adds ten days to the process and costs nothing extra. It also prevents the most expensive surprises.
What the Numbers Actually Look Like Across the Boroughs
A one-bedroom condo in Manhattan proper typically carries $6,000 to $14,000 in annual property tax, depending on the building age and exemption status. The same unit in Brooklyn, usually $4,000 to $9,000. Queens sits in the middle at $3,500 to $8,000. The Bronx and Staten Island tend to be lower, $2,500 to $6,000, but the assessment ratios can be less transparent and the abatement programs less frequently tracked by buyers. The variation within each borough is larger than the variation between boroughs. A prewar co-op in Upper West Side Manhattan might pay $8,000 in taxes while a brand new condo in nearby Hell's Kitchen pays $18,000, not because the building is more valuable, but because the newer building lacks any exemption and the older one still has ten years of phaseout remaining. The tax deduction advantage is real but shrinking Itemizing property tax deductions on your federal return can save you significant money, but the SALT cap limits state and local tax deductions to $10,000 combined. For high earners in expensive buildings, this cap bites hard. You can deduct property taxes, but not the portion of common charges that covers everything else. The $10,000 limit means if your property tax alone is $12,000, you only get $10,000 of it. The remaining $2,000 is lost. This is one of the reasons wealthy buyers in NYC have started pushing for changes to the cap, and it's one of the reasons the tax burden feels heavier than the headline number suggests. New York State also offers a rent relief program for renters, but owners don't get anything similar. The policy gap is real and it affects everyone above the cap threshold.

The only reliable way to understand what you're actually paying is to look at the three most recent tax bills, the exemption expiration date, and the board's approved budget. Those three documents together will tell you more than any listing or marketing sheet ever will. Everything else is noise.