QuickBooks Was Built for Businesses, Not Your Household Budget
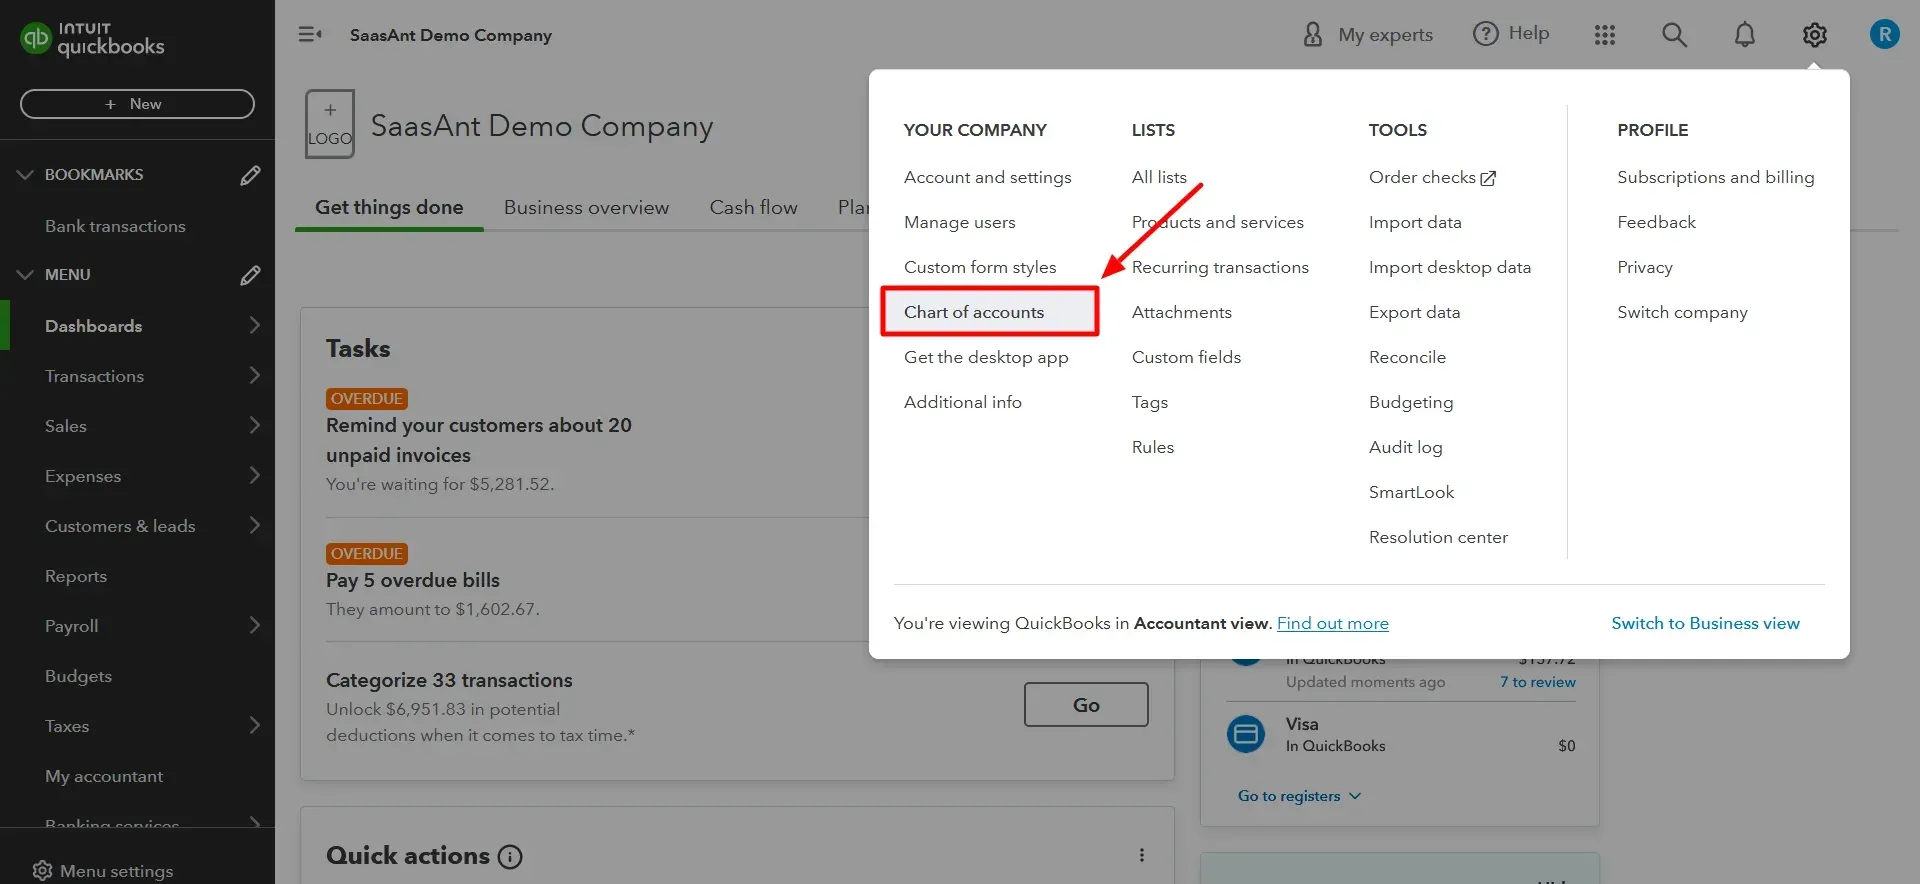
I've spent years watching people try to squeeze their personal finances into QuickBooks. The tool works, technically. That doesn't mean it fits. I set up QuickBooks Self-Employed for my own rental property income back in 2019 and ran it that way for about fourteen months before ripping it out. Here's what actually happened during that time. The core issue is that QuickBooks is a double-entry accounting system wrapped in a single-user interface designed for small business owners who need to track profit and loss. When you use it for personal finance, you're fighting the software's DNA constantly. Most people don't realize this until they've already entered three months of data and hit a wall. The main workflow looks like this. You connect your bank accounts through Plaid or Direct Connect. Transactions populate automatically. You then categorize each transaction to an account in the Chart of Accounts. QuickBooks calculates your net profit or loss based on how you've mapped everything. That part is fine. The friction starts when your personal financial life doesn't map cleanly onto a business P&L structure.
I learned this the hard way when I tried to track my household expenses alongside my rental income in the same file. QuickBooks forces you into either a sole proprietorship structure or a multi-entity setup. I went with the sole proprietor route and assigned my rental income to a separate income account and my personal spending to expense accounts. The problem came when I wanted to see my total net worth across all accounts. QuickBooks doesn't give you that. It gives you a Profit & Loss report and a Balance Sheet. The Balance Sheet shows bank accounts, but it doesn't aggregate them the way a personal finance tool does. I ended up building a custom report using the Custom List feature just to get a combined total of checking, savings, and money market accounts. It took me about forty minutes to set up and another twenty minutes every month to refresh.
How People Actually Set It Up
The standard approach most users fall into starts with QuickBooks Self-Employed or QuickBooks Online Simple Start. Both are available at intuits.com. Self-Employed runs about ten dollars a month on the basic tier. Online Simple Start is roughly the same price point. You sign up, link your accounts, and start categorizing. What people miss is that QuickBooks has a "Categories" system that's different from its Chart of Accounts. The categories appear on transactions and are meant for quick tagging. The Chart of Accounts is the underlying accounting structure. When you categorize a grocery store charge as "Meals and Entertainment," QuickBooks routes that to the Meals and Entertainment expense account on your P&L. That's by design for a business. For personal use, you might prefer to tag that same transaction as "Groceries" under a different mapping. You can create custom categories in QuickBooks, but they still map to Chart of Accounts accounts underneath. You can't decouple the two entirely without jumping through vendor add-ons or building custom classes. Here's a practical workflow that actually works. Create a separate equity account called "Owner Contributions" and another called "Owner Withdrawals." Every month, when you transfer money between your personal checking and any business or investment accounts, record it as a transfer between the Owner Contributions and Owner Withdrawals accounts. This keeps your P&L clean and prevents your net income from being distorted by internal transfers. I used to manually enter these every month. Then I discovered QuickBooks' recurring transaction feature. I set up a template that copies itself on the first of each month and just adjust the amount. Saved me about twelve minutes per month, which sounds like nothing until you multiply it across a year.
Get the Full Details
Where the Tool Actually Breaks Down
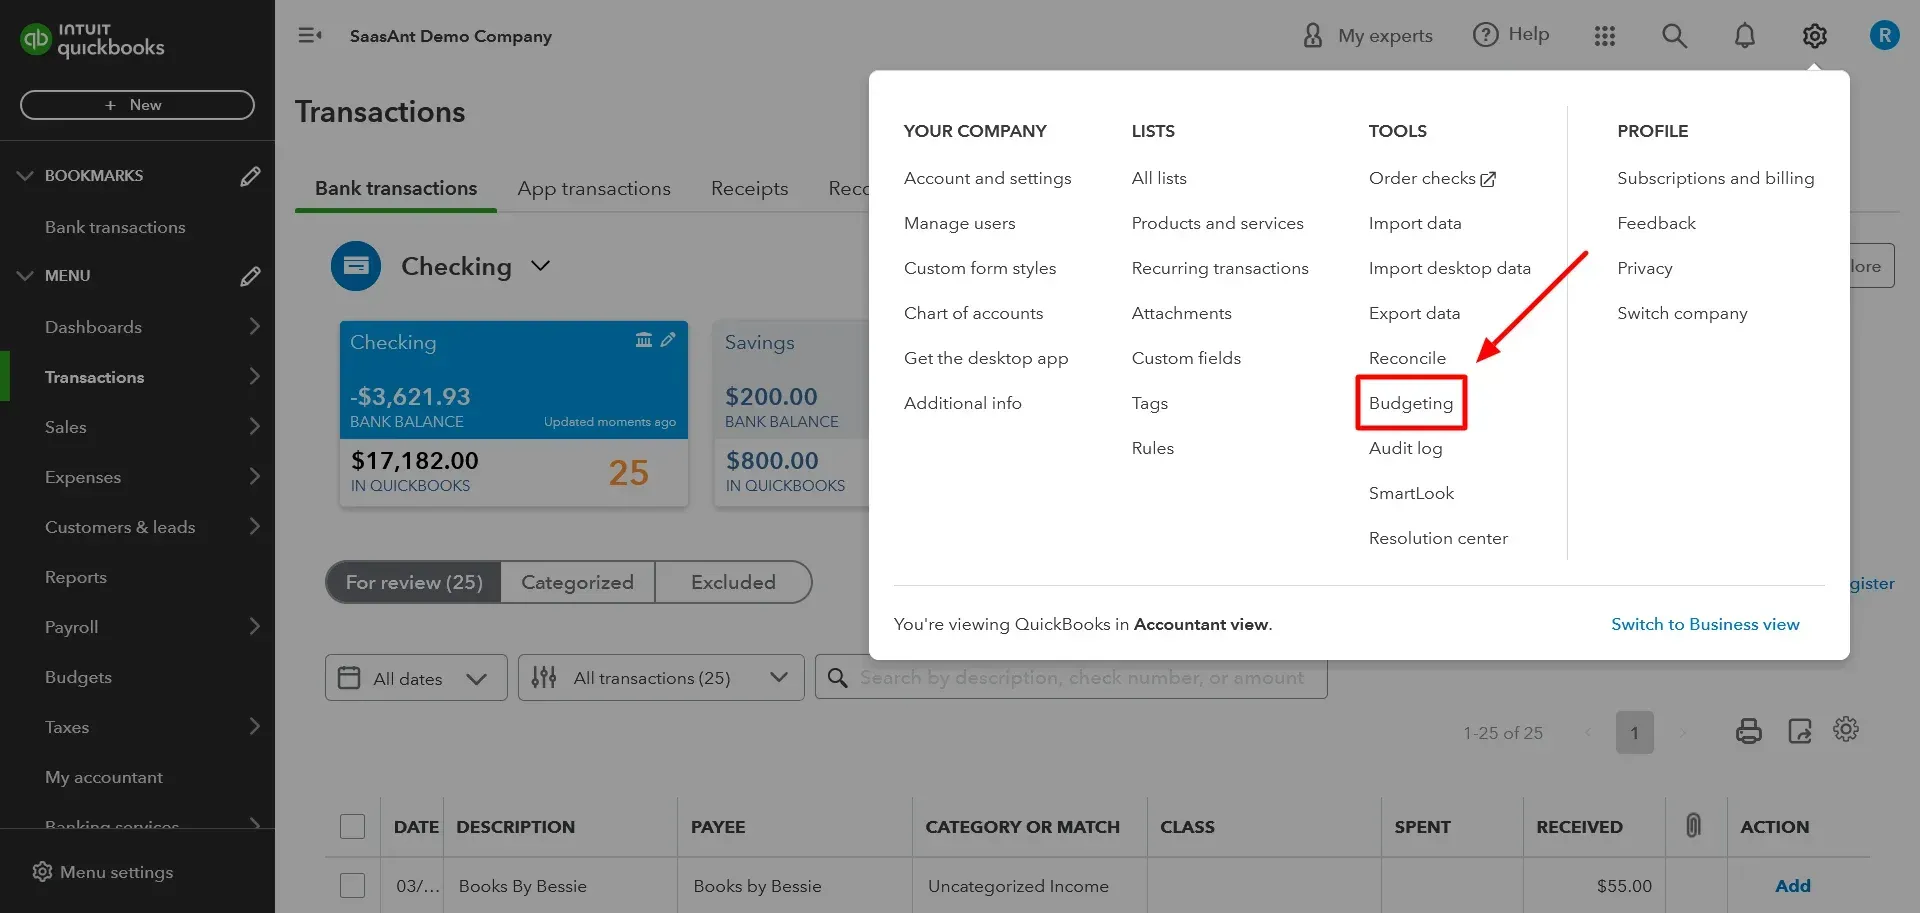
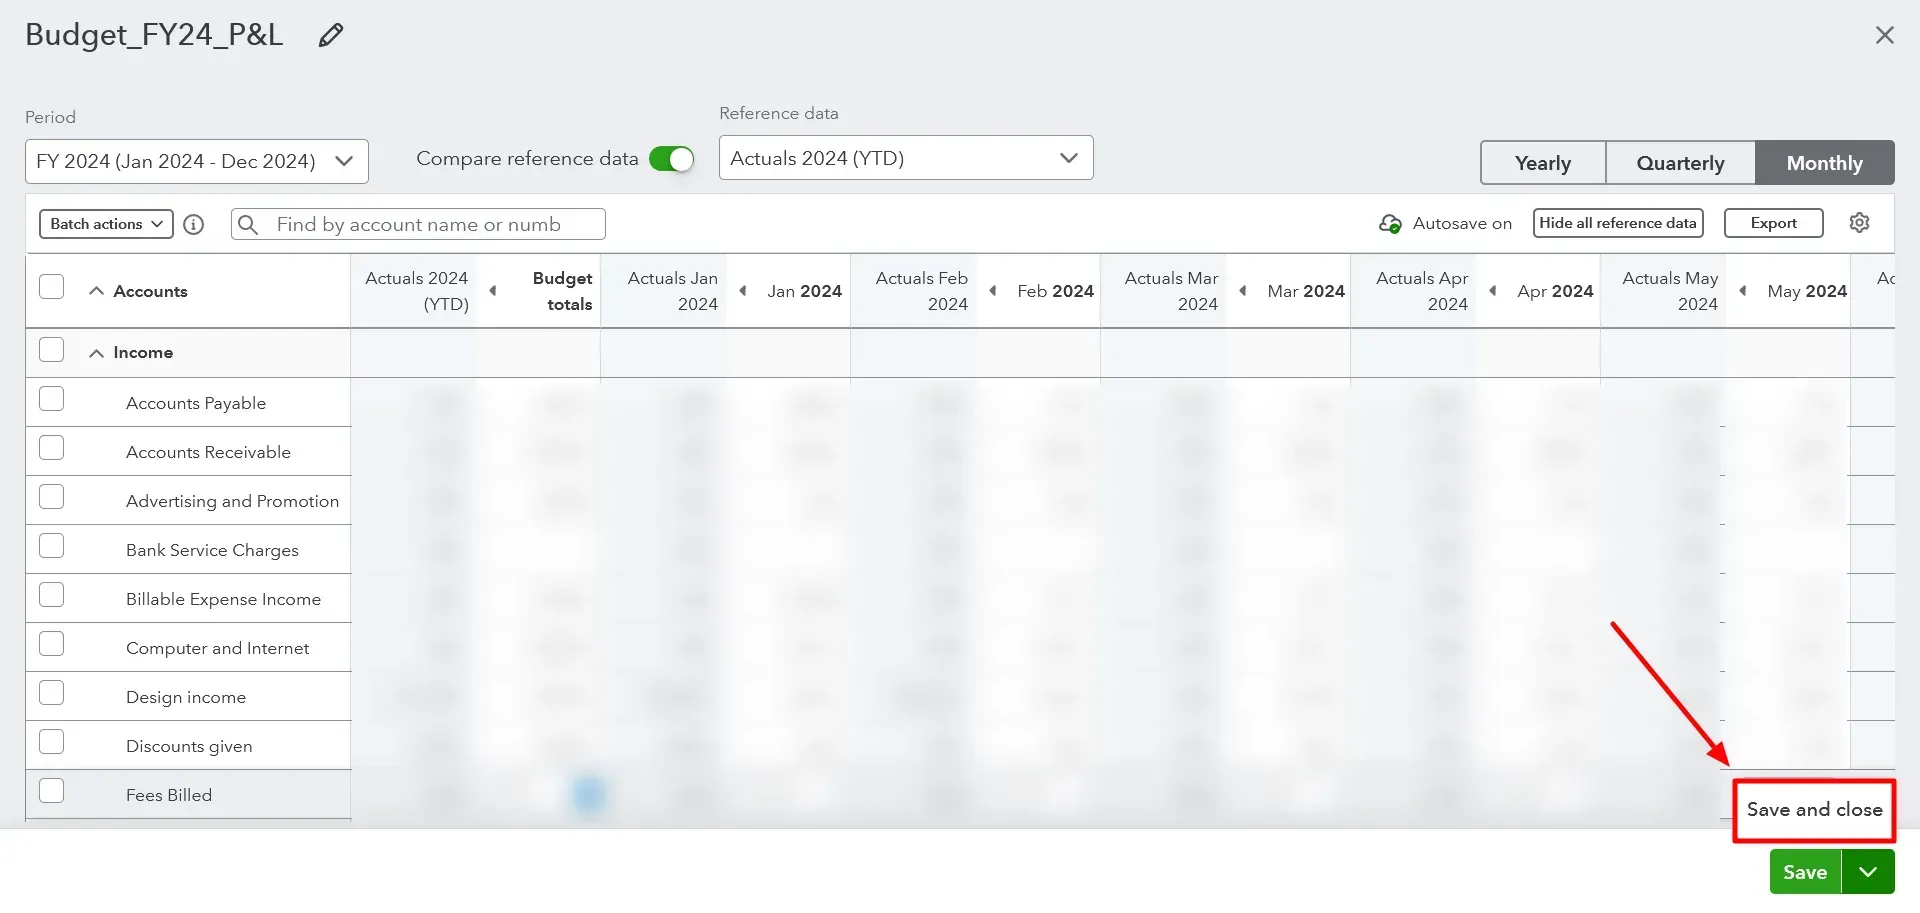
The biggest problem with QuickBooks for personal use is budgeting. QuickBooks has no native budgeting feature in the lower tiers. You can add budgets in the Plus tier and above, but even then the functionality is primitive. You set monthly or quarterly budgets by account. There's no rolling budget. There's no envelope method. There's no visualization of spending against a target within a month. If you want that level of control, you're better off using Mint, YNAB, or even a spreadsheet. I switched to YNAB after my QuickBooks experiment and the difference was immediate. YNAB's zero-based budgeting system forces you to assign every dollar a job. QuickBooks simply records what happened. One is predictive. The other is retrospective. For personal finance, predictive matters more. Another blind spot is debt tracking. QuickBooks doesn't have a built-in loan amortization schedule. If you have a mortgage, car loan, or student loans, you can record the payments as expenses, but you won't see your remaining balance decrease in any organized way unless you manually adjust the liability account each month. I kept a separate spreadsheet for my mortgage balance and updated it quarterly while QuickBooks handled everything else. That's two systems instead of one. Which defeats the purpose of consolidating your finances. Here's something most guides won't tell you: QuickBooks treats credit card payments as transfers between your credit card liability account and your checking account. That's correct from an accounting standpoint. But when you review your cash flow, it looks like money disappeared. The payment doesn't show as spending. It shows as a liability reduction. This confuses a lot of personal finance users because they expect their credit card payments to appear as expenses on a spending report. They don't. The actual purchases are the expenses. The payment is just moving money around. I spent about three weeks thinking I was misreading my cash flow until someone pointed this out on a forum. The fix is to run the "Expenses by Vendor" report instead of the Cash Flow report when you want to see where your money went.
When It Actually Makes Sense
QuickBooks works for personal finance if you're a freelancer or independent contractor with significant business income mixed into your personal accounts. The tax deduction tracking alone justifies the switch. I kept meticulous records of mileage, home office expenses, and equipment purchases because QuickBooks had those features built in. If you claim Schedule C deductions, the time saved on tax preparation more than pays for the subscription. The IRS match feature in Self-Employed pulls your 1099s automatically. That alone saves roughly two hours during tax season. It also makes sense if you already own a business and want everything in one place. Running separate QuickBooks files for your business and your personal finances means logging into two systems, reconciling across two sets of accounts, and maintaining duplicate data. Consolidating everything into one file eliminates that overhead. Just keep your business and personal transactions clearly separated using classes or locations. QuickBooks Online allows location tracking in the Plus tier and above. I used location tracking to separate my rental property activity from my day job income in the same file. The reports filtered cleanly by location without any custom scripting.
The Honest Verdict
QuickBooks for personal finance is a tools-not-a-solution situation. It handles transaction recording well. It generates accurate financial reports. The bank feeds are reliable. Where it fails is in personal finance specific workflows like budgeting, debt payoff tracking, net worth aggregation, and spending visualization. If your primary need is tracking what comes in and goes out and generating tax-ready reports, it works fine. If you want a tool that helps you plan and control your spending, you'll spend more time fighting the interface than gaining insight. I'd recommend trying the thirty-day free trial before committing. Set up your accounts exactly how you think you'd use them. Enter a month of real transactions. See whether the reporting matches what you actually need to see. If you find yourself constantly working around the software instead of using it, that's your answer. The market has better options for purely personal finance use. QuickBooks is just not one of them in most cases.