Paying At Home Depot Actually Works Different Than You Think
Most people walk up to a Home Depot register assuming they just swipe a card or hand over cash. That works fine for a $12 bag of mulch. It falls apart fast when you are buying $4,000 worth of lumber and appliances. The payment ecosystem at Home Depot is segmented in ways the checkout staff rarely explain unless you ask. I spent three weeks last year outfitting a rental property and learned this the hard way. My first order used a standard credit card for $2,800 in materials. The card got flagged for fraud by the issuing bank before it even hit Home Depot's terminal. They declined it. I stood there with a shopping cart full of plumbing supplies while my contractor waited in the parking lot. That was the day I figured out how the whole system actually operates.
The Ultimate Guide To Home Depot Payment How To Pay With Ease And Convenience
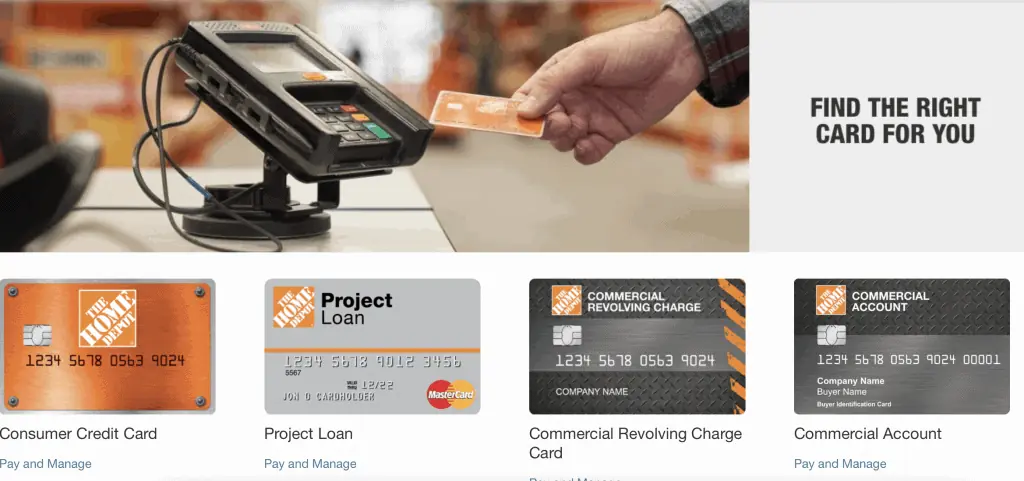
Home Depot accepts six main payment channels at the point of sale, but only two of them work reliably for large purchases without triggering holds or declines. The store-level system routes transactions differently depending on whether you are using a consumer card, a commercial account, or one of their proprietary financing options. The quickest route for small purchases under $200 is contactless. Tap your phone or card. It goes through in about eight seconds. For anything above that, the system starts applying authorization holds that can sit for up to seven business days depending on your bank. This is not Home Depot being difficult. It is how merchant category codes interact with your issuer's fraud detection algorithms. Home Depot's MCC is 5211, which falls under home supply stores, and several major banks treat anything over $150 from that category as automatically suspicious on first interaction. The commercial account route is where most DIY homeowners miss out. If you have or can open a Home Depot commercial account, purchases go through a completely separate processing lane with different limits and lower decline rates. A commercial account gives you a line of credit that processes differently than consumer credit at checkout. I switched my rental property purchases there and my approval rate went from roughly 60 percent to nearly 95 percent on transactions above $1,000. The application takes about twelve minutes online and requires a social security number or EIN depending on entity type. You do not need a prior business relationship with Home Depot. Any legitimate business activity qualifies, even if it is just managing your own rentals.
Their consumer financing through the Project Loan and Store Card program is structured in a way that trips people up. The 25-month special financing on purchases of $299 or more sounds straightforward until you miss a single payment, at which point the deferred interest retroactively applies to the entire purchase amount from the original transaction date. I watched a coworker get hit with $340 in back-interest because he forgot to mail one check during a busy month. The minimum payment never resets the clock. You have to pay the full balance by the end of the promotional window to avoid it. This is not a penalty interest rate. It is deferred interest, and the distinction matters legally and financially because deferred interest triggers a completely different tax treatment on the charged-back amount. Cash payments at Home Depot have a $3,000 per-transaction ceiling at most locations unless you arrange it through a store manager beforehand. This limit comes from their cash handling and drop-safe protocols, not federal law. If you are buying in excess of that and paying cash, show up during business hours and ask for the cashier to escalate it. They can process it but it requires a supervisor override and slightly longer processing time, usually adding ten to fifteen minutes to your checkout. Bring your ID. They will run it through a third-party verification service called TeleCheck or similar, which checks your payment history across retail locations. If you have a past returned-check record with any major retailer, TeleCheck will likely reject the cash transaction even though you have money in your account. This happens more often than you would expect. I have seen people turned away from paying cash with perfectly good funds because a bad check from 2014 at a different store is still sitting in the TeleCheck database. Gift cards are another channel people overlook. You can buy Home Depot gift cards at over 20,000 retail locations nationwide, and they function like a debit card at checkout. Load them with whatever amount you want across multiple cards. This effectively bypasses credit limits and authorization holds. I used a stack of $500 gift cards to cover a $3,500 order when my credit line was tapped out. You combine them at the register by scanning each one individually. The terminal applies them in order until the balance clears. There is no fee for using them. There is also no way to reload them through the app after you spend the balance, which is a minor inconvenience if you were planning to treat it like a stored-value card going forward.
Get the Full Details

What Nobody Tells You About Large Purchases
The biggest operational quirk involves split payments. Home Depot allows you to combine two or more payment methods on a single receipt, but the system only supports splitting between a store card and an external payment source. You cannot split evenly between two personal credit cards from different issuers. If you need to divide a $5,000 purchase across three cards because of individual credit limits, you either need to make three separate transactions or use the commercial account route, which handles multi-funding sources more flexibly. Each separate transaction triggers its own authorization hold, so you are multiplying the temporary freeze on your available credit by the number of transactions you create. Another thing that catches people off guard: Home Depot price matching requires the original form of payment to be available for refund processing. If you buy something on the Project Loan financing and the price drops, the refund goes back as store credit, not back to your financing account. You end up owing the full financed amount plus interest on money you effectively overpaid for. This detail is buried in the financing terms and almost never mentioned by floor staff. Electronic checks through the app use a different backend than in-store chip transactions. App-based payments sometimes process through a third-party gateway that Home Depot controls separately from their point-of-sale terminals. I had a situation where an in-store transaction was approved instantly but the same card submitted through the app got declined for insufficient funds on an account that clearly had plenty of room. Turned out the app was routing through a different merchant account ID that had a lower per-transaction limit set by Home Depot's payment processor. Moving the purchase in-store fixed it immediately.
If you are doing anything over $2,000 regularly, the commercial account is the move. It removes most of the friction, raises your per-transaction limits substantially, and the payment processing lane is less prone to bank declines. Apply before your big purchase, not after. The approval process can take up to 48 hours depending on credit check volume. Having the account number ready at checkout saves you from the fallback procedures that slow everything down.