The Mechanics Behind Split Payments at Checkout
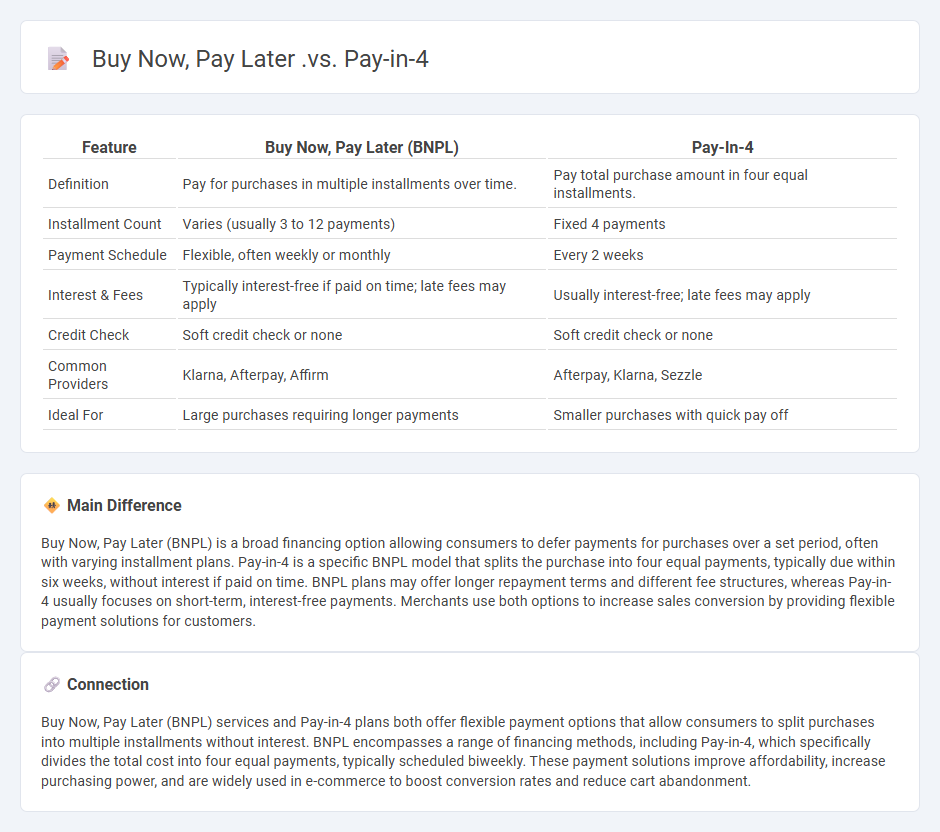
Most merchants don't realize how much friction they're removing when they add a four-installment payment option. The average cart abandonment rate drops by somewhere between 20 and 40 percent once that checkout button shows a smaller upfront charge. You're not just making things easier for customers. You're capturing purchases that would have quietly vanished. The model is straightforward on paper. A customer splits a purchase into four equal payments, with the first one due at checkout and the remaining three collected automatically every two weeks. Klarna, Afterpay, Affirm, and Sezzle all run on this basic structure. The merchant gets paid upfront minus a fee, usually between 4 and 6 percent of the transaction value. The customer gets the goods immediately and pays over six weeks. Everyone walks away thinking they won.
Pay In 4 Revolutionizes Checkout How Buy Now Pay Later Is Reshaping Consumer Spending
Here's what the marketing materials don't tell you. The real leverage isn't in the split-payment mechanics themselves. It's in the behavioral shift that happens when a $200 purchase suddenly feels like a $50 purchase. That psychological reframing is what drives conversion. Customers who wouldn't tap "buy" at full price will do it when the first charge looks manageable. And merchants who understand this stop treating BNPL as just another payment method and start using it as a pricing lever. I spent years integrating payment flows for mid-market e-commerce brands, and one edge case still comes to mind clearly. We were working with a subscription box company that wanted to offer their $120 quarterly box on the four-installment plan. The problem was that their billing system auto-processed the second payment two weeks after checkout, but the first shipment didn't ship until week three. Customers started receiving chargeback alerts because they were confused about why a payment hit before the box arrived. The workaround was simple but not obvious: we set the BNPL provider to delay the second installment by 14 days from the ship date rather than the checkout date, which required a manual configuration in the provider's API settings. Most platforms default to the checkout date, and the documentation buries this option under integration guides meant for enterprise accounts.
What Happens When Things Go Wrong
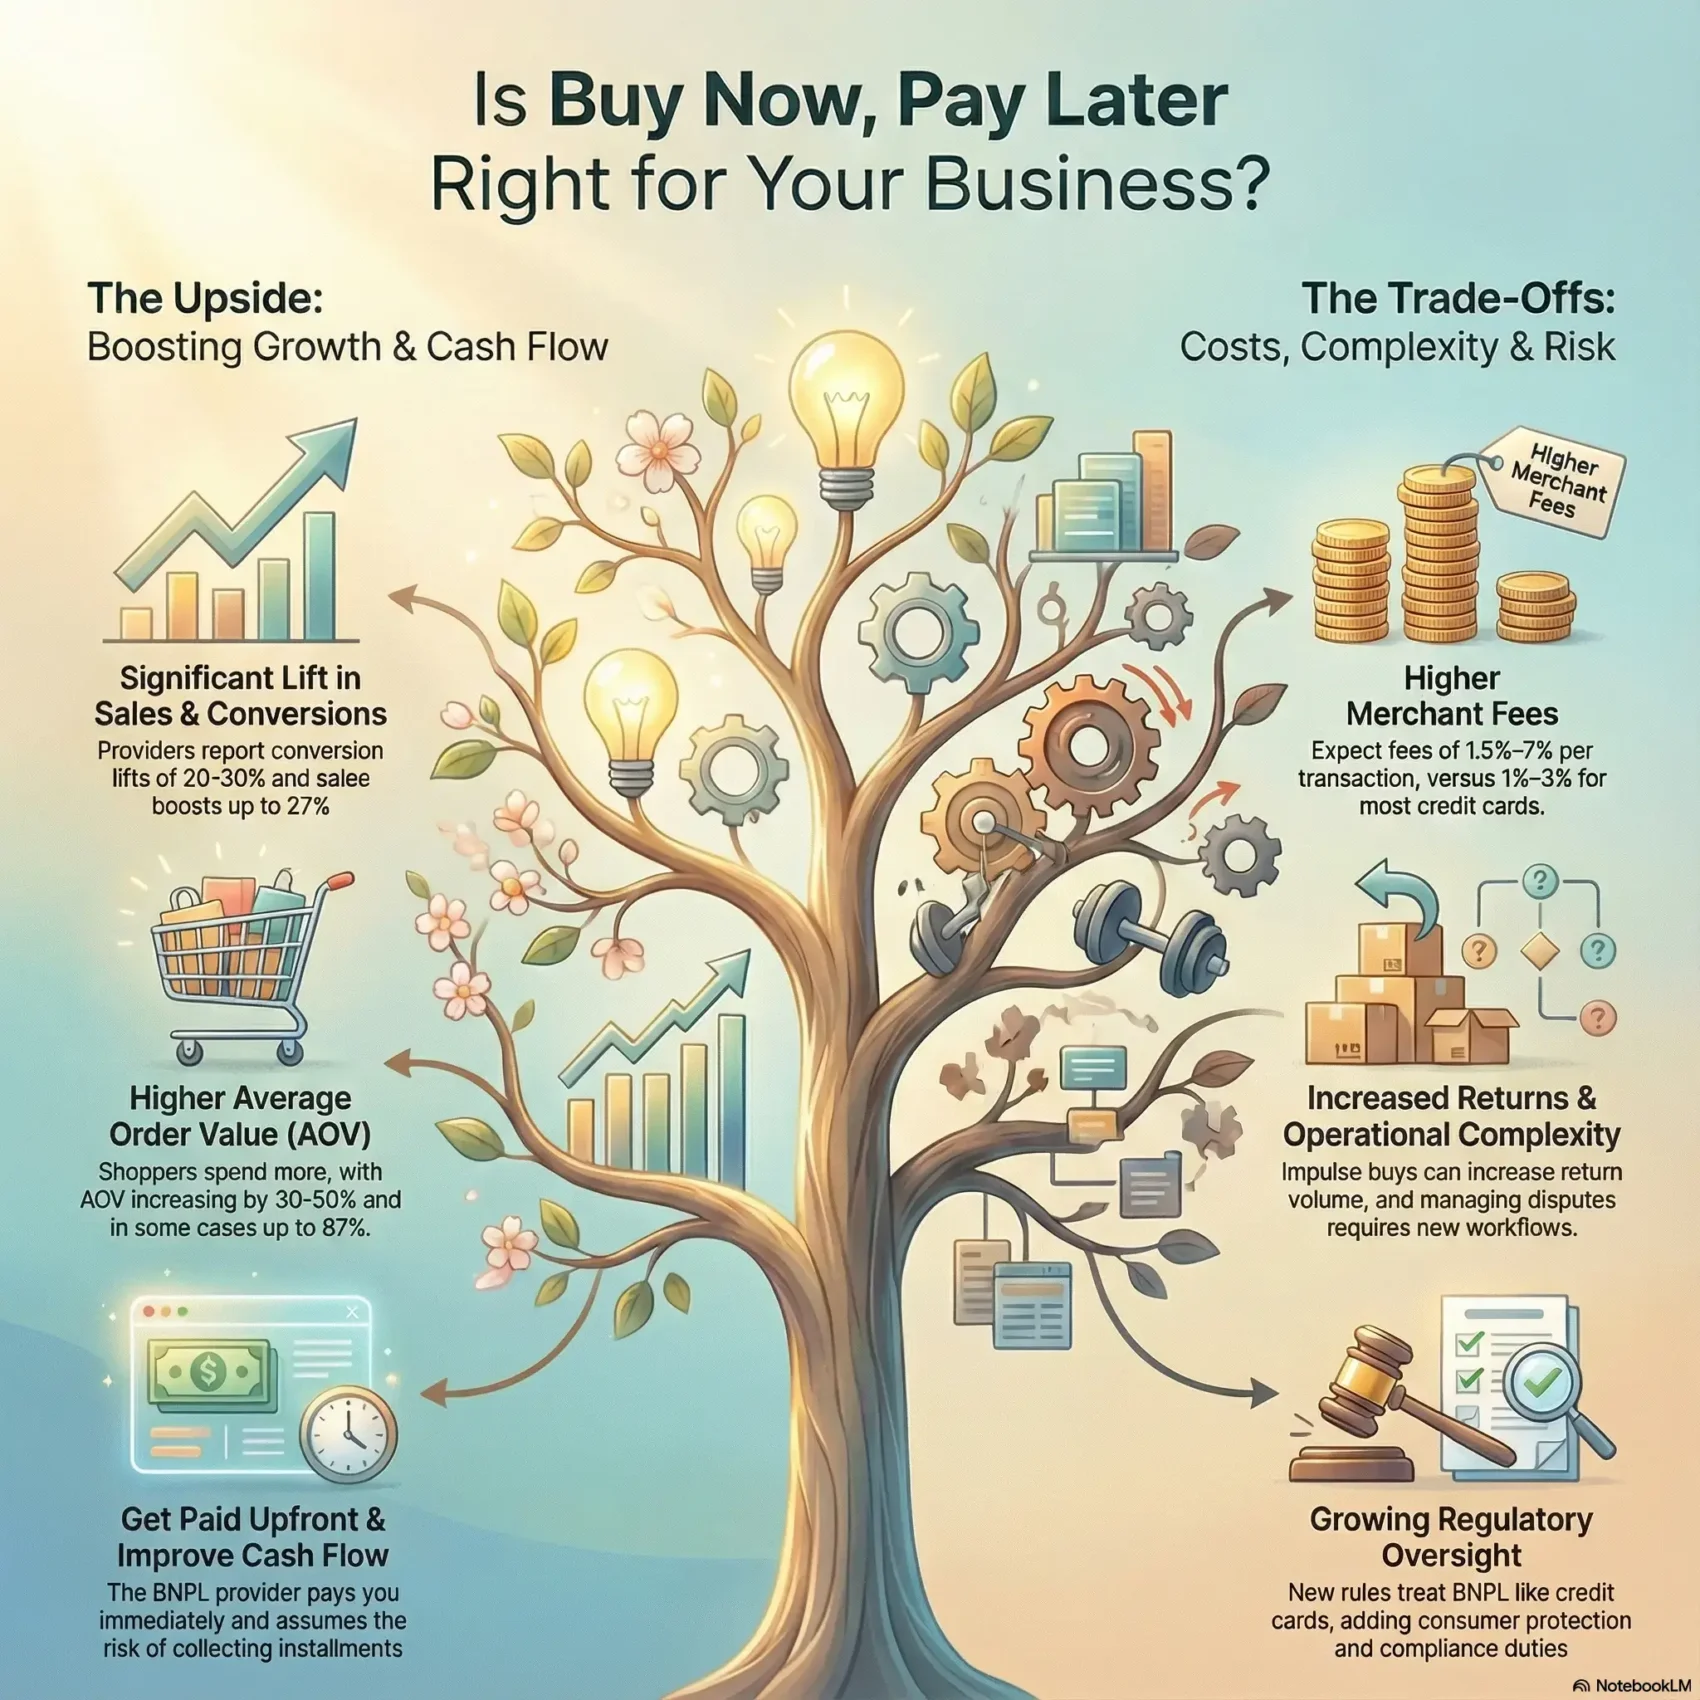
BNPL providers make money on merchant fees and late payment penalties, but they also carry risk. When a customer misses a payment, the provider doesn't come after the merchant. They chase the customer. However, chargebacks are a different story. If a customer disputes a charge and the provider hasn't yet collected the remaining installments, the merchant typically absorbs the loss on the full amount, not just the first payment. This is something most small business owners learn the hard way. The soft approval trap is another nuance people miss. BNPL providers run a soft credit check that doesn't affect the customer's credit score, but it does look at spending patterns across their entire portfolio of providers. A customer who has maxed out their Afterpay limit and their Klarna limit simultaneously might get declined on one platform but approved on another with a much lower spending cap. The result is that your checkout page shows an option that appears available, the customer selects it, and then gets a last-minute rejection at the payment screen. This kills conversion faster than any broken button. I've seen merchants try to solve this by enabling multiple BNPL providers at once. That sounds reasonable until you realize you're paying the 4 to 6 percent fee to two separate providers on the same sale, or worse, you're confusing customers with too many choices. The data from a handful of A/B tests I reviewed showed that offering a single BNPL option consistently outperformed offering multiple options by about 8 percent in conversion rate. Choice overload is real, even at checkout.
Get the Full Details

How to Actually Set It Up
If you're running a Shopify store, the easiest path is installing the app directly from the Shopify App Store. Klarna, Afterpay, and Sezzle all have first-party integrations that take maybe ten minutes to configure. You enter your account credentials, select which products or collections you want to offer the payment plan on, and the checkout button updates automatically. No developer required. For custom-built stores, you'll need to work with the provider's API or a middleware solution like Stripe Installments, which wraps multiple BNPL options into a single integration. The minimum viable setup takes about an hour. A properly configured setup that includes A/B testing, product-level restrictions, and fallback messaging for declined applications takes roughly six to eight hours spread across a couple of days. Don't skip the fallback messaging. When a customer gets declined, showing a generic error page costs you a sale. A message that says something like "You can also pay with monthly installments through our partner" with a link to an alternative provider keeps the door open. There's also the matter of reporting. BNPL transactions appear differently in your analytics dashboard depending on the provider. Some bundle them under "other payment methods." Others create a separate category. If you're trying to measure the actual impact on average order value and conversion rate, you need to pull the raw transaction data from the provider's dashboard, not just trust what your analytics platform is showing you. I learned this after spending three weeks trying to reconcile a discrepancy between my GA4 reports and my actual bank deposits.
Where This Approach Falls Apart
BNPL isn't universal. It works brilliantly for physical goods priced between $50 and $1,000. It works poorly for everything else. High-ticket items above $1,000 often exceed the spending limits that BNPL providers place on individual accounts, and the four-installment structure over six weeks doesn't provide meaningful relief for purchases that would benefit from longer repayment terms. Items under $50 don't generate enough margin to absorb the merchant fee without eroding profit to near zero. Subscription services are another problematic category because recurring charges interact badly with fixed installment schedules. There's also the regulatory landscape shifting under everyone's feet. The CFPB has been proposing rules that would treat BNPL providers more like traditional lenders, which could mean mandatory credit checks, stricter affordability assessments, and changed fee structures. Nothing has been finalized as of right now, but merchants who build their entire strategy around BNPL should be monitoring this closely. A regulatory change that forces providers to hard-check credit scores would eliminate one of the main selling points of the model for customers who've been turned down elsewhere. If your business model doesn't fit the sweet spot I described, alternatives exist. Traditional store financing through providers like PayPal Credit can handle a wider range of price points. Deferred interest promotions, when structured carefully, can approximate the BNPL experience without the same fee structure. And for B2B customers, net-30 or net-60 terms are often more appropriate and come with zero merchant processing fees.
The bottom line is that BNPL is a tool, not a strategy. It moves the needle for the right merchants at the right price points with the right product mix. It won't fix a broken storefront or a product market fit problem. Configure it carefully, track the actual numbers from the provider dashboard, and keep an eye on the regulatory horizon. Most importantly, don't assume that just because you enabled the option, customers will use it. Test different placements, different messaging, and different product eligibility rules. The difference between a mediocre implementation and a good one is usually something small that most people never think to check.