Capitalizing in Finance is Mostly About Intuition Until It Isn't
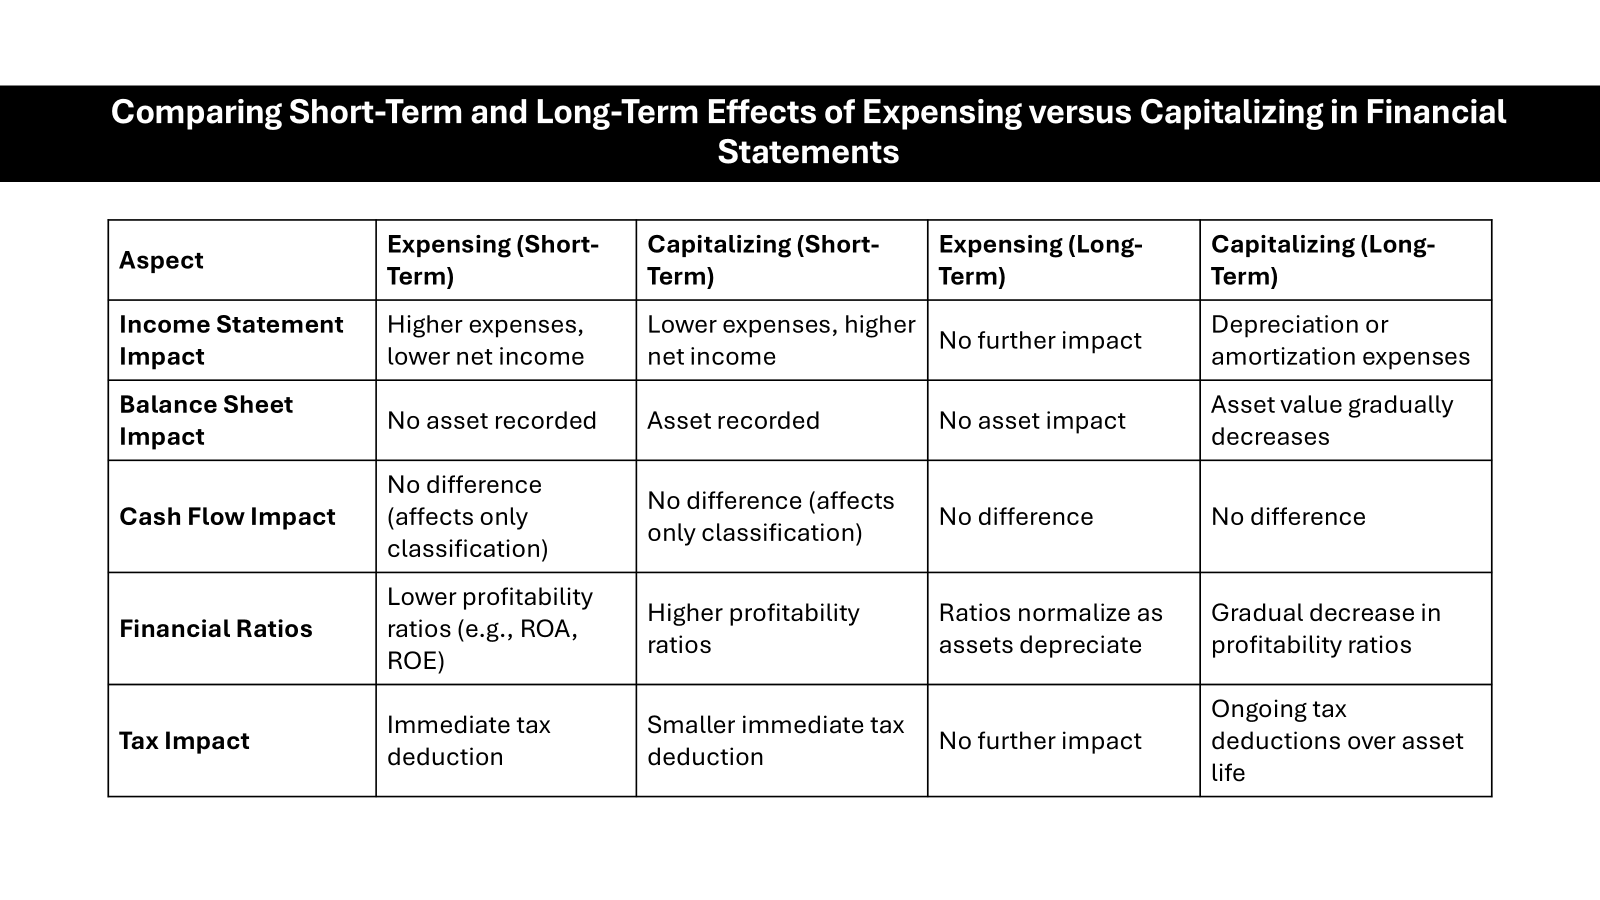
I spent years doing deal documentation and audit prep before I actually understood when to capitalize versus expense something. The basic rule is simple enough: if it provides long-term benefit to the business, capitalize it. If it's consumed in the normal course of operations, expense it. That's what every textbook says. The real world is messier. Start with the asset recognition criteria from IFRS or your local GAAP. The item must be controlled by the entity, probable future economic benefits will flow to it, and the cost can be measured reliably. Three conditions. Miss any one of them and you're expensing it, no debate. Here's where people get confused. "Long-term" doesn't strictly mean more than a year. Some frameworks say the benefit period just needs to extend beyond the current reporting period. In practice, I've seen companies capitalize equipment with six-month useful lives because they expected repeated use across multiple quarters. That was technically defensible but drew questions from auditors who preferred a cleaner bright line at twelve months.
I once worked on a software implementation where we capitalized $400,000 of internal development costs. The project lasted fourteen months. We stopped capitalizing during the pilot phase because the software couldn't reliably produce its intended output yet. IAS 38 is explicit about that – you can only capitalize development costs once technical feasibility is established. The hard part is defining when feasibility starts. It's not a technical milestone, it's a judgment call. We drew the line at successful UAT sign-off. Every stakeholder agreed afterward, but I still remember the tension around that decision. Training costs are another common trap. You capitalize direct costs of creating or obtaining an intangible asset, but general employee training usually doesn't qualify unless it's directly attributable to making a specific asset usable. I've seen finance teams capitalize onboarding costs for new ERP implementations. That was wrong and we reversed it during an audit. Took three weeks to rework the journal entries. Interest capitalization under IAS 23 is where the mechanics get tedious but the rules are clearer. You capitalize borrowing costs directly attributable to qualifying assets – basically assets that take a substantial period of time to get ready for use. Construction projects, manufactured inventory for sale, and certain intangible projects qualify. General corporate overhead doesn't. The tricky part is the suspension rule: you stop capitalizing interest when the asset is substantially ready for its intended use, not when it's actually in use. There was a warehouse project where we kept capitalizing interest for six weeks after the building was operational because we were waiting for outdoor landscaping to finish. Our auditor disagreed. Landscaping was incidental to the building's primary function. We had to adjust the entry and eat the interest expense.
Repairs versus improvements is the perpetual headache. A routine maintenance schedule is expensed. An upgrade that extends useful life, increases capacity, or improves efficiency gets capitalized. The line between "maintains" and "improves" is subjective. I've seen the same type of HVAC replacement classified differently by two different companies in the same industry. The tax authority generally doesn't care as much as the auditors do, but inconsistent treatment across your own portfolio raises flags. One practical shortcut: create a capitalization threshold policy and stick to it. $5,000 is common. $10,000 if you're a larger entity. Below the threshold, expense everything regardless of useful life. This isn't theoretically perfect but it's universally accepted and it saves enormous time. My current company uses $2,500 because our asset volume is high and the administrative cost of tracking low-value items exceeds the benefit. The policy is documented in our accounting manual and auditors don't question it. Impairment testing follows capitalization. Once something is on the balance sheet, you need to test it periodically. Goodwill and indefinite-lived intangibles require annual testing. Everything else gets tested only when there's an indicator of impairment. The indicator concept is deliberately vague – changing market conditions, obsolescence, legal restrictions, worse-than-expected performance. I once had to test a fleet of vehicles for impairment after an regulatory change made half of them non-compliant overnight. The recoverable amount dropped below carrying value and we took a $1.2 million write-down. The capitalization work from three years prior meant we had a solid depreciation schedule to work from, which made the impairment calculation straightforward. That's the upside of getting the initial recognition right.
Get the Full Details
If you're using a spreadsheet-based system rather than proper ERP software, the biggest risk is version control and audit trail. I've seen capitalization schedules where someone edited a useful life assumption without recording why. When the auditor asked, the answer was "it felt wrong." That's not defensible. Whatever tool you use, every change to a fixed asset record needs a documented rationale. Even a simple field in your tracking system that captures the date, the person, and the reason for the change is better than nothing. The other thing nobody warns you about is the tax versus book difference. Depreciation for financial reporting purposes and depreciation for tax purposes often follow different schedules and conventions. Setting up and maintaining the deferred tax calculations for those differences takes time. Don't underestimate it. A mid-size company with several hundred fixed assets can spend weeks each year reconciling the two schedules. Automating the gross fixed asset register helps, but the reconciliation logic itself usually requires custom work. For most companies, the process goes like this. Acquisitions and new purchases trigger capitalization entries at cost. Cost includes purchase price, import duties, non-refundable taxes, and directly attributable installation and professional fees. Less any trade discounts or rebates. Don't forget freight-in. It's easy to overlook and it's material if you're importing equipment.
Ongoing additions and improvements follow the same principle but the allocation between capital and expense is where the judgment lives. Component accounting under IFRS requires you to capitalize significant parts of an asset separately even if they're not purchased separately. A commercial airplane is the textbook example – engines, interior, and airframe each have different useful lives. A simpler example is a building with a roof. If you replace the roof, you capitalize the new roof and remove the carrying amount of the old one. The old roof's remaining book value becomes a loss. It feels harsh but it's correct. Disposals and retirements are where most errors surface. You derecognize the asset, remove accumulated depreciation, and recognize any gain or loss. The error pattern I see most often is forgetting to remove the asset from the register entirely, leaving it to depreciate into perpetuity. The fix is a full physical verification at least once a year, ideally with tagging and barcodes. My last company did a full count and found forty-seven assets that had been disposed of over the prior three years but never removed from the ledger. The accumulated depreciation error was about $80,000. Not catastrophic but embarrassing for a finance team. Software capitalization deserves its own attention because the rules shifted slightly with the introduction of cloud computing. Internal costs of developing or obtaining software for internal use can be capitalized from the point of preliminary project completion onward. That means research phase costs go to expense, application development phase costs can be capitalized, and post-implementation costs are generally expensed. Hosting costs for SaaS arrangements are usually operating expenses unless you're building the infrastructure yourself. The boundary between hosting and ownership is blurrier now than it was ten years ago, and standard-setters are still figuring out how to address it cleanly.
If you need a practical starting point, pull your chart of accounts and review the expense categories that have large balances. Look for recurring payments that might be capitalizable. Vendor invoices for equipment, license fees for software, construction contracts, and professional services related to asset acquisition are the usual suspects. Run the three-condition test on each one. Document the conclusion. Move forward. The downside of being too aggressive with capitalization is overstated assets and inflated earnings, which attracts scrutiny. The downside of being too conservative is understated assets, which makes your balance sheet look weaker than it is. Both extremes distort ratios. The sweet spot is applying the criteria consistently and documenting your reasoning so someone else can follow the same logic next time. Most of the guidance I've seen online covers the theory well but skips the edge cases. The edge cases are where the job actually lives. A lease with a purchase option that becomes reasonably certain to be exercised. A warranty that extends beyond the standard period and provides additional benefit. A retrofit that combines repair with modernization. These show up on every balance sheet eventually. Having a policy that anticipates them saves a lot of late-night spreadsheet work.

I don't have a download link to share because this isn't a tool or a template you can package. It's a set of judgment calls backed by standards that change slowly but not silently. The best resource I've found is just keeping the relevant standard close at hand and reading the implementation guidance, not just the main text. The main text tells you what to do. The implementation guidance tells you what other people have struggled with, which is usually more useful.