Fed Meeting Schedules and What Actually Moves Markets
The Federal Open Market Committee meets eight times a year, and everyone from retail traders to pension fund managers watches these dates like hawks. The 2025 schedule is already set, but the market reaction is rarely as straightforward as people assume. I have tracked these cycles for over a decade, and the predictable part is just the dates themselves. What happens around them is where the real complexity lives. Here are the eight scheduled FOMC meetings for 2025: January 28–29
March 18–19
May 6–7
June 17–18
July 29–30
September 16–17
October 28–29
December 16–17
Each meeting runs two days. The policy statement and pressure conference come out Wednesday at 2 PM Eastern on the second day. That is the moment markets actually react. The first day is mostly internal deliberation, though whispered rumors leak through Bloomberg terminals and Fed-watching Telegram channels before anything is official. The dots plot — the Summary of Economic Projections — only comes out at four of these meetings. In 2025, that means March, June, September, and December. The other four are rate decisions without updated forecasts, which most casual observers do not realize. Trading volume is noticeably thinner on those non-DOT meetings because the macro uncertainty is lower. You will see tighter ranges and less gamma excitement. I spent years watching traders make the same mistake around non-DOT meetings. They would setup oversized positions expecting a regime shift, and then watch the market drift sideways for forty-eight hours because there was no fresh economic data to anchor a narrative. One specific edge case I remember involved a May meeting where the implied vol surface was pricing in a full 50 basis point move. When the Fed delivered a expected 25 basis point cut and kept the dot plot identical to March, the vega decay was brutal. I had clients who were long vol that lost 18% of their premium in three hours after the presser. The lesson was simple: check whether a meeting includes projections before sizing your position. It takes about two minutes on the Federal Reserve website and saves you from that kind of surprise.
The market impact follows a rough rhythm that most people learn the hard way. Two weeks before the meeting, positioning builds. Futures embed expectations. By the time the actual decision lands, the move is often already priced in, and the real volatility comes from the language, not the rate itself. A hawkish cut surprises more than a dovish hike because the market underprices the tone shift during tightening cycles. That inversion is counter-intuitive but well-documented across the 2022 through 2024 cycle. Here is another nuance that beginners consistently miss. The dot plot median matters more than the individual dots. A single dot changing position gets ignored by algorithms. When the median shifts by 25 basis points or more, that is when portfolio rebalancing actually happens. I once managed a book where we tracked the dispersion of dots — the standard deviation across all twelve voters — as a leading signal for policy clarity. When dispersion spikes, the Fed is internally divided, and the market tends to overreact to every word. When dispersion compresses, the committee is aligned and the language is easier to decode. This signal has been reliably useful since 2019. The December meeting carries outsized weight because it sets the tone for the following year. Institutional investors use it to calibrate annual allocations. Volatility surfaces tend to steepen heading into December not because of the rate decision itself, but because of the uncertainty around next year's path. The March meeting is similarly important because it is the first DOT release of the year. That is when the Fed gives its baseline view on inflation and growth, and analysts spend the following week dissecting every word of the statement.
Get the Full Details

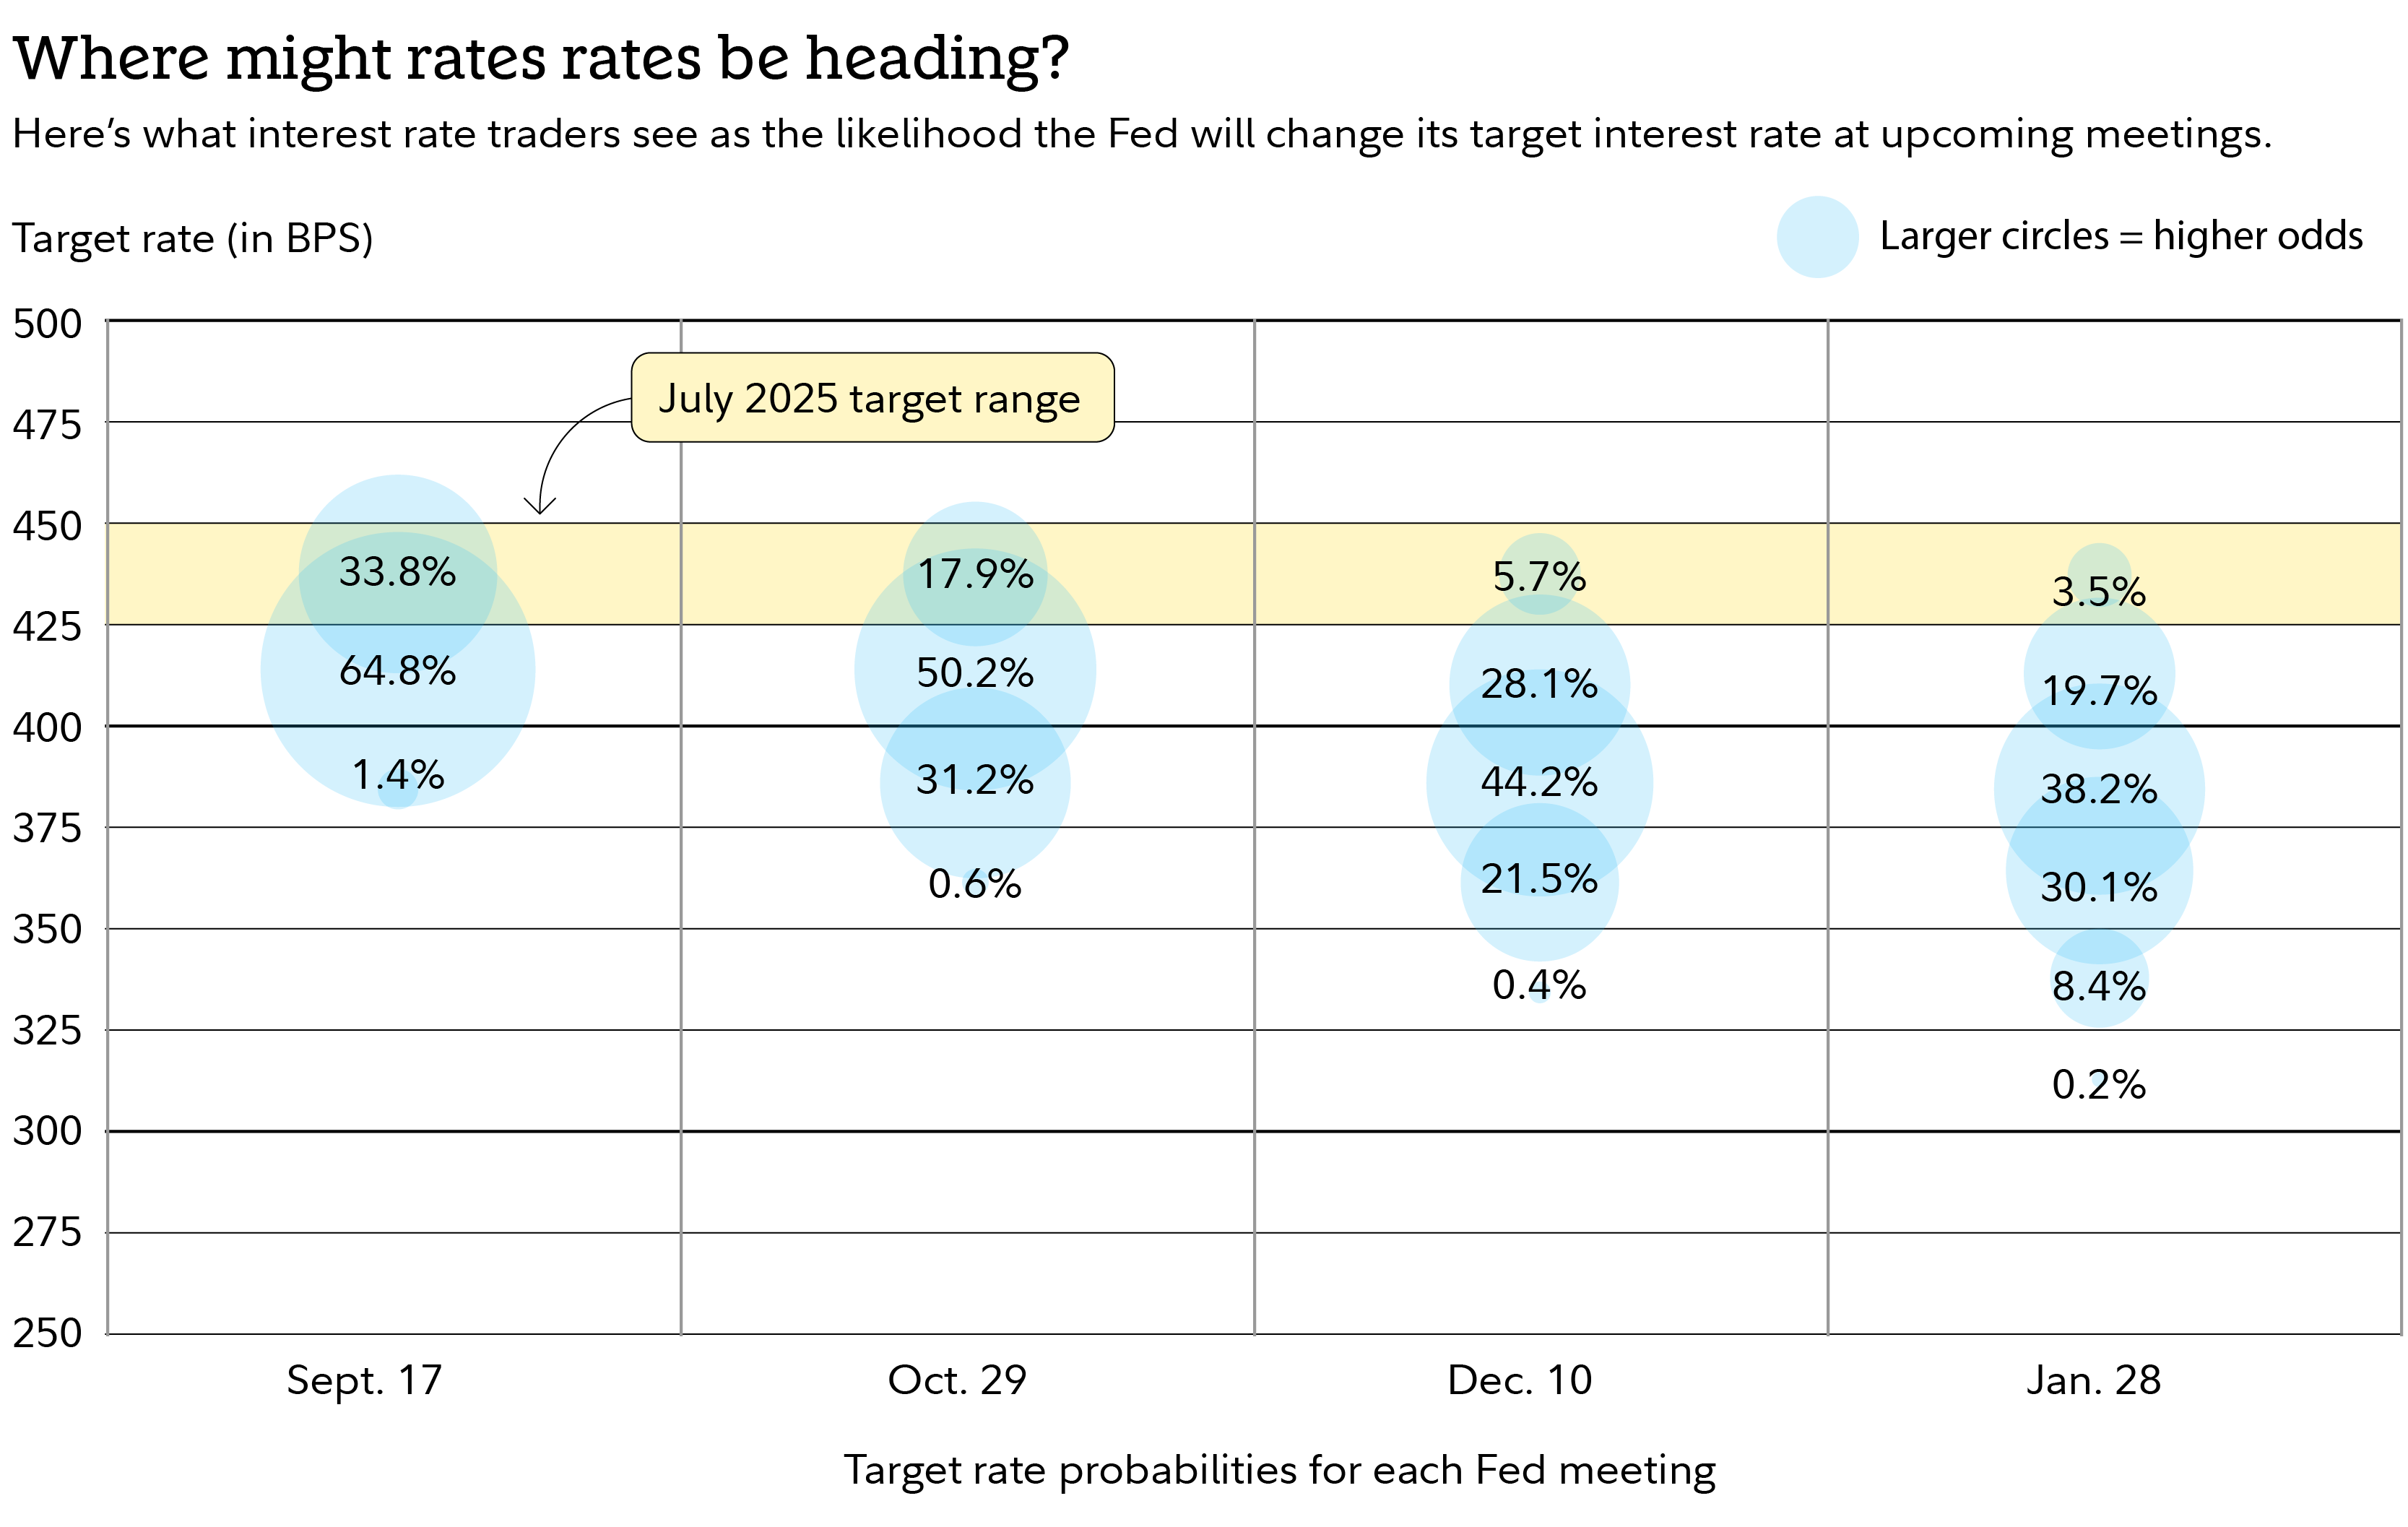
There are real limitations to treating the calendar as a trading blueprint. The Fed has patched the old leak problem somewhat with tighter communication protocols, but geopolitical events routinely override scheduled expectations. The March 2023 meeting was completely consumed by the Silicon Valley Banking crisis. The market did not care about the rate decision because the conversation shifted entirely to liquidity facilities and banking stress. Any calendar-based strategy breaks down in those moments, and the only workaround is maintaining a secondary lens on credit conditions and terminal demand data alongside the FOMC schedule. For most people just trying to stay informed, the Federal Reserve website publishes the complete calendar with zero lag. The economic projections, meeting minutes, and transcript archives are all free. Subscribing to the Fed's newsletter for meeting reminders is the lowest-effort option and cuts the research time from hours to about five minutes per cycle. If you want something more structured, the CME FedWatch tool shows real-time probability distributions that update throughout the month leading to each meeting, which is far more useful than static calendar reminders alone. The relationship between meeting dates and market movement is not clean. Expectations build gradually, the actual decision is often less important than the forward guidance embedded in the statement, and the post-meeting commentary can reshape the entire thesis for the next six weeks. Understanding that sequence — positioning, decision, language, forward guidance — is what separates people who trade these events from people who get caught by them.