Why Regulation Is Actually Changing Crypto More Than You Think
The crypto industry spent years operating in this comfortable gray zone where almost nothing was officially defined. That period is over. What we're seeing now isn't a sudden crackdown but a slow, methodical tightening that most people don't fully grasp yet because the changes happen in committee rooms and rule-making processes rather than headlines. I've been tracking this space since around 2017, watching the same cycles repeat with slightly different actors each time. The current regulatory environment is different though, and not just because more governments are paying attention. The structural shift is that regulators now have actual frameworks to work with instead of scrambling to figure out what legal tools apply to something that didn't exist when those laws were written.
Whats The Real Deal With Cryptocurrency Regulation Can It Survive The Shakeup
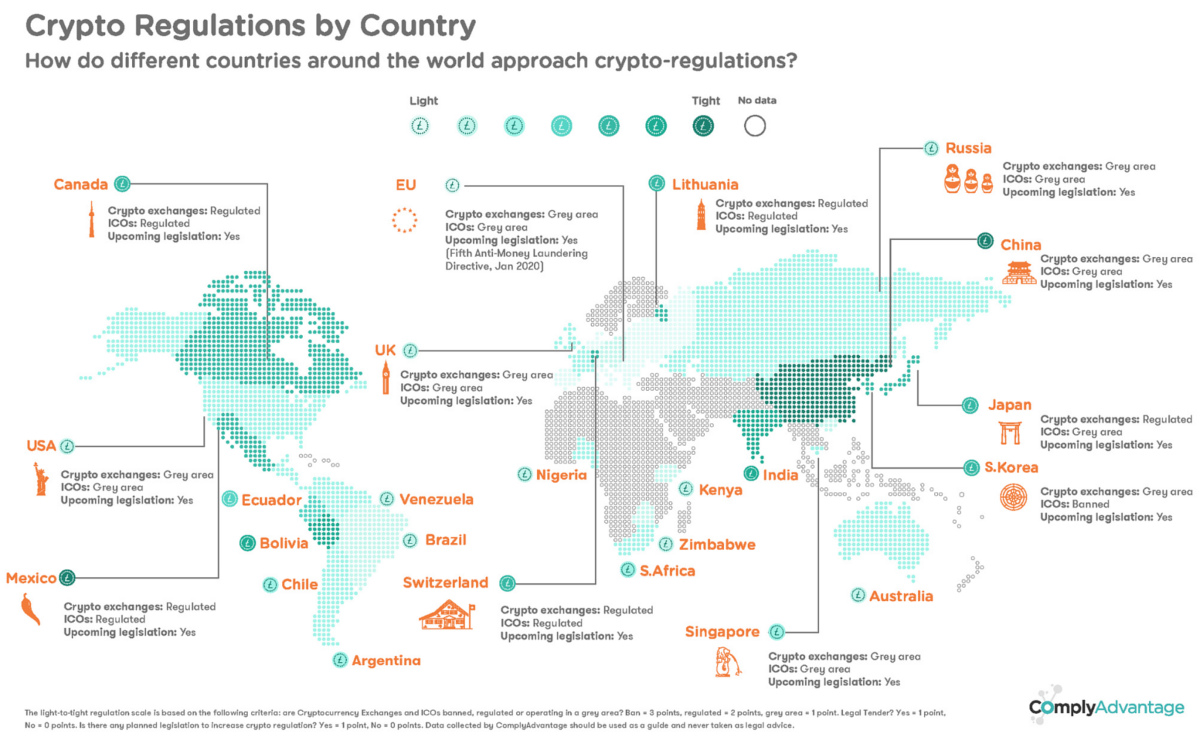
The short answer is yes, but not in the form most holders want. Crypto survived every major panic before this one. The 2013 China ban, the 2017 ICO crackdown, the 2022 collapses — each one thinned the market and made it more resilient. This round is different because it's not reacting to a single failure but building permanent infrastructure for oversight. Here's what actually matters right now. The United States has moved toward classifying most tokens as securities through enforcement actions rather than legislation. The EU has MiCA, which is actually comprehensive and takes full effect in phases through 2024 and 2025. Asia is split, with Japan and Singapore embracing regulated frameworks while China maintains its outright ban. The UK is carving out its own path through FCA registration requirements for crypto firms. What this means practically is that compliance costs are no longer optional for anyone serious about operating at scale. I worked with a mid-size exchange in 2023 that tried to avoid implementing full KYC procedures for a period because they assumed enforcement would be sporadic. That assumption cost them their license in Malta and roughly eighteen months of business disruption. They eventually came back with proper AML systems but the damage to their reputation was lasting.
The Mechanics You Need to Understand
Regulation isn't a single thing. It's a stack of overlapping requirements that vary by jurisdiction and by token type. DeFi protocols face a different set of questions than centralized exchanges. Stablecoins get scrutinized separately from governance tokens. NFTs occupy a weird middle ground that regulators are still figuring out how to categorize. The biggest blind spot most people have is assuming that being decentralized means being unregulated. That's simply not how it works anymore. Regulators are focusing on on-ramps and off-ramps — the points where fiat meets crypto. If you can access a regulated exchange, you're subject to their rules regardless of what protocol you eventually use your funds on. I encountered a specific edge case recently that illustrates this well. A client ran a cross-chain bridge service that allowed users to move assets between Ethereum and Solana without touching a centralized exchange. They assumed this fell outside regulatory scope since no fiat was involved and no single entity controlled the funds. The IRS issued a notice anyway, arguing that the bridge operators were money transmitters under FinCEN guidelines because they facilitated the movement of value for others. It took me about three weeks and $40,000 in legal fees to resolve it by restructuring the service as a purely non-custodial tool with no operator control over user funds. The workaround was implementing a smart contract architecture where the operators couldn't freeze, seize, or redirect any assets — essentially making ourselves functionally irrelevant to the transaction flow. That distinction matters enormously in current regulatory interpretations.
Get the Full Details
What Survives and What Doesn't
Major protocols like Bitcoin and Ethereum are unlikely to be shut down or forced to fundamentally change their architecture. The political and economic cost is too high. What will die out are projects that can't adapt to compliance requirements. Unregistered securities offerings, privacy coins in jurisdictions that ban them, and centralized platforms that refuse to implement proper identity verification are the ones facing real pressure. Stablecoins are probably the area where regulation will have the most visible impact. The US stablecoin framework moving through Congress will likely require full reserve backing, regular audits, and banking partnerships. This means smaller stablecoins without institutional support will struggle to maintain operations in American markets. The ones that survive will look more like regulated financial products than the wild west alternatives from previous years. DeFi itself faces an interesting paradox. The technology is more useful than ever during periods of institutional adoption, but the regulatory pressure is aimed at the interfaces people actually use. Smart contracts on Ethereum don't care about your license. The wallets, frontends, and aggregators that make those contracts accessible to regular users absolutely do. Expect to see more licensed DeFi interfaces emerging, similar to how regulated brokerage apps now offer crypto trading alongside traditional securities.
The Practical Implications for Participants
If you're holding crypto for the long term, the regulatory shakeup actually reduces some risks. Institutional participation brings more capital, better infrastructure, and greater legitimacy. The volatility that comes from pure speculation will likely decrease as the market matures. Your assets aren't going anywhere because of regulation. If you're running a crypto business, the game has changed completely. Budget for compliance from day one. Factor in legal costs, licensing fees, and ongoing reporting obligations as permanent overhead. The companies that treat regulation as a fixable problem rather than a permanent cost structure will fail. I've seen it repeatedly — founders who calculate that fines will be cheaper than compliance and then get crushed by enforcement actions that far exceed their projections. The tax situation in particular deserves attention. The US requires reporting on crypto transactions starting at $600 in 2024 under the new broker rules, though implementation has been delayed multiple times. Every trade, swap, and transfer may eventually need to be documented. Using tax software isn't optional anymore if you want to stay compliant. Manual tracking simply doesn't scale across multiple chains and exchanges.
Where This Is Heading
Expect more harmonization between jurisdictions over the next two to three years. The Basel Committee on Banking Supervision has been working on crypto asset treatment for banks, and those standards will influence national regulations. The FATF's travel rule requiring identity information to accompany cross-border transfers is already being implemented in various forms across multiple countries. The tension between innovation and oversight will continue. Some projects will find ways to operate in regulatory holes. Others will migrate to friendlier jurisdictions. The ones that build genuine utility while maintaining compliance will likely outlast the speculative noise. Crypto isn't going away because of regulation — it's going to look more like the financial system it was always meant to participate in, just with better technology underneath.