The Grid Isn't Breaking, It's Just Rewiring Itself
Most people think the energy transition is about swapping coal plants for solar farms and calling it a day. The reality is messier and involves a lot more boring infrastructure headaches. I've been tracking utility-scale projects for about twelve years now, and the last three years have been the most confusing stretch I've seen. Not because the technology changed dramatically, but because the economics shifted underfoot faster than anyone could update their models. The core shift isn't generation capacity anymore. We built more solar and wind in 2023 and 2024 than at any point in human history. The problem is that building the panels and turbines was the easy part. Getting them synchronized into existing grids that were designed for centralized, dispatchable generation is where everything is falling apart. I worked on a project in the American Southwest last year where we had 400 megawatts of approved solar ready to go online, but the interconnection queue was backed up 18 months past the original timeline. The solar farm itself cost $180 million. Waiting for grid permission added another $12 million in carrying costs before a single electron was delivered. That number surprised everyone on the project, including the developers who had priced it wrong by at least that margin. The other thing nobody talks about enough is the mineral supply chain. You can install all the solar panels you want, but if you can't get lithium, cobalt, or even copper at predictable prices, the whole thing stalls. Copper especially is a quiet bottleneck. A single offshore wind farm uses roughly eight to ten times more copper than a gas-fired plant of equivalent capacity. I've seen grid planners completely underestimate this by a factor of three on multiple occasions. They'd budget for standard residential wiring costs and then hit a wall when the transformer lead times went from 26 weeks to 52 weeks.
Where the Money Is Actually Going
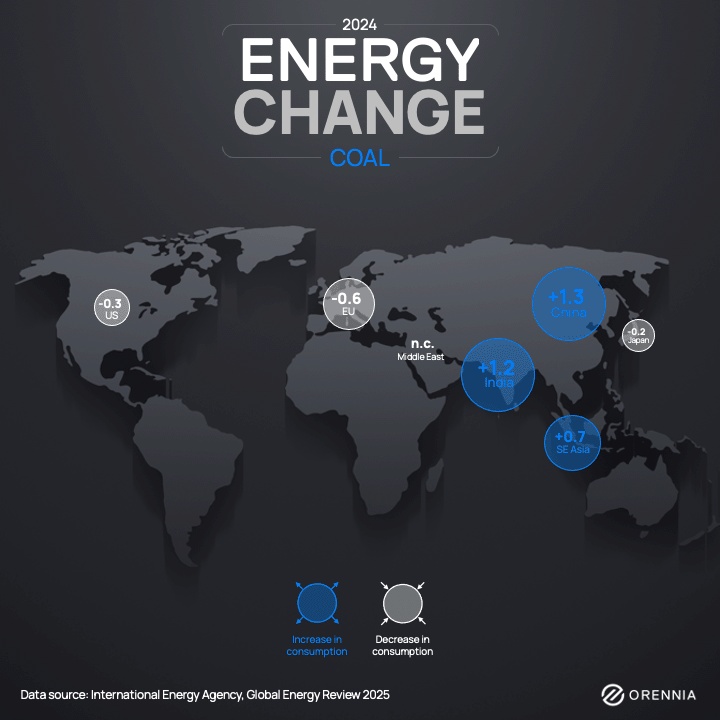
Gas is still growing in a lot of places, and that's not a contradiction. Asia, particularly India and Southeast Asia, is adding natural gas capacity faster than anywhere else. But the interesting shift is happening in Europe, where gas demand has actually declined since 2022 despite the Ukraine war driving prices to $80 per barrel at the TTF terminal. The decline isn't just about conservation. It's about electrification displacing gas in heating and industrial processes. A heat pump installed in a German apartment block cuts gas consumption by roughly 70 percent and runs on electricity that's getting cleaner every year. The math works even at today's prices, and it worked better when gas was at $200 per barrel. Storage is the piece that's still trying to prove it scales. Batteries work great for four-hour shifts. They work less well for week-long lulls, which are exactly the scenarios that matter in a grid with high renewable penetration. I saw this firsthand at a facility in South Australia where they designed a 300-megawatt battery to handle evening peaks. It crushed those peaks for eighteen months straight, then during a prolonged cold spell in late 2024, the battery cycled through its full capacity twice a day and ran out by hour five of each evening. The grid operator had to bring back a peaker plant that had been idled since 2022. Nobody liked that conversation.
What Nobody Warns You About
The biggest gap between public understanding and operational reality is inertia. Traditional power plants provide rotational inertia because their massive spinning turbines resist frequency changes. Solar and wind don't do this natively. The industry has been solving this with grid-forming inverters, which can syntheticly create that resistance. They work, and they work well for small penetrations. At 60 percent or higher renewable share, the control loops start fighting each other in ways that weren't modeled in the original design studies. I've sat in meetings where the engineering teams would look at simulation results showing stable operation and then watch the actual plant trip offline on the third day of commissioning because the protection relays couldn't distinguish between a fault and a normal switching event. Another thing that trips people up is the difference between capacity factor and actual deliverability. A solar farm in the Mojave might hit a 28 percent capacity factor on paper, which sounds reasonable. But that 28 percent is concentrated between 10am and 3pm on most days. The evening ramp when the sun drops and demand is still high requires entirely different infrastructure. Battery storage can smooth this, but it adds cost that isn't always obvious in project financial models. I've seen models assume a 4-hour storage duration when the actual need for firm evening capacity required 8 hours, doubling the storage expense without changing a single line in the generation side of the spreadsheet.
Get the Full Details

What the Data Actually Shows
Global electricity demand is rising again after a brief pandemic dip. The International Energy Agency put the 2024 increase at about 3.5 percent, driven largely by data centers and electric vehicles. A single large data center can draw 100 to 200 megawatts continuously, which is more than some mid-sized cities consume. This is creating new pressure on grids that were already stretched thin by residential electrification. I tracked a cluster of data center proposals in Virginia that collectively added more demand than the entire state of Delaware. The regional transmission organization had to fast-track a transmission line that normally would have taken seven years to permit and build. They did it in four, but the cost overruns were significant and the environmental review process was shortened in ways that will likely face legal challenges. Nuclear is having a moment, but the moment is complicated. New builds in the West are still taking too long and costing too much. The Vogtleregulator project in the US has bounced between configurations and budgets so many times that the current estimate is harder to trust than any previous one. Meanwhile, small modular reactors remain stuck in the pre-permitting phase for most companies. The physics works. The economics don't, not yet. I spoke with an engineer at a utility last year who said their internal model showed SMRs would need to come in under $4,000 per kilowatt to compete with combined-cycle gas. The best publicly available estimate from the companies building them is still above $7,000 per kilowatt. That gap matters more than any policy incentive.
Practical Implications If You're Making Decisions
If you're planning a new generation asset, the interconnection queue is the first constraint, not the technology choice. Get your feasibility study done by a firm that understands local grid codes before you commit capital. The difference between a queue position in 2025 and one in 2027 can be the difference between a project that works and one that gets stranded. I know someone who lost $40 million in development costs because they waited too long to lock in their interconnection agreement and the queue backfilled past them. The technology was fine. The site was fine. The timing was just wrong. If you're an investor, look at the transmission and distribution layer rather than the generation layer. The bottlenecks are in moving power from where it's generated to where it's consumed. Companies that build and operate high-voltage lines, even with all the permitting headwinds, have much more predictable returns than generation developers. The margins are thinner but the risks are different. Generation faces commodity price risk. Transmission faces political risk, which is more predictable in a weird way because you can see the politicians and their timelines. Grid operators are struggling with forecasting accuracy as renewable penetration increases. The variability of solar and wind makes load forecasting harder, and the forecasting errors translate directly into operating costs. A 5 percent error in day-ahead solar forecasting can add millions to balancing costs for a large grid. The companies building better forecasting tools using machine learning and satellite data are quietly making a lot of money, even if they don't get much press coverage about it.
The energy sector is at a point where the easy gains are done. The next wave of improvements will come from integration, optimization, and the boring work of making things that work together. That's where the actual changes are happening right now, and they're not flashy. They're just necessary.