The Grid Doesn't Care About Your Timeline
I spent three years working behind the scenes on a cross-border interconnection project in Northern Europe and let me tell you something that won't surprise anyone who's been in this space long enough to get annoyed by headlines: the energy transition isn't happening in some clean, orderly fashion. It's happening in spreadsheets, in permitting queues, and in the quiet frustration of engineers who watch a perfectly good wind project sit dormant because a single substation upgrade hasn't been approved. The global energy landscape is undergoing a structural realignment that has less to do with climate policy and more to do with basic supply chain mechanics, labor availability, and the sheer reality that building new energy infrastructure takes considerably longer than the press releases suggest. Here's the thing most people miss when they read the quarterly reports about record renewable capacity additions. The headline number tells you how much new solar or wind nameplate capacity was installed in a given year. It doesn't tell you how much of that capacity actually reached the point of generating electricity, how much grid connection time was added to the queue, or whether the copper, aluminum, and rare earth minerals needed to connect that capacity were actually available at a price the project could absorb.
I remember sitting in a meeting with a developer who had a 500-megawatt solar farm ready to interconnect. The utility told them their queue position was fine but the transformer substation they needed was backed up eighteen months out because every other project in the region had the same queue position. Eighteen months. The solar panels were already manufactured and sitting in a warehouse. The land was cleared. The permits were signed. The only thing standing between that project and revenue was a piece of electrical equipment that couldn't be expedited because the global supply chain for power transformers was running on roughly six-to-nine-month lead times in 2023 and it hasn't really improved since. This is the actual bottleneck nobody talks about in the optimistic projections. It's not technology. Solar panels work. Wind turbines work. Batteries work, mostly. The bottleneck is the physical infrastructure that connects them to the grid and moves the electrons from where they're generated to where someone is actually using them. The geopolitical dimension of this shift is also getting mischaracterized. People talk about the energy transition as if it's simply replacing fossil fuel dependence with renewable dependence, which implies the power dynamics just flip. What's actually happening is more complicated and arguably more disruptive. China controls roughly sixty percent of the global solar panel manufacturing capacity and about ninety percent of the polysilicon processing. They also control the vast majority of lithium refining, cobalt processing, and the production of critical mineral components used in wind turbine magnets. The United States and Europe are spending hundreds of billions trying to onshore or friendshore these supply chains and they're running into the same problem that every industrial policy initiative hits eventually: you can allocate capital faster than you can build competence.
I worked with a team that tried to source a domestic supply of transformer-grade silicon steel for a transmission project and the entire United States produces maybe two facilities worth of that material right now. Two. The rest comes from Japan, China, and Germany. There is no quick alternative because building a silicon steel mill isn't something you do over a summer. It's a multi-year, hundred-million-dollar bet on a material that almost nobody has been ordering more of for the last decade.
Get the Full Details

What Actually Drives The Transition Forward
Cost curves don't lie and they've been lying in favor of renewables for a while now. Utility-scale solar in the United States has hit below three cents per kilowatt-hour in some auctions. Onshore wind is similarly cheap where the resources exist. This is why the capital is flowing. It's not primarily ideological. It's arithmetic. The problem is that cheap electricity generation and reliable electricity delivery are two completely different engineering problems. A solar farm that generates power at three cents per megawatt-hour is useless if you can't get that power out of the desert where it was built and into a city three hundred miles away where people actually need it. Transmission is the hard part. It always has been. I've watched projects get killed by local opposition not because people opposed renewable energy in principle but because they didn't want a high-voltage transmission line running through their county. This is NIMBYism at the infrastructure scale and it's one of the single most effective blockers in the entire energy transition. A typical overhead transmission line in the United States faces an average of five to seven years of permitting and legal challenges before construction begins. In Europe the numbers are worse in some countries because the environmental review requirements are more stringent and the community consultation processes are more extensive.
The counterintuitive insight here is that the countries with the strongest climate policies and the most ambitious renewable targets often face the slowest deployment rates precisely because their permitting frameworks are designed to be thorough and participatory. Speed and deliberation are generally at odds with each other when you're moving dirt and steel across landscapes that people live on.
The Geopolitical Realignment Nobody's Writing About
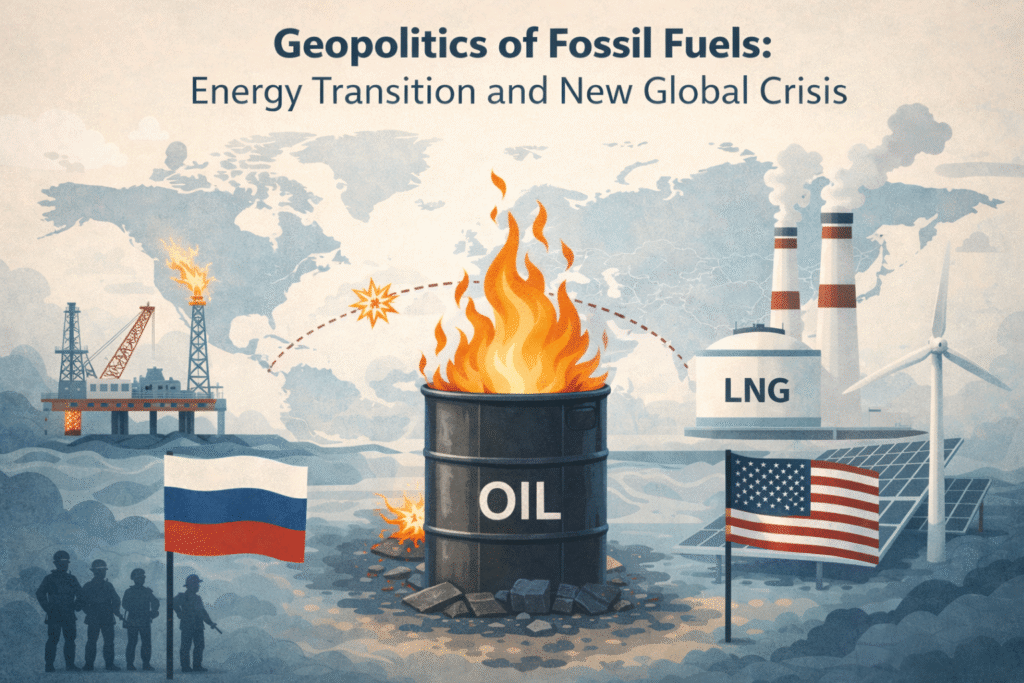
The old energy geopolitics ran on a simple axis: who controls the oil and gas. The new energy geopolitics runs on a much messier axis involving mineral supply chains, manufacturing capacity, and the political stability of countries that sit on deposits of lithium, cobalt, nickel, and rare earth elements. Democratic Republic of Congo produces about seventy percent of the world's cobalt. That's a statistic that should make anyone who thinks the energy transition is a clean breakout uncomfortable. The refining capacity for many of these critical minerals is concentrated in a small number of countries with varying levels of governance quality and human rights records. China has been strategically investing in mining and processing infrastructure in Africa and South America for over a decade and they're now positioned to control the supply chain from mine to battery cell in ways that no single Western company or coalition has been able to replicate. I was part of a supply chain assessment for a battery storage project and we literally could not get a vendor to confirm the origin of the cobalt in their cells without weeks of back-and-forth and third-party certification. The tracing infrastructure for critical minerals is still rudimentary at best and deliberately opaque at worst because the commercial value of ambiguity in this market is significant.
The United States response has been the Inflation Reduction Act, which ties consumer incentives to domestic sourcing and freind-shoring of critical mineral supply chains. The European Union responded with the Critical Raw Materials Act. Both are reasonable policy moves. Neither is going to materially shift the global supply chain geography in the next five years because the infrastructure buildout required just doesn't exist yet and building it takes time that the current market urgency doesn't seem to account for.
Where The Real Vulnerabilities Are
Let me be blunt about the things that keep people up who actually work in this sector. The first vulnerability is the mismatch between where renewable resources are located and where load centers are. The best solar resources in the United States are in the Southwest. The best wind resources are in the Great Plains. The largest load centers are on the coasts. Moving that power requires transmission that doesn't exist at sufficient scale. The second vulnerability is grid inertia and frequency regulation. Traditional synchronous generators provide inherent grid stability because their rotating mass absorbs and releases energy in response to frequency deviations. Inverters-based resources like solar and wind don't provide that same physical inertia and while grid-forming inverter technology is advancing, it's not deployed at the scale needed to replace conventional generation on a system-wide basis. I've seen grid operators in Texas and California quietly maintain standby natural gas capacity specifically because they can't rely on the renewable buildout to provide firm capacity during peak demand events. The third vulnerability is the concentration of manufacturing. If China decides to restrict exports of solar polysilicon or rare earth processing services the way they've restricted gallium and germanium exports in recent years, the rest of the world has limited short-term alternatives. This isn't speculation. It's already happened and the supply shock lasted about eighteen months before prices stabilized at higher levels.
The practical takeaway for anyone tracking this space is to stop watching the headline announcements about new capacity and start watching the interconnection queue data, the permitting timelines, and the commodity supply chain indicators. Those are the real leading indicators of whether the transition is actually accelerating or just looking like it is on paper. I've found that the Interconnection Queue reports from the Electric Reliability Corporation of America give you a much clearer picture of what's actually coming online than any energy ministry press release. The data shows thousands of gigawatts of renewable capacity queued for interconnection but only a fraction of that is expected to reach commercial operation within the next five years due to queue attrition, interconnection study delays, and hardware procurement issues. The gap between queued capacity and delivered capacity is where the actual story lives. There's also a quiet shift happening in dispatchable capacity that deserves attention. Natural gas is serving as a transitional fuel in many markets because it can ramp quickly to balance variable renewable generation. But the same permitting and infrastructure constraints that slow down renewable projects also slow down pipeline and LNG export terminal development. I've seen gas-fired peaker plants that were approved three years ago still waiting on compressor station permits because local communities filed injunctions based on air quality concerns. The same community that supports clean energy will oppose a natural gas facility nearby even if that facility is what keeps their lights on when the sun isn't shining and the wind isn't blowing.

The energy transition is real. The economics are sound. The technology works. The deployment is slower and more politically fraught than the narrative suggests and the geopolitical implications are still being written in real time by people making decisions that most of the public will never see. That's the accurate state of things without the noise.