How the Duval County Property Appraiser Actually Works
The Duval County Property Appraiser office handles roughly 280,000 parcels. That includes residential homes, vacant land, commercial buildings, and everything in between. The person sitting at the desk doesn't drive by your house. They look at sale data, prior assessments, and computer models. Most homeowners never meet them. I've been watching property assessments in Northeast Florida since around 2014. I've filed appeals, tracked changes year over year, and read through the raw data myself. The system isn't perfect. It has real quirks that trip people up if you don't know where to look.
What You Need To Know About Duval County Property Appraiser Facts Process And Impact On Homeowners
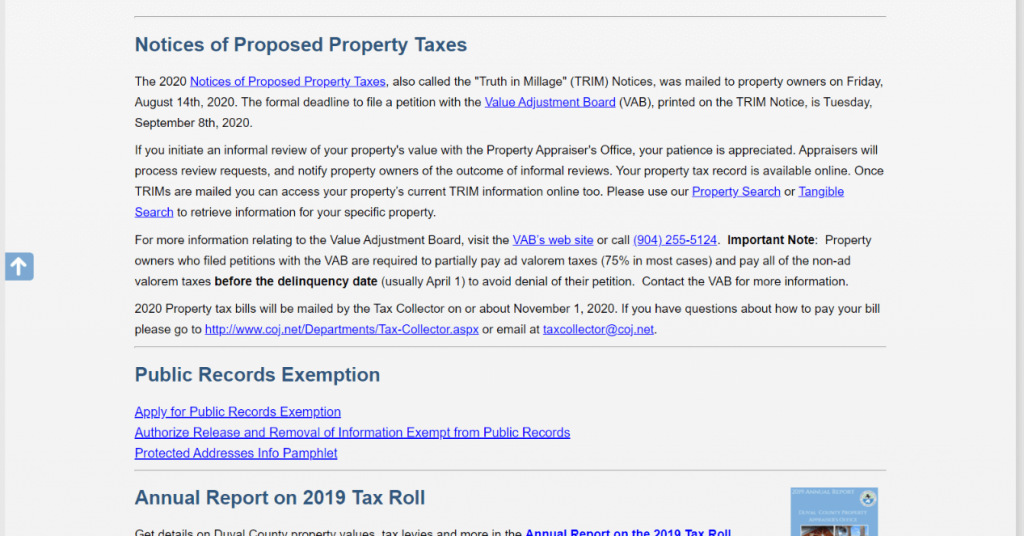
Here's the straightforward part. The Property Appraiser determines market value for every parcel once a year. That number becomes your assessed value. The tax authority then applies millage rates to it. So the appraisal itself doesn't set your taxes, but it's the foundation everything else builds on. If the appraisal jumps, your tax bill usually follows. The official process starts with a notice mailed in the fall. That notice shows your proposed value for the upcoming tax year. You have a window, usually around 30 days, to respond. You can accept it, or you can appeal. If you appeal, you get a meeting with the Value Adjustment Board. The board meets quarterly. January, April, July, and October sessions handle different types of objections. January is for everyone. April and October are typically for agricultural exemptions and special cases. July handles mid-year changes from new construction or damage.
My first real experience with this came in 2017. A neighbor sold his house for a price that seemed high compared to nearby properties. The appraiser used that sale as a comparable and bumped my value up by nearly twelve thousand dollars. I pushed back by pulling three sales from my own street that were clearly lower. The board agreed and reduced my assessment back down. The lesson was simple: sale data matters more than any model they run. That brings me to something most homeowners miss. The appraiser uses mass appraisal techniques. That means they build statistical models for neighborhoods, not individual inspections for every house. They adjust for square footage, age, condition, and lot size based on aggregates. It works well for median values. It struggles at the edges. If your home is unusual in your area, the model probably doesn't capture it accurately. I ran into this myself with a property that had a finished basement unlike anything on the block. The model treated it as unfinished space. My assessment was roughly fifteen percent below what it should have been based on the improvement. It took two years and a specific appeal form to get them to recognize the square footage classification. You have to be the one to flag it. Nobody does it automatically.
Get the Full Details

Here's another counter-intuitive point. A lower assessment isn't always better for you long term. If your neighbor's house sells for a lot and yours doesn't, your relative share of the tax burden goes up. The appraiser zeroes in on fair market value, not your personal circumstances. Your income, your mortgage rate, how long you've lived there. None of that factors in. It's purely about what the property would sell for as of January first of the tax year. The online search tool is probably the most useful resource they offer. You can pull up any parcel and see its current value, prior values going back several years, and the breakdown of land versus improvements. I use it to track trends before filing anything. If your value jumped sharply while nearby parcels didn't, that's a signal to investigate. If everyone's went up uniformly, it's probably just the market moving. One detail that trips people up: the January first valuation date. Your home could be completely renovated in February and your assessment won't reflect that until the following year. Conversely, if something damages your property before January first, that drop in value gets captured immediately. Timing matters more than most homeowners realize.
When you decide to appeal, start with the evidence, not the emotion. Saying your taxes are too high won't work. You need to show the appraiser's value doesn't align with actual market data. Comparable sales are the standard approach. You want recent sales within the same neighborhood, similar square footage, similar age and condition. Ideally three to five comps. Close the gap on condition differences with notes, not guesses. Another thing that works better than people expect: checking the property record card for errors. Square footage mistakes, incorrect bedroom counts, wrong year built, unfinished space classified as finished. These sound small but they move the needle. I've had cases where a single room was listed twice, inflating the value by eight percent. Correcting the record card alone dropped the assessment without even getting to a hearing. The Value Adjustment Board hearing is informal. There's no lawyer required. You present your case, the appraiser's representative presents theirs, and the board votes. Most appeals get resolved at this level. A significant portion settle before the hearing through informal conferences with the appraiser's office. That's often the fastest path. You email or call, send your comps, and they may adjust without a formal appearance.
There are limitations worth being blunt about. The process favors people who invest time. If you're working two jobs and can't pull comparable sales or drive around checking conditions, you're at a disadvantage. Professional consultants exist but they cost money, usually a percentage of your savings or a flat fee of several hundred dollars. For a modest assessment reduction, it might not be worth it. Another reality: appeal success varies widely by year. In markets where values are rising fast, like we've seen in Jacksonville over the last few years, the appraiser's numbers tend to track closer to actual sales. That makes appeals harder because the data supports their position. In flat or declining markets, you have more room to challenge because the model lags behind. The impact on homeowners isn't just about the tax bill. Assessment changes affect refinancing, insurance estimates, and sometimes school district boundaries indirectly through how values cluster. A sudden jump can also signal to your insurer that your replacement cost has changed, which can nudge premiums even if the policy itself didn't change.

If you want to stay on top of this without getting caught off guard, set a calendar reminder for November each year. Pull your notice. Compare it to the prior year. Look at your street or immediate neighborhood on the appraiser's site. If something looks off, start gathering data early. Don't wait until the appeal deadline is three days away. A few specific resources worth knowing about. The Duval County Property Appraiser maintains an online parcel search at their official website. The Value Adjustment Board schedules are published publicly. Their office can provide a copy of your property record card if you request it. None of this requires a lawyer or a consultant. The information is there if you look for it. Bottom line: the system is designed to be transparent on paper but it rewards people who put in the work. Understanding the timeline, knowing where to find data, and building a factual case will serve you better than hoping for an automatic correction. Most errors get fixed only when someone points them out.