IRA basics without the brochure language
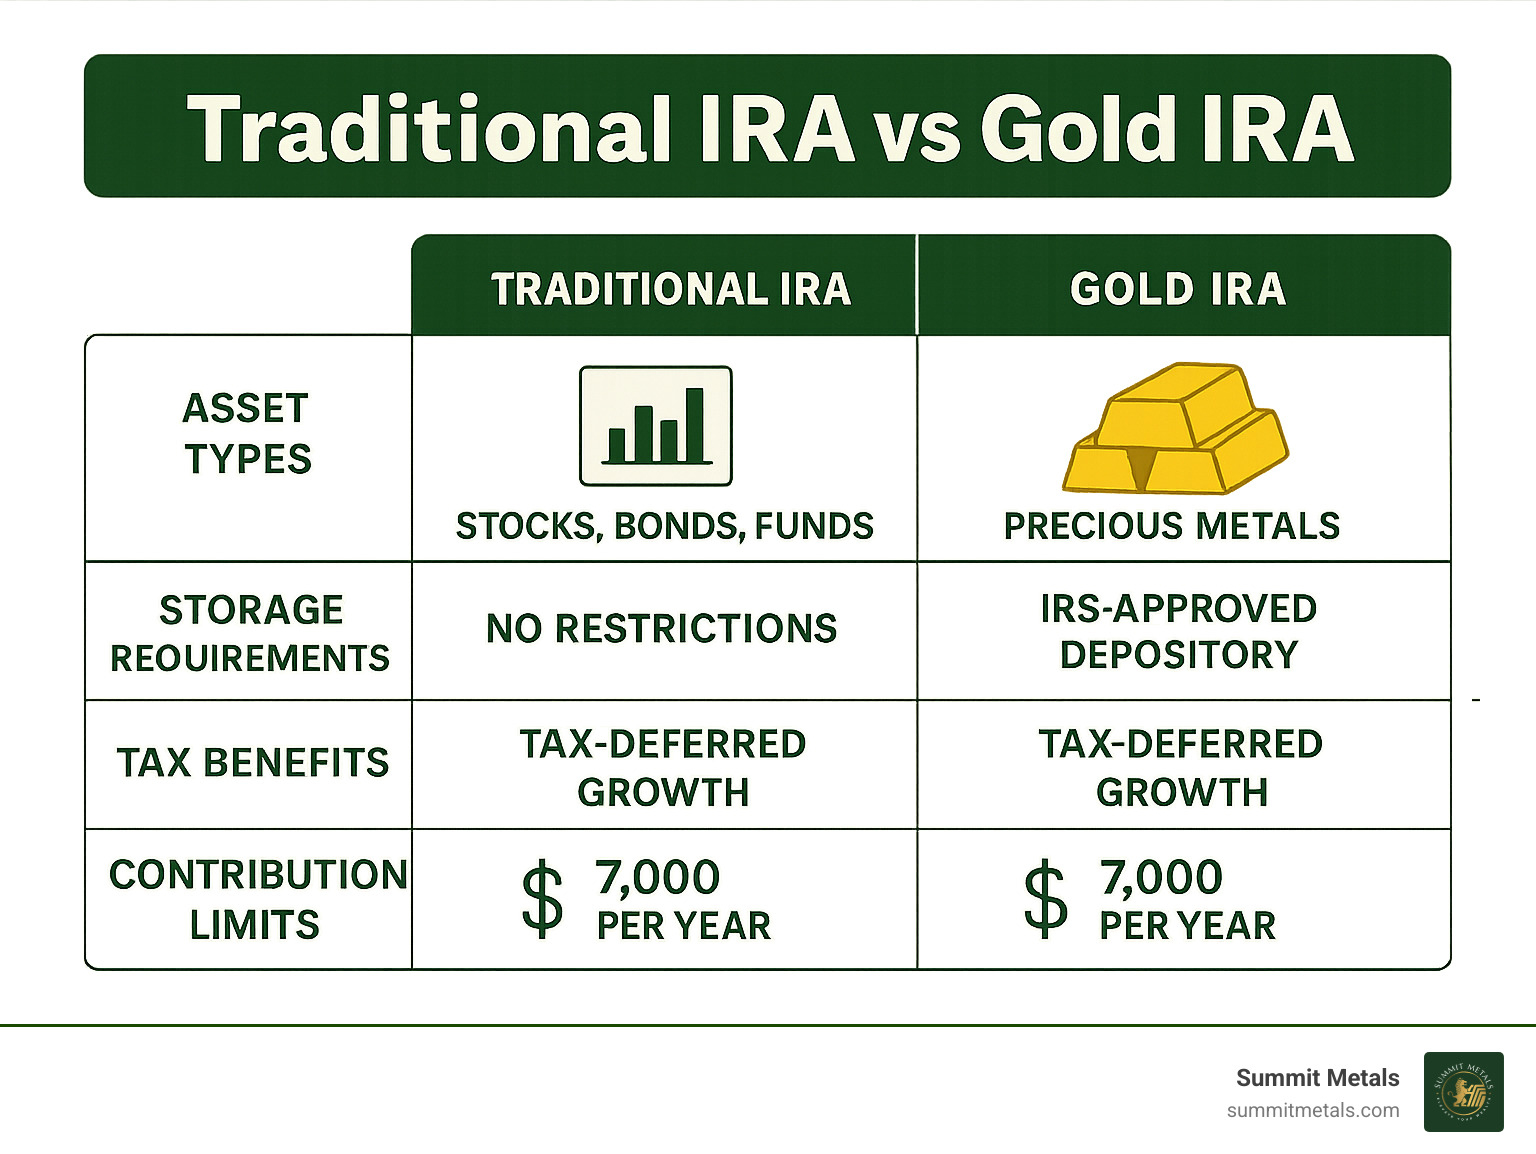
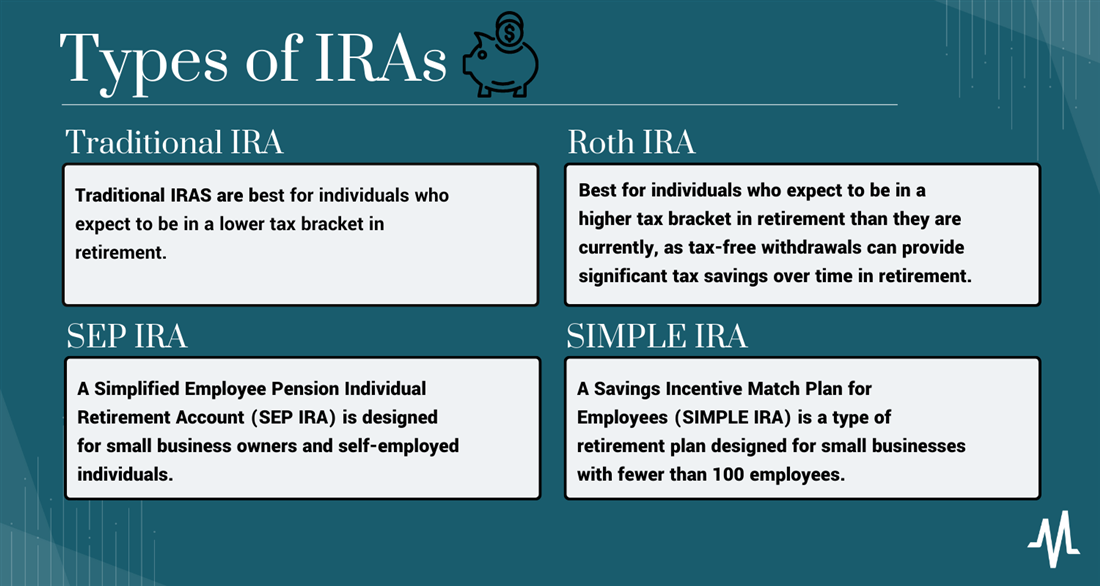
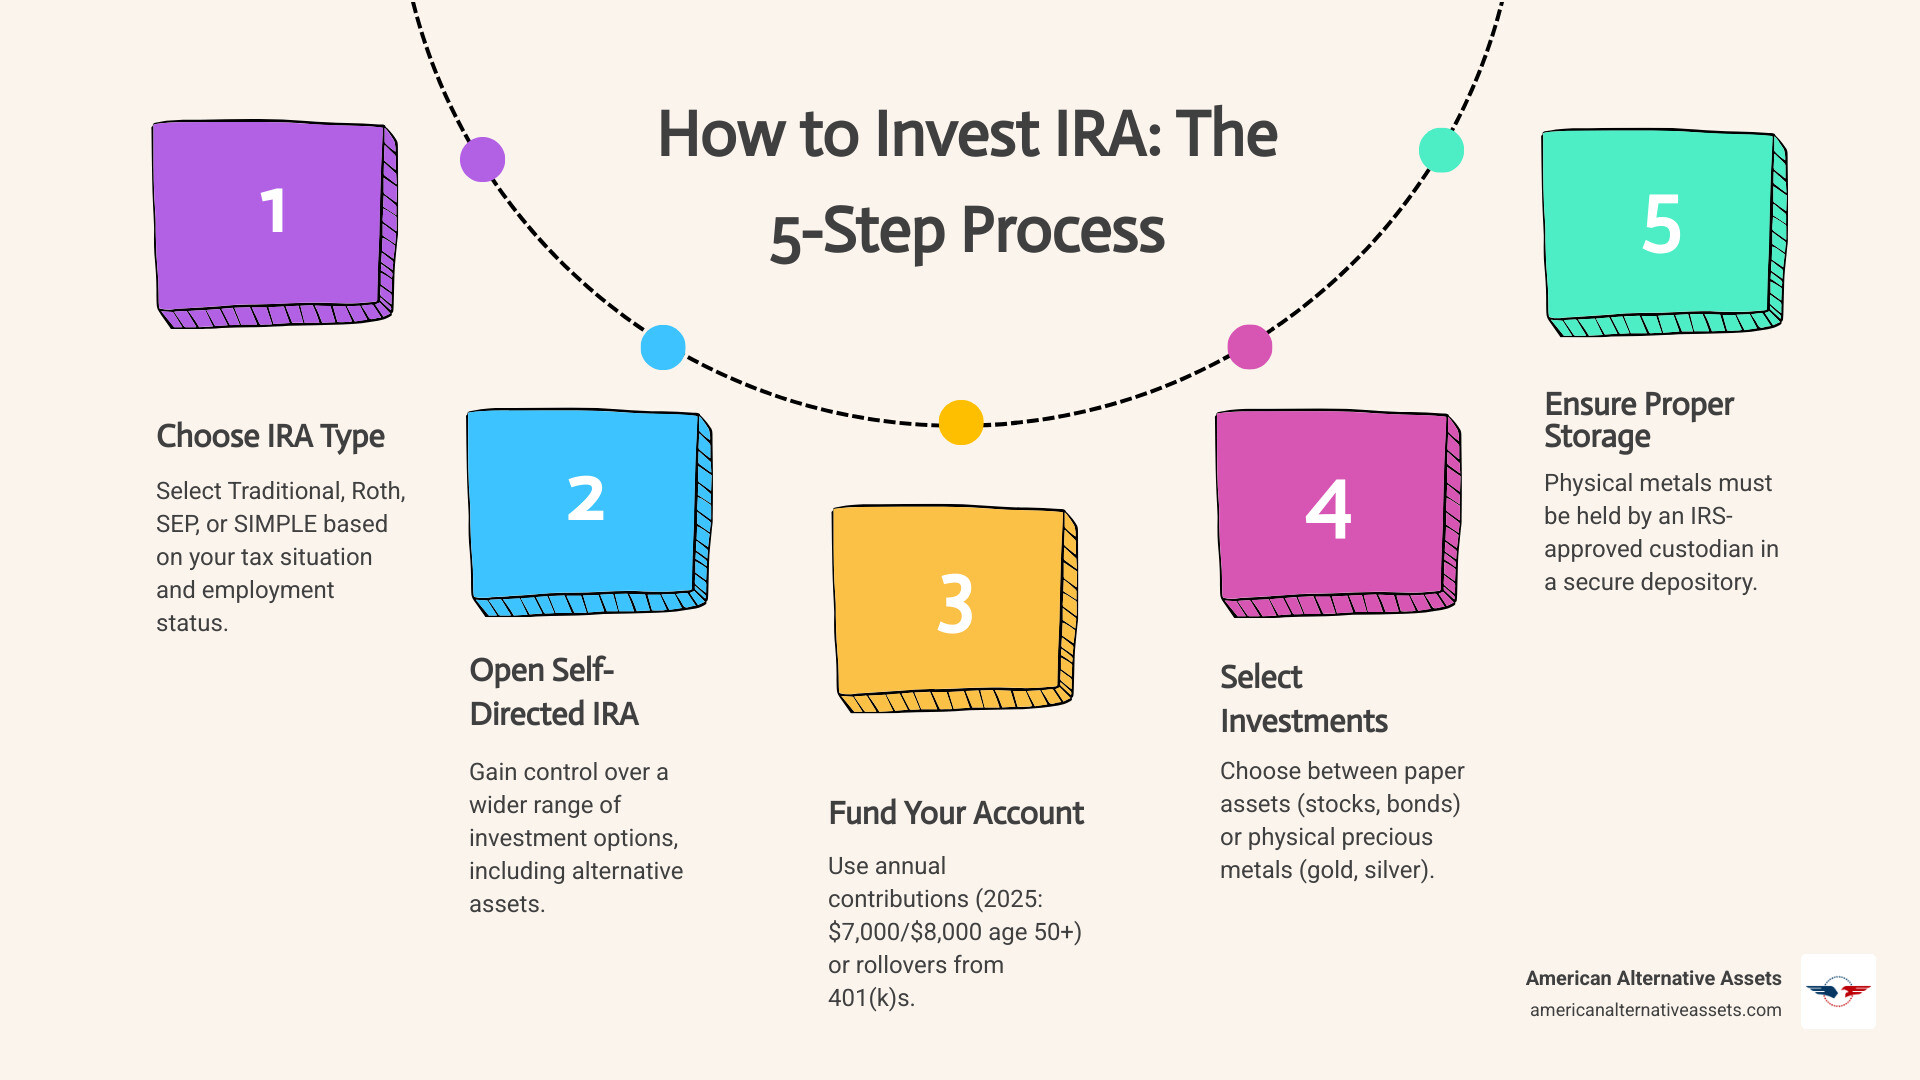
An IRA is a tax-advantaged retirement account you open yourself, separate from any employer plan. That distinction matters because it changes who sets the contribution limits, which are the same whether you have a 401(k) or not. You pick a financial institution, fund it, and choose investments. The government doesn't select anything for you. The catch is that the IRS decides the rules, not the bank. The two types you'll encounter constantly are Traditional and Roth. A Traditional IRA lets you deduct contributions in many cases, which lowers your current taxable income, and your money grows untaxed until withdrawal. Withdrawals in retirement are taxed as ordinary income. A Roth IRA uses after-tax dollars, so there's no upfront deduction, but qualified withdrawals in retirement are completely tax-free. Both have annual contribution limits that adjust periodically. For 2024, the base limit is $7,000, or $8,000 if you're 50 or older. These numbers shift, so check the current year before you fund anything.
What Is The Ira Understanding The Basics And How It Shapes Your Financial Future
Understanding the mechanics is straightforward. Choosing which one to use is where most people get tangled up, and not always for the reasons they expect. Here's the practical framework I use when advising people who are actually trying to make a decision instead of reading a summary page. Start with your marginal tax rate now versus the rate you expect in retirement. If your current rate is higher than your expected retirement rate, a Traditional IRA generally saves you money on taxes. If your current rate is lower or roughly equal to what you think you'll pay later, Roth usually makes more sense. This is the textbook answer, and it's also where it starts to fall apart in real life. The tax rate you face in retirement isn't just your current bracket flipped forward. It depends on how your other income sources stack up. Social Security benefits can become partially taxable depending on your provisional income. Required minimum distributions from Traditional IRAs and 401(k)s add forced income that can push you into a higher bracket whether you need the money or not. A Roth IRA sidesteps RMDs entirely during your lifetime, which is a structural advantage most people don't factor in when they're doing the simple now-vs-later calculation. That alone can justify a Roth even when your current bracket is slightly higher than your projected retirement bracket, because it gives you flexibility to manage taxable income year by year instead of being forced into withdrawals at whatever rate the IRS picks for you.
I hit a specific edge case a few years ago that illustrates why the basic model doesn't always cover it. A client was in a moderately high tax bracket during peak earning years and had maxed out his 401(k). He was leaning toward a Traditional IRA because it lowered his taxable income that year. But his employer also offered a deferred compensation plan, which meant a significant chunk of income was already being pushed into future years and would show up on his tax return regardless of whether he contributed to an IRA. Adding a Traditional IRA contribution on top of that would have created a situation where his deductions were partially phased out due to the income-based AGI limits for IRA deductions when you're covered by a workplace retirement plan. Instead of losing the deduction entirely, which the phase-out rules would have done at his income level, I switched him to a Roth IRA contribution. The tax savings weren't immediate, but he kept the full benefit of his 401(k) deferral, avoided the deduction phase-out headache, and locked in tax-free growth at a known current rate rather than gambling on what his tax situation would look like decades later. It wasn't a dramatic move, but it fixed a problem that wouldn't have shown up on a standard contribution calculator. There are other nuances that aren't in the fact sheets. Backdoor Roth contributions exist for a reason. If your income exceeds the direct Roth IRA contribution limits, you can contribute to a Traditional IRA with nondeductible dollars and then convert it to a Roth. The trick is the pro-rata rule. If you already have pre-tax money sitting in an existing Traditional IRA, the conversion isn't as clean as it sounds. The IRS treats all your Traditional IRA balances as one aggregate account when calculating the taxable portion of a conversion. So someone with $50,000 in an old rollover IRA and $6,000 in a new nondeductible contribution wouldn't convert just the $6,000 tax-free. They'd convert a proportional mix based on the total balance, and the pre-tax portion would trigger a tax event. The workaround is to roll any pre-tax IRA funds into an employer-sponsored 401(k) plan if it accepts rollovers, which isolates the backdoor Roth contribution in a clean Traditional IRA and makes the conversion fully tax-free. Not all 401(k) plans accept rollovers, so you have to check with your plan administrator before attempting this. SEP IRAs and SIMPLE IRAs are different animal entirely. A SEP IRA is designed for self-employed individuals and small business owners. Contributions are made by the employer, not the employee, and the limits are dramatically higher than a standard IRA. For 2024, you can contribute up to 25% of compensation or $69,000, whichever is less. A SIMPLE IRA is for small employers with up to 100 employees. Employees can contribute $16,500 in 2024, or $19,500 if 50 or older, and the employer must either match up to 3% of compensation or make a 2% non-elective contribution to all eligible employees. These aren't personal choice accounts the way a regular IRA is. They're employer-sponsored structures with their own rules and contribution timelines.
Get the Full Details

Contributions for a given tax year generally need to be made by the tax filing deadline, including extensions. That means April 15th of the following year for most people, or October 15th if you file for an extension. You can't contribute retroactively past that deadline. If you miss it, you've lost that year's tax advantage and will need to request a return of the contribution plus any earnings it generated, which itself creates a taxable event. Withdrawal penalties are another area where people assume they understand the rules and then get surprised. Traditional IRA withdrawals before age 59½ typically incur a 10% early withdrawal penalty on top of ordinary income tax. There are exceptions. First-time home purchases up to $10,000, qualified education expenses, certain medical costs exceeding 7.5% of adjusted gross income, and disability are common exemptions. Roth IRAs have a different withdrawal order. Contributions can be withdrawn at any time, for any reason, tax-free and penalty-free, because you already paid taxes on that money. Earnings, however, are subject to the same rules as Traditional IRA withdrawals. The ordering matters when you're in a situation where you need partial access. You pull contributions first, then earnings, and only the earnings trigger penalties and taxes if you're under 59½ and don't qualify for an exception. Here's what most guides don't emphasize enough: an IRA is not a standalone strategy. It works best when you think about it as part of a layered approach. Maximize any employer match in your 401(k) first because that's free money with an immediate return. Then decide between Traditional and Roth IRA contributions based on your current tax situation and long-term outlook. If you're self-employed, run the numbers on whether a SEP IRA or Solo 401(k) makes more sense given your income and withdrawal timeline. And if you have both a Traditional IRA and a Roth IRA, the tax implications of switching between them over time are worth modeling, because converting from Traditional to Roth later in life can create a sudden spike in taxable income that might push you into a higher bracket for that year.
The limitations are real. IRAs don't protect you from market downturns. They're just containers. If you put everything in a single stock or a poorly performing fund, you'll lose money regardless of the tax treatment. They also don't eliminate the risk of outliving your savings. A Roth IRA with a large balance still runs out if you withdraw too much too fast or don't adjust your asset allocation as you age. Some people treat an IRA as a savings account substitute and wonder why their retirement projections don't match their actual returns. The account structure doesn't guarantee outcomes. It only changes the tax timing. If you're going to use one, open it with a low-cost provider. Fidelity, Vanguard, and Schwab all offer IRA accounts with zero-fee index fund options and no account maintenance charges. The difference in fees between a provider charging 0.05% and one charging 1.5% compounds into a meaningful gap over 30 years. Don't let a bank upsell you into managed accounts with high expense ratios inside your IRA. The account type is designed to minimize tax drag; don't add fee drag on top of it. The mechanics are simple. The strategy is where people trip. Figure out your current versus future tax bracket, understand how the pro-rata rule affects conversions, know which withdrawal exceptions apply to your situation, and don't treat the IRA as an investment decision in itself. It's a tax wrapper. What goes inside it is what actually determines whether it shaped your financial future the way you intended.