The Swiss Franc and Its Relatives
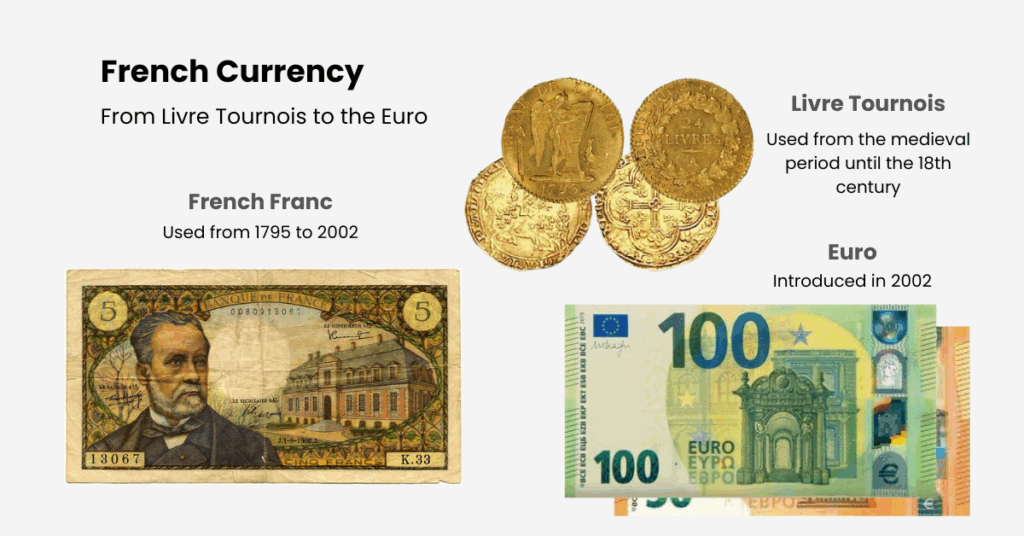
The franc is one of those currencies you hear about constantly but barely understand how it actually works. There are at least eight different franc-denominated currencies still in circulation today, each with separate central banks, separate monetary policies, and separate histories that don't always line up the way people assume they do. If you're trying to figure out what Is The Franc Currency Understanding The History Types And Use Of Francrelated Currencies then you need to stop treating them as interchangeable and start looking at the actual mechanics. The original French franc was introduced in 1795 to replace a chaotic mix of regional currencies after the Revolution. The Swiss franc followed in 1850 when Switzerland standardized its cantonal monies. The key detail most people miss is that the Swiss government didn't create a single national currency by decree. It negotiated the transition with cantons that had been minting their own coins for centuries, and the compromise structure that emerged still affects how the Swiss National Bank operates today. The franc name spread from French colonial expansion into Africa, where former colonies kept the currency name but issued their own versions with different pegs and different central bank mandates. Here's what actually matters for anyone dealing with these currencies. The Swiss franc (CHF) trades as a standalone currency with a floating exchange rate. The Belgian franc (BEF) was replaced by the euro in 2002 and is now a historical currency. The French franc (FRF) also disappeared into the euro in 2002. The West African CFA franc (XOF) and Central African CFA franc (XAF) are two separate currencies that share the same name and the same peg to the euro, but they are issued by different central banks and are not freely convertible between each other. The Comorian franc (KMF), Djiboutian franc (DJF), and Congolese franc (CDF) each operate independently with their own peg arrangements or floating rates. That's eight currencies, not one.
I spent three years handling treasury operations for a logistics company that moved goods through West and Central Africa. One of my first mistakes was assuming the CFA francs used in Senegal could be exchanged at parity with the CFA francs used in Cameroon. They share the same abbreviation family but the exchange required converting through euros first because the two monetary zones don't have a direct clearing arrangement. I lost roughly fourteen hundred dollars on that error in a single quarter before we restructured our payment routing through dedicated correspondent banks in Paris. The workaround was straightforward once I understood the structure. We opened separate accounts with Banque Centrale des États de l'Afrique de l'Ouest and Banque des États de l'Afrique Centrale, and let each account settle in its own zone. It added about twenty minutes of processing time per transaction but eliminated the cross-zone conversion losses entirely.
How The Major Franc Currencies Actually Work
The Swiss franc remains the most liquid and widely traded of all franc currencies. It's classified as a safe-haven currency by most institutional desks, which means it tends to appreciate during periods of global market stress. The Swiss National Bank intervened heavily in 2011 to prevent the franc from appreciating beyond 1.20 against the euro, then removed the floor unexpectedly in January 2015, causing the currency to spike nearly thirty percent in a single trading session. That event wiped out billions in leveraged positions overnight and remains one of the most discussed episodes in modern FX history. If you're holding CHF positions, you need to understand that the SNB still holds significant foreign reserve assets and still intervenes when it sees fit, even though the explicit floor is gone. The CFA franc zones operate under a different set of constraints. Both the XOF and XAF are pegged to the euro at a fixed rate of 655.957 CFA francs per euro, a rate that has been maintained since the peg was established to the French franc in 1948 and continued after France adopted the euro in 1999. The peg is backed by a Treasury deposit account held by France that contains roughly thirty-five percent of each zone's foreign reserves. This arrangement guarantees convertibility but it also means that monetary policy for both zones is effectively dictated by the European Central Bank's decisions rather than by local economic conditions. Member states cannot devalue their currency independently. They cannot print money to finance deficits. The constraint is real and it has been the subject of ongoing political debate in both West and Central Africa for decades. The Congolese franc (CDF) is a completely different case. It floats, it has experienced severe depreciation, and it carries substantial country risk. The DRC has gone through multiple currency redenominations and the black market premium over the official rate has at times exceeded forty percent. Trading CDF requires understanding that the official rate published by the Banque Centrale du Congo is not the rate you will actually get outside major banks in Kinshasa. I learned this the hard way when a supplier in Lubumbashi quoted prices in USD but demanded payment in CDF at a rate that was roughly twenty percent worse than the interbank midpoint. The fix was simple. I started contracting in USD with a clear clause specifying the exact exchange rate basis, and the disputes stopped immediately.
Get the Full Details
Practical Use Cases and Where People Go Wrong
Most people encounter the franc through travel or basic remittances. Switzerland is expensive and the franc is strong, which means visitors from eurozone countries often underestimate how far their money actually goes. A meal that costs twelve euros in Paris will cost roughly fifteen to sixteen Swiss francs in Zurich for the same quality level. The price difference isn't just inflation. It's structural, driven by Swiss wage levels, high operating costs, and a currency that retains its safe-haven premium. For businesses, the practical question is whether to hold CHF as a reserve currency. The answer depends on your exposure. If you have revenue streams in Switzerland or with Swiss counterparties, hedging with forwards or options is standard practice. The Swiss options market is deep enough that even medium-sized corporates can get reasonable pricing on six-to-twelve-month tenors. If you have no Swiss exposure, holding CHF as a diversification move makes sense only if you understand the carry trade implications. The interest rate differential between Switzerland and most other major economies has been negative or near-zero for extended periods, which means holding CHF generically without a directional thesis is a drag on returns. You pay for the safety. The CFA franc is often misunderstood in investment circles. Some analysts treat it as a stable currency because of the euro peg, but stability on paper doesn't translate to stability in practice when you're dealing with the underlying economies. Benin, Côte d'Ivoire, Senegal, and the other WAEMU member states have growth trajectories that don't always align with European monetary policy. When the ECB raises rates, the CFA zone raises rates too, regardless of whether local inflation or unemployment justifies that move. This mismatch creates periodic capital flow disruptions that the peg absorbs poorly. I've seen CFA franc liquidity tighten noticeably during ECB hiking cycles, even though the official exchange rate never moved. The problem shows up in settlement delays and wider bid-ask spreads at local correspondent banks, not in the published rate.
If you're handling franc currencies for any sustained period, the single most useful thing you can do is track the SNB balance sheet for CHF exposure, monitor the French Treasury deposit balance for CFA zone confidence, and watch the black market premium for floating francs like the CDF. None of these indicators appear on a standard Bloomberg terminal screen. They require going to the source data directly. The SNB publishes weekly reserve and balance sheet figures. The French Ministry of Economy publishes monthly CFA Treasury account balances. Black market premiums for the Congolese franc are tracked by local financial newsletters and can be approximated by comparing official rate quotes with parallel market quotes from recognized brokers in the DRC. The franc family isn't a single currency. It's a collection of independent monetary systems that happen to share a name inherited from French economic history. Treating them as identical is the most common mistake I see, and it's a mistake that costs people real money every year. The Swiss franc operates on market forces with occasional intervention. The CFA francs operate on a rigid peg with French backing. The Congolese and Comorian francs float with varying degrees of instability. Knowing which bucket your exposure falls into determines everything about how you manage it.