The Basics You Already Know
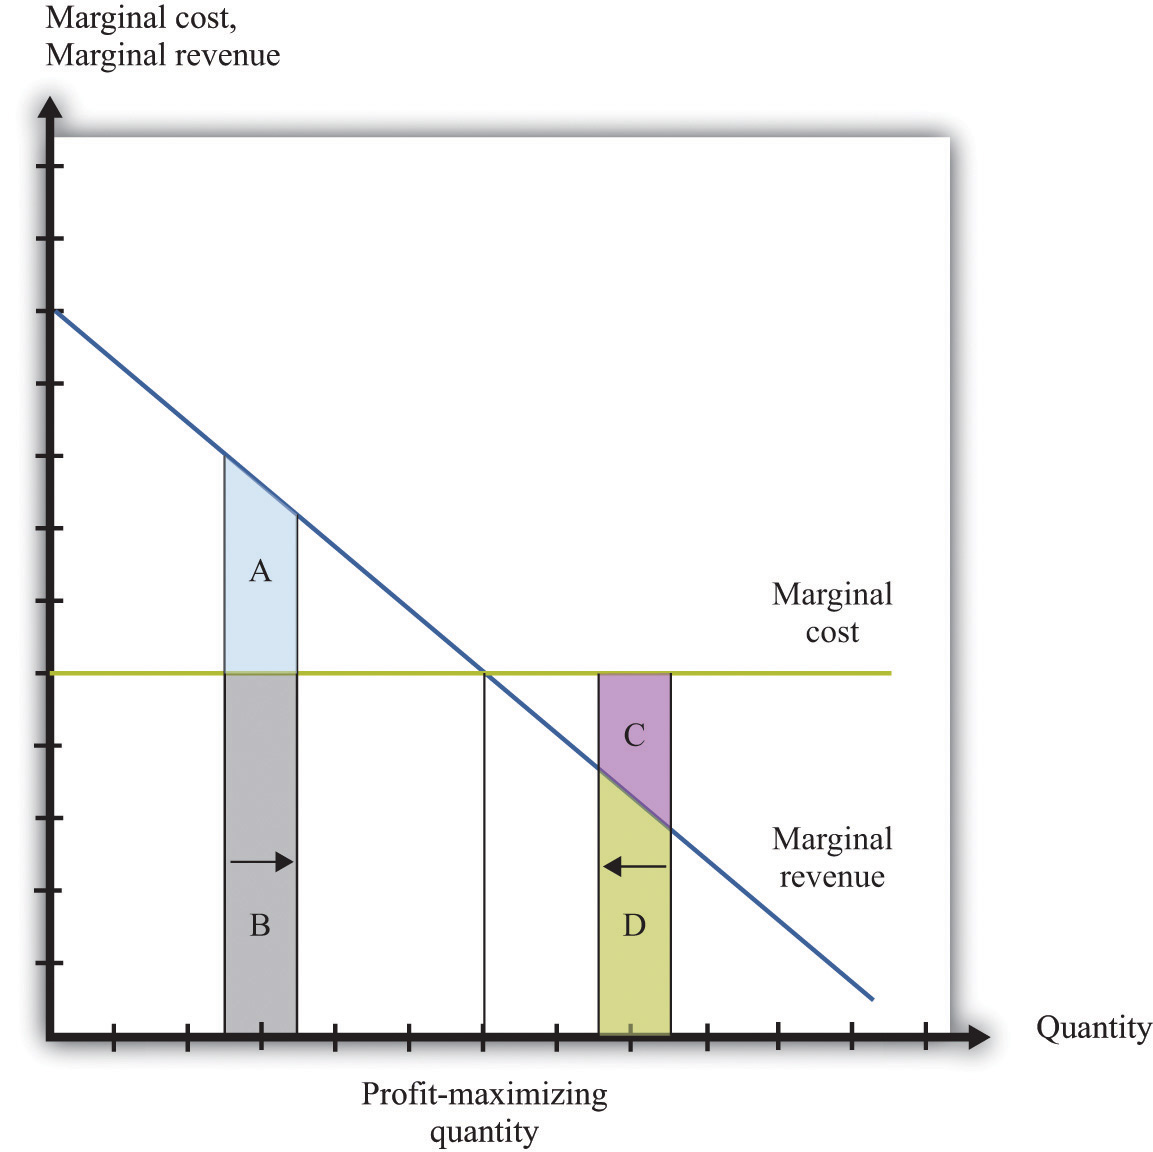
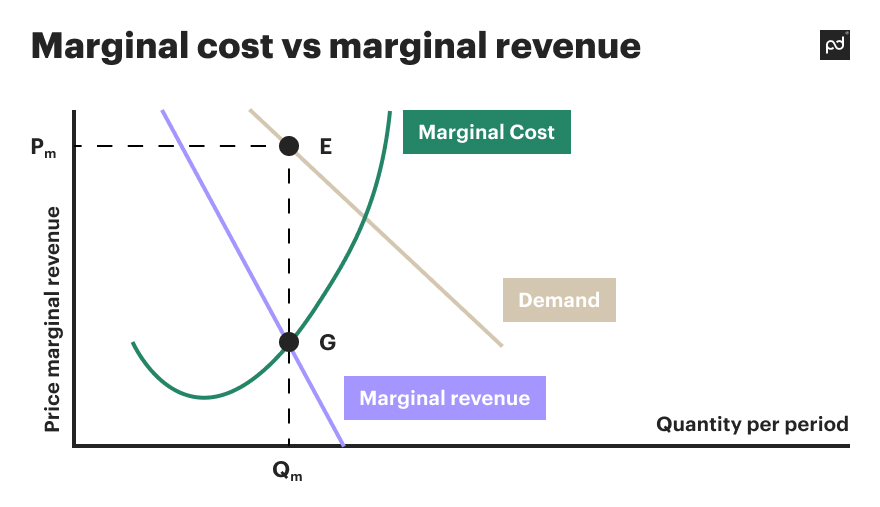
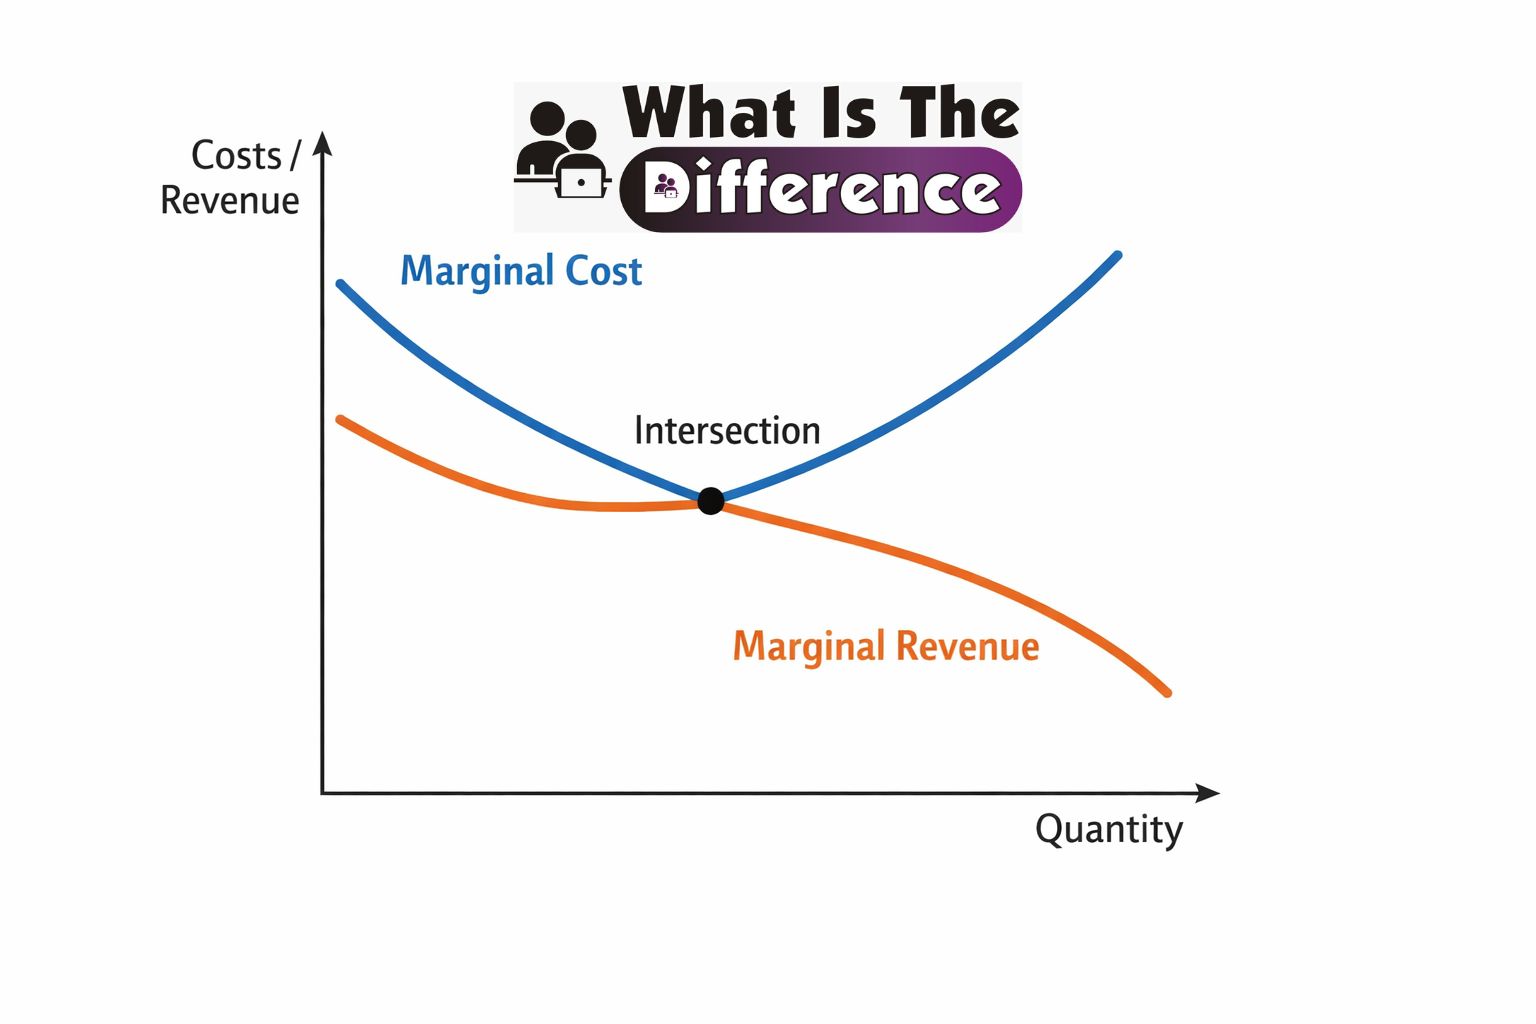
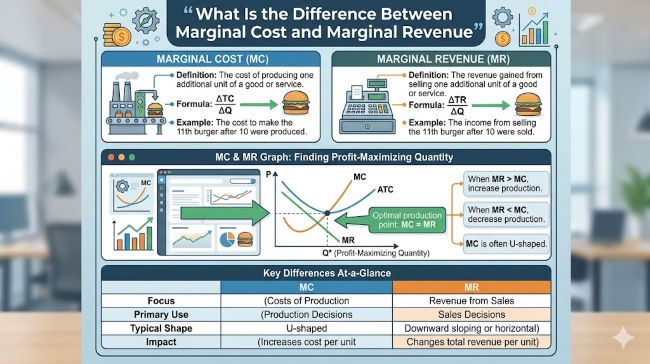
MC is what it costs to produce one additional unit. MR is what you earn from selling that one additional unit. Profit maximization happens where MC equals MR. That part is standard microeconomics 101. But the real question most people are actually asking is less about the textbook definition and more about how these concepts behave when you're running a business with messy, unpredictable data. Decoding profit maximization means working backward from your actual numbers to find the output level where the gap between what you earn and what you spend stops widening. You're looking for that single production quantity where producing one more unit would cost you more than the revenue it brings in. Before that point, you should keep producing. After it, you should stop. I worked through this for a small manufacturer last year. They made industrial seals and gaskets. Their marginal cost curve wasn't smooth — it stepped up dramatically at certain batch sizes because they had to run a second shift to meet demand. The MR curve was declining because their main buyer, a mid-size HVAC distributor, negotiated volume discounts that cut into per-unit revenue as order sizes grew. The textbook answer would have been to set MC equal to MR on paper. What actually worked was mapping out their real cost data by batch and their real pricing tiers by volume, then finding the intersection point in the actual data rather than trying to force a continuous curve through discrete jumps.
The difference between MC and MR isn't just conceptual. It shows up in how you model your business. MC tends to be jagged — labor, materials, equipment wear, capacity constraints. MR is usually smoother but can have its own discontinuities when pricing tiers, promotional periods, or contract renegotiations kick in. When both curves have jumps, the equal-MC-and-MR rule still applies, but you have to check every jump point individually instead of relying on calculus-based optimization. A few things people miss when they first tackle this. One is that marginal cost isn't the same as average total cost. Beginners sometimes divide total cost by quantity and use that as MC, which gives you the wrong answer when fixed costs are involved or when variable costs aren't linear. MC is specifically the change in total cost divided by the change in quantity for that one additional unit. If going from 100 to 101 units increases your total cost by $12, your MC is $12, not your average cost per unit across all 100 units. Another thing: MR isn't always equal to price. If you're selling in a competitive market where you take the market price as given, then yes, MR equals price for each additional unit. But if you have any pricing power — which most businesses do to some degree — selling one more unit requires lowering the price on all units, not just the marginal one. That means MR falls faster than price. For a simple linear demand curve P = a - bQ, MR = a - 2bQ. The slope of the MR curve is twice the slope of the demand curve. This matters because it shifts your profit-maximizing quantity lower than you'd calculate if you mistakenly treated MR as price.
Here's a practical scenario I ran into that doesn't get covered in textbooks. You have a product where the marginal cost of producing one more unit is below the marginal revenue, so mathematically you should produce it. But producing that unit requires running a machine that degrades faster under high utilization. The replacement cost of that machine isn't captured in your per-unit MC calculation. I've seen businesses miss this and overproduce until their equipment failure rate spiked, turning a seemingly profitable marginal unit into a net loss once replacement costs were factored in. The workaround is to include depreciation and maintenance as marginal costs, not just as fixed overhead spread across all units. When you're actually computing this, here's the order that tends to work. Gather your cost data by output level. Calculate the change in total cost between each level and the one before it — that's your MC. Gather your revenue data by output level, accounting for any price changes needed to sell additional units. Calculate the change in total revenue — that's your MR. Find where MC first exceeds MR. Your profit-maximizing quantity is the level just before that crossover. Run a sanity check by calculating total profit at that quantity and at the two quantities around it to make sure you haven't missed a local maximum caused by discrete jumps in your data. The approach breaks down in a few situations. If your cost or revenue data is too noisy — say you're working with monthly aggregates instead of per-unit tracking — the marginal calculations become unreliable. I've seen people get MC and MR estimates that swing wildly from one period to the next simply because of random variation in their data, not because of actual changes in their cost or demand structure. In those cases, smoothing the data with a moving average or fitting a curve to the data points first gives you more usable marginal estimates, though it introduces its own assumptions about the shape of your cost and revenue functions.
Get the Full Details
Another situation where this framework fails is when you have multiple products sharing capacity. The marginal cost of producing one more unit of product A depends on whether that unit displaces production of product B. The simple MC = MR rule assumes a single product or independent products. With shared constraints, you need to think in terms of marginal contribution per constrained resource unit, which is a different calculation entirely. Linear programming handles that better than basic marginal analysis. If you're dealing with this in practice, the most useful thing you can do is track your actual per-unit costs and revenues at a granular level. Monthly or quarterly aggregates obscure the marginal relationships you're trying to find. Daily or weekly production and sales records give you enough resolution to see where MC and MR actually intersect without needing to fit idealized curves through sparse data points.