The Six-Figure Threshold and Why It Feels Different Than You Expect
Most people hear "six figures" and immediately picture financial freedom. The reality is much more mundane and depends entirely on where you live, what your expenses look like, and how you define the line between stability and wealth. I made $102,000 my first year out of grad school. I felt broke. My rent was $2,400 a month in a city where that's a studio apartment, student loans ate $900, and "six figures" didn't feel like anything other than a number that looked impressive on a business card.
What Is Six Figures Defining The Income Milestone Between Stability And Wealth
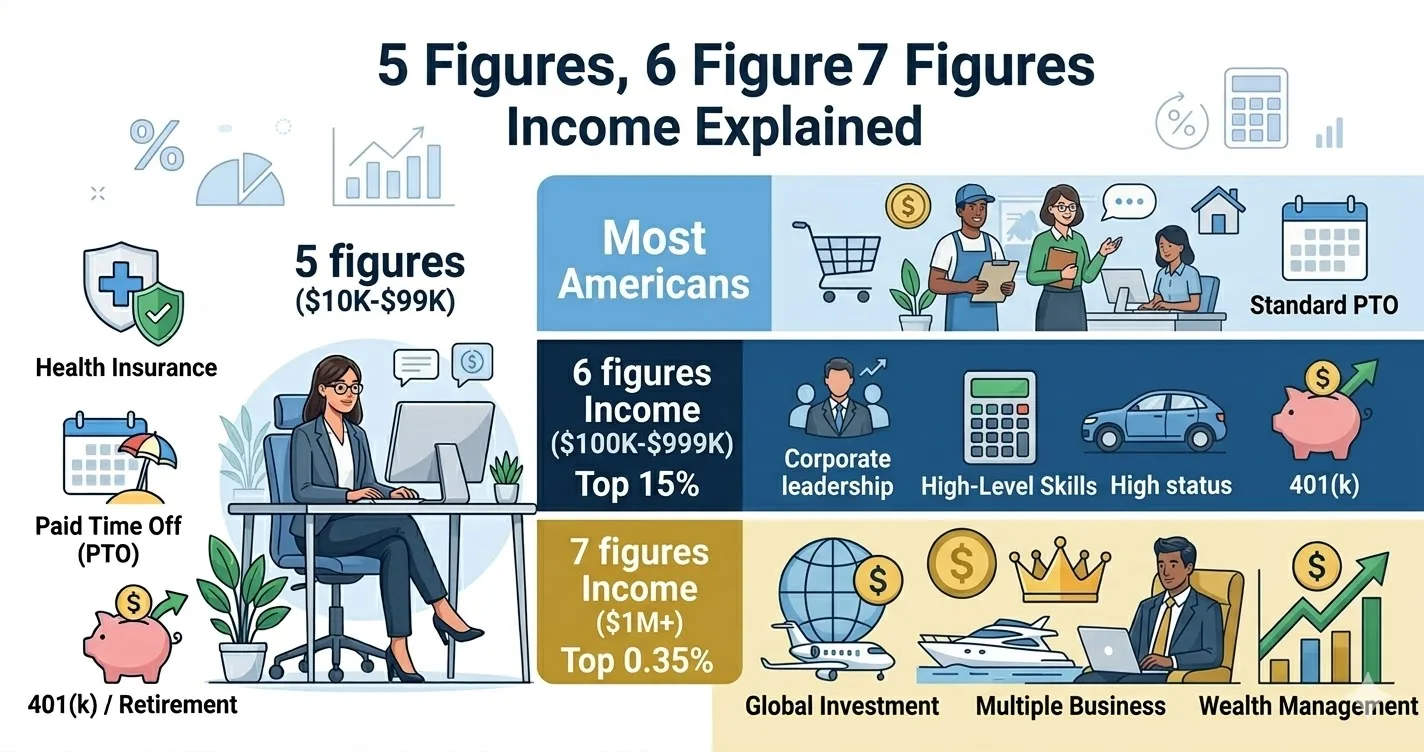
The term "six figures" literally means any income between $100,000 and $999,999. That's the numerical definition. The social and financial definition is far messier. In most of the United States, $100,000 in household income places you roughly in the top 15 to 20 percent of earners. You're doing better than the median. But you are not wealthy. You are stable if your cost of living is managed. Stability at six figures means your essential expenses—housing, food, transportation, insurance, debt minimums—consume less than 50 percent of your gross income after taxes. Wealth, by contrast, usually requires that same category drop below 25 percent, with significant surplus going toward investments that compound independently of your labor. Here is the part nobody tells you: crossing $100,000 often pushes you into a significantly higher tax bracket, sometimes making your take-home pay increase by only 8 to 12 percent despite the 7-figure headline. I learned this the hard way when my salary bumped from $96,000 to $104,000 and my biweekly paycheck barely moved. The marginal tax rate hit me along with FICA, state tax, and the phase-out of certain deductions. Net effect: about $400 more per month, not the $2,000 I assumed.
If you are working backward from a desired net income, you need to calculate the gross using effective tax rates for your situation, not just look at bracket thresholds. A quick rule of thumb: in most moderate-to-high tax states, you need to target roughly $130,000 to $150,000 gross to feel genuinely secure on a single income with a mortgage and no dependents. That range is your actual stability floor, not $100,000. The gap between stability and wealth at the six-figure level usually comes down to three variables: geographic arbitrage, investment rate, and income sustainability. You can live comfortably on $110,000 in Tulsa, Ohio, or parts of North Carolina. You cannot do the same in San Francisco or New York City without dual incomes or significant lifestyle trade-offs. Investment rate matters more than most people realize. Someone making $120,000 and saving 30 percent will reach a different financial position in five years than someone making $150,000 and saving 8 percent. The lower earner is often closer to traditional wealth markers because wealth is defined by assets, not income. I encountered a specific edge case recently that illustrates this well. A client came to me making $115,000 as a contractor with no employer benefits, no health insurance subsidy, and quarterly tax estimates eating into cash flow. By every standard metric she should have been comfortable. She was not. The workaround was straightforward but non-obvious: she restructured her income into a series of smaller, predictable monthly retainers instead of project-based billing, opened a health savings account to reduce taxable income by roughly $4,150 annually while covering her insurance costs, and shifted her emergency fund from a standard savings account to a money market fund that yielded enough to offset some of the instability. Within six months her stress dropped and her actual savings rate doubled, even though her gross income stayed the same.
Get the Full Details

Another counter-intuitive point: sometimes the six-figure milestone works against you. Income-based repayment plans for federal student loans, certain childcare subsidies, and even some insurance premiums use adjusted gross income as a threshold. Crossing $100,000 can disqualify you from programs that would save you more than the extra taxes cost you. I've seen this happen with spouse-dependent benefit calculations and graduate program income caps. Always model the total financial picture, not just the paycheck. The ceiling of six figures is where wealth conversations truly begin. At $200,000 to $250,000 gross, most people in reasonable cost areas can sustain a 30-to-40 percent savings rate and hit common wealth benchmarks within a decade. Below $150,000, it is still achievable but requires tighter discipline on housing and lifestyle inflation, which tends to creep up automatically once you cross that first magical number. There is no download link or tutorial for this because it is not a tool. It is a calculation you need to run for your own life. The numbers shift based on your location, your debt, your family structure, and your risk tolerance. But the framework is consistent: define stability as expenses under 50 percent of net income, define wealth as assets generating enough passive income to cover those same expenses, and work backward from there rather than forward from a salary figure.