What PMT Actually Does in Real Finance
PMT is one of those functions everyone knows because they had to use it in Excel at least once, and then immediately forget how it works after the spreadsheet closes. The function exists to calculate the fixed periodic payment on a loan or annuity, given a constant interest rate. That's it. But the way people approach it tells you whether they actually understand what's happening under the hood or if they just trust the green box to spit out a number. The formula behind PMT is built on the concept that money today is worth more than money tomorrow, which is the same principle that runs discounted cash flow analysis. The difference is that PMT locks you into a rigid structure, while DCF leaves the cash flows flexible. I find myself reaching for PMT when I'm doing something like calculating a car loan or a mortgage, where the payment is fixed and the term is set. I stop using it when I'm modeling something like a project with uneven returns across years, because PMT can't handle that. You have to build your own discounting in that case.
What Is Pmt Finance Unlocking The World Of Discounted Cash Flows
That question sits at the intersection of two things people often confuse. PMT handles periodic payments with a fixed rate, while discounted cash flow is the broader framework for valuing any stream of future money. You can think of PMT as a narrow tool inside the DCF world, specialized for the case where every payment is identical and every period is the same length. When the payments deviate from that pattern, you leave PMT behind and go back to the raw discounting math. The practical value of PMT shows up most clearly in debt modeling. If you're evaluating whether a business can service its debt, you need to know the payment amount before you look at anything else. That's the first step. You calculate PMT using the loan amount, the interest rate, and the number of periods, and then you check whether the cash flow you expect to generate covers that number comfortably. In my experience, the margin of safety around that coverage ratio is usually where deals fall apart, not the calculation itself.
The Mechanics of PMT in Practice
I spend more time debugging PMT mistakes than I do using it correctly, and the mistakes are almost always the same ones. The most common is mixing periods, like plugging in an annual interest rate while the payment frequency is monthly. That gives you a number that looks plausible but is way off. The fix is straightforward: divide the annual rate by the number of payment periods per year, and multiply the number of years by those same periods to get the total count. It's easy to skip that step when you're in a hurry, and that's exactly when errors creep in. Another thing worth noting is that PMT assumes the payment happens at the end of each period unless you tell it otherwise. Some loans structure things differently, and if you don't adjust the type argument, your result shifts by one period's worth of interest. It's a small detail, but it matters when you're comparing offers or building a model that other people will audit. I learned this the hard way when a colleague pointed out that my loan comparison was off by a few hundred dollars because I hadn't set the type flag correctly. I started double-checking that every time since. Let me walk through a concrete example rather than leaving it abstract. Say you're looking at a equipment loan for a small manufacturing project. The loan amount is 120,000, the annual interest rate is 7.5 percent, and the term is five years with monthly payments. You convert the annual rate to a monthly rate by dividing by 12, giving you 0.625 percent per period. The total number of periods is 60. Running the PMT calculation with those inputs gives you a monthly payment of roughly 2,399. That's the number you compare against your projected monthly cash flow from the equipment. If the equipment generates 2,800 in net revenue per month, you're covered. If it generates less, you're taking on risk that you should quantify before signing anything.
Get the Full Details
Where PMT Meets Discounted Cash Flow
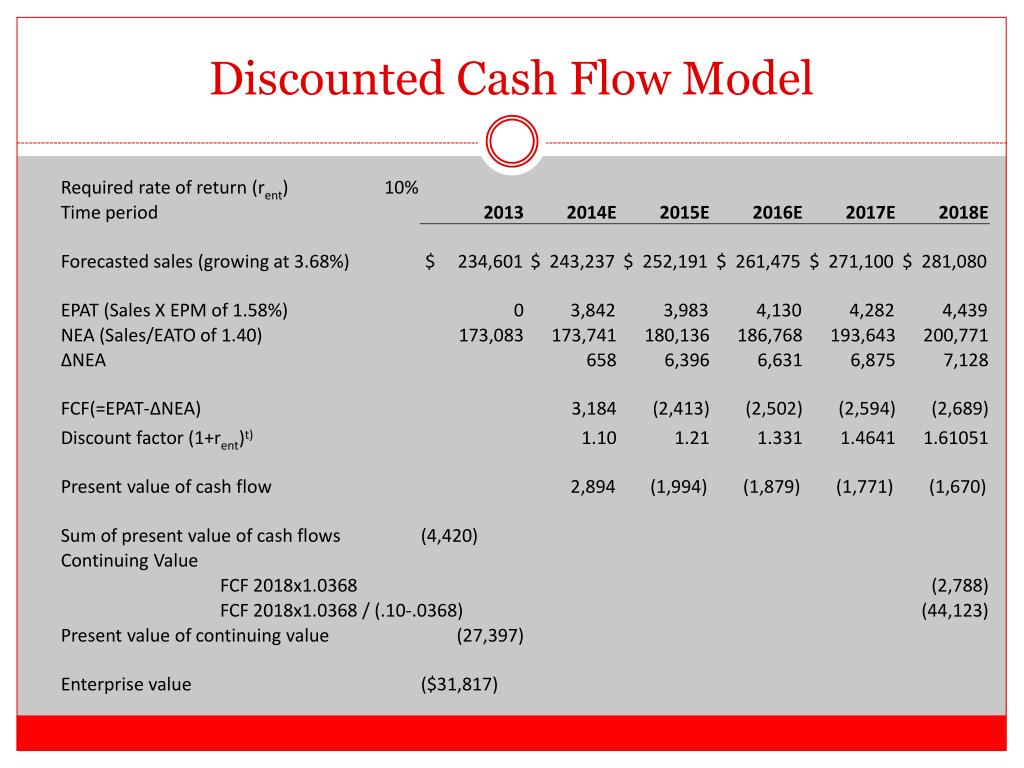
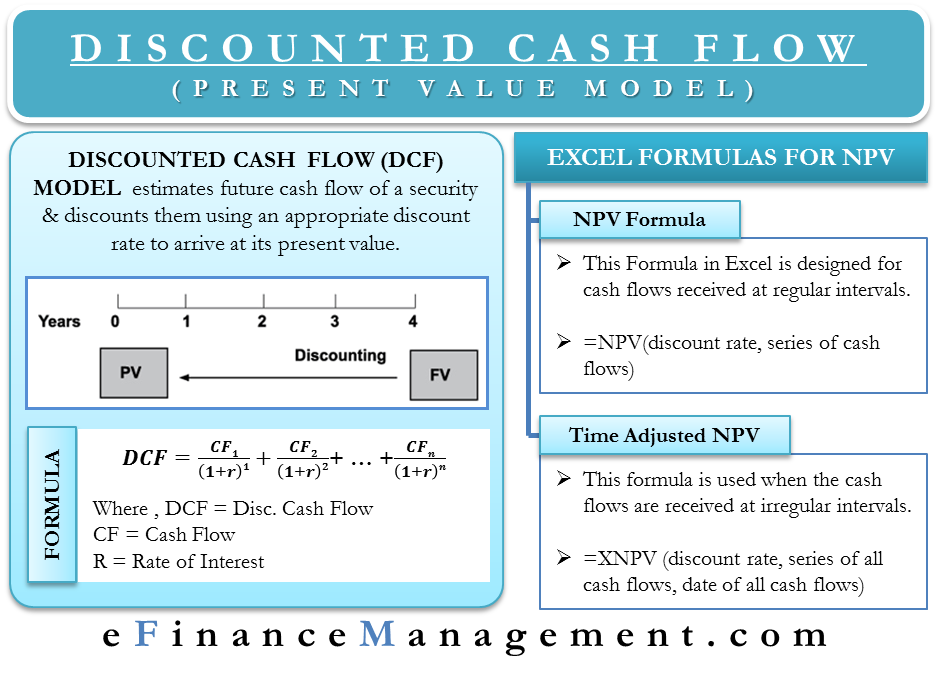
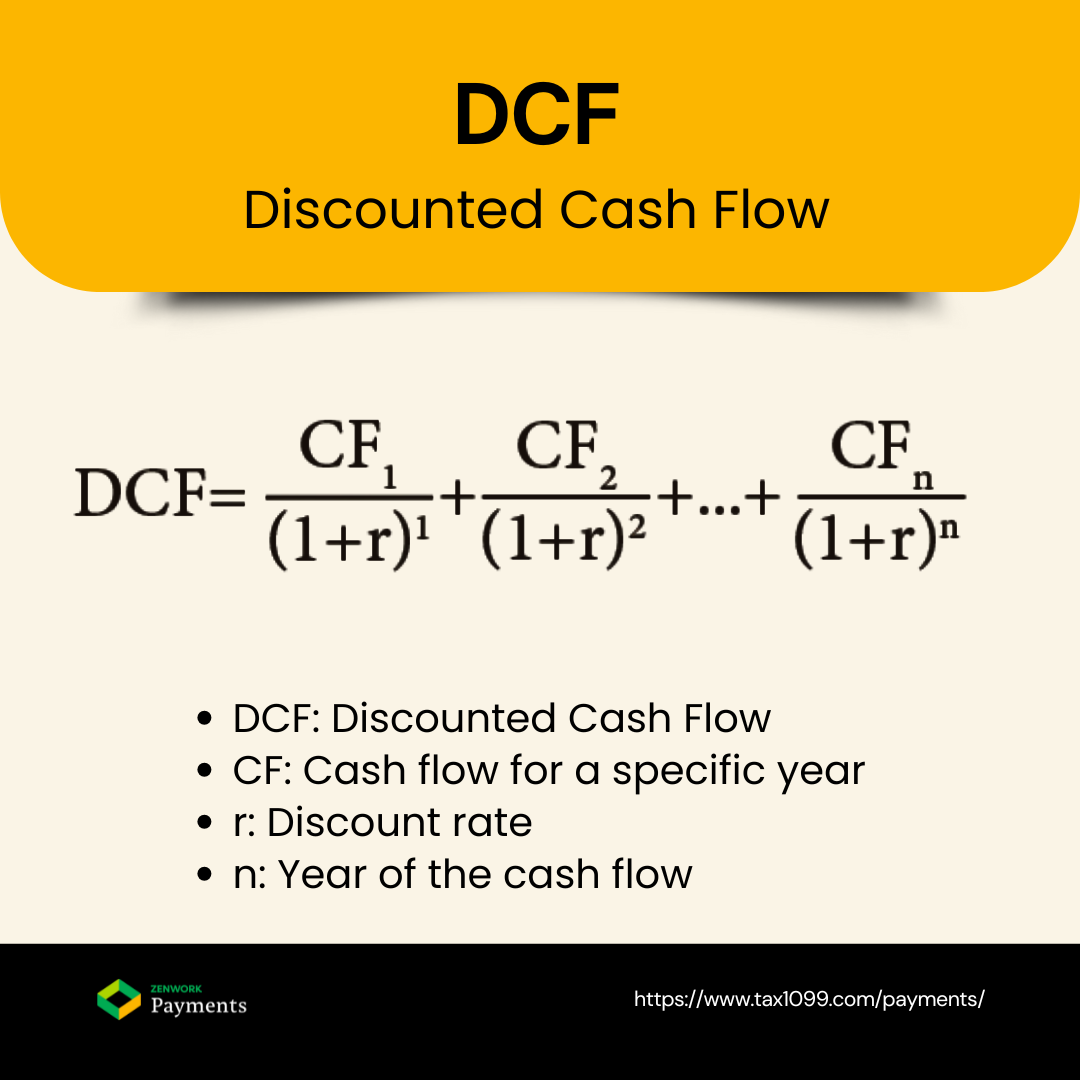
The connection between PMT and DCF is more subtle than people usually make it. PMT gives you a single payment number, while DCF discounts each future cash flow individually to its present value. In theory, you could reverse-engineer a PMT result using DCF principles by discounting each identical payment and solving for the annuity factor, but that's just recreating what PMT already does more efficiently. The real overlap is in how you use both tools together when evaluating an investment or a financing decision. Here's how I approach it in practice. First, I use PMT to determine what the debt service will be if the business takes on a loan. Then I run a DCF model that projects the business's cash flows over the same horizon, discounting them at an appropriate rate that reflects the risk. The comparison between the two tells you whether the business can support the debt and still leave room for equity returns. This is the framework behind leveraged buyouts, capital expenditure decisions, and most project finance deals. It's not complicated, but it requires discipline because mixing up the discount rate or the timing assumptions will give you a result that looks right but isn't. One insight that beginners miss is that PMT doesn't account for the timing of when cash actually hits your account. If you're modeling a lease or a bond where payments come at the beginning of the period instead of the end, the standard PMT function will underestimate your liability unless you adjust it. I've seen this trip up people who were confident in their numbers right until a cash flow statement didn't match their model. The fix is to set the type parameter to 1, which shifts the calculation to beginning-of-period payments. It's a small change, but it matters in tight spreadsheets where accuracy is non-negotiable.
The Limits of PMT and When to Walk Away
PMT is useful, but it has hard boundaries, and ignoring those boundaries is how models get broken. The function only works when payments are level and the interval between them is consistent. If you're dealing with balloon payments, interest-only periods, or step-up rates, PMT is the wrong tool. You need to build a custom schedule that mirrors the actual cash flow structure. I've spent hours once trying to force PMT to handle a loan with a three-year interest-only period followed by amortization, and I finally just gave up and wrote a loop that calculated each segment separately. It took me about twenty minutes to build, and the result was more accurate than anything PMT could produce. Another limitation is that PMT assumes the interest rate is fixed. Variable-rate loans, adjustable mortgages, and most corporate debt with floating coupons don't fit this mold. When the rate changes, you have to recalculate the payment at each reset point, which means PMT only works for the slice of the timeline where the rate is constant. I handle this by breaking the model into chunks, running PMT for each rate period, and then stitching the results together. It's not elegant, but it's honest about what the function can and can't do. There's also the issue of fees and charges that PMT doesn't capture. Origination fees, prepayment penalties, and insurance premiums all affect the true cost of a loan, but PMT only returns the principal and interest portion. If you want to compare two loan offers that have different fee structures, you need to add those costs separately and run a proper DCF analysis that includes them. Otherwise, you're comparing apples to oranges and might pick the worse deal because the payment number looked smaller.
A Real Case Where I Got Burned
I once modeled a equipment lease for a client who was comparing it to a loan. The lease had escalating payments, which is common in real-world deals because the lessor builds in wear and maintenance reserves. I ran PMT on the loan side and a manual discounting schedule on the lease side, but I used the wrong discount rate for the lease. I applied the loan rate instead of the lease implicit rate, which is typically higher because leases carry different risk and tax implications. The comparison came out in favor of the lease, and the client almost signed before a second review caught the error. I switched the discount rate and the picture flipped completely. That experience taught me to never assume rates are interchangeable between debt and lease analysis, no matter how similar the cash flows look on the surface. If you're going to use PMT, here's how I recommend approaching it. Start by writing down the three inputs you need: the interest rate per period, the total number of periods, and the present value or loan amount. Make sure the rate and the periods match in terms of frequency, because that's where most mistakes happen. Next, decide whether payments are at the beginning or end of each period, and set the type argument accordingly. Finally, verify the output by checking it against a simple amortization schedule, even if you only do the first few periods manually. This takes about five minutes and saves you from chasing errors later. For deeper analysis, pair PMT with a DCF model that includes the actual cash flows, not just the debt payment. Calculate the debt service coverage ratio by dividing your projected operating cash flow by the PMT result. A ratio below 1.2 usually signals trouble, and anything below 1.0 means you're underwater. These thresholds aren't laws, but they're benchmarks that have held up across multiple deals I've worked on. Adjust them based on the industry and the volatility of the cash flows, but don't ignore them entirely.
When you're ready to move beyond simple loans and into more complex structures, start by breaking the problem into pieces. Handle the fixed-payment portions with PMT, and model the variable or irregular portions with custom discounting. I don't recommend trying to force a single formula to cover everything, because it usually breaks somewhere and you won't know where until it's too late. A modular approach lets you test each piece independently and catch issues early.
Why This Matters for Decision Making
The reason PMT and DCF belong together in the same conversation is that both are about comparing money across time. Every financial decision, whether it's taking on debt, investing in equipment, or evaluating a project, requires you to answer the same basic question: is the money I'm committing today worth more than the money I'll receive later? PMT gives you a snapshot of the commitment side, while DCF gives you a view of the return side. Using them together gives you a complete picture, and skipping either one leaves you guessing. I've watched people make decisions based on payment size alone, without looking at the total present value of what they're getting in return. That's a shortcut that works until it doesn't, and when it fails, the damage is usually significant. A good analyst doesn't rely on shortcuts. They run the numbers, check the assumptions, and acknowledge where the model is uncertain. PMT is a tool for that process, not a replacement for thinking through the problem carefully.