How Personal Contract Purchase Actually Works When You Sit Down With a Finance Broker
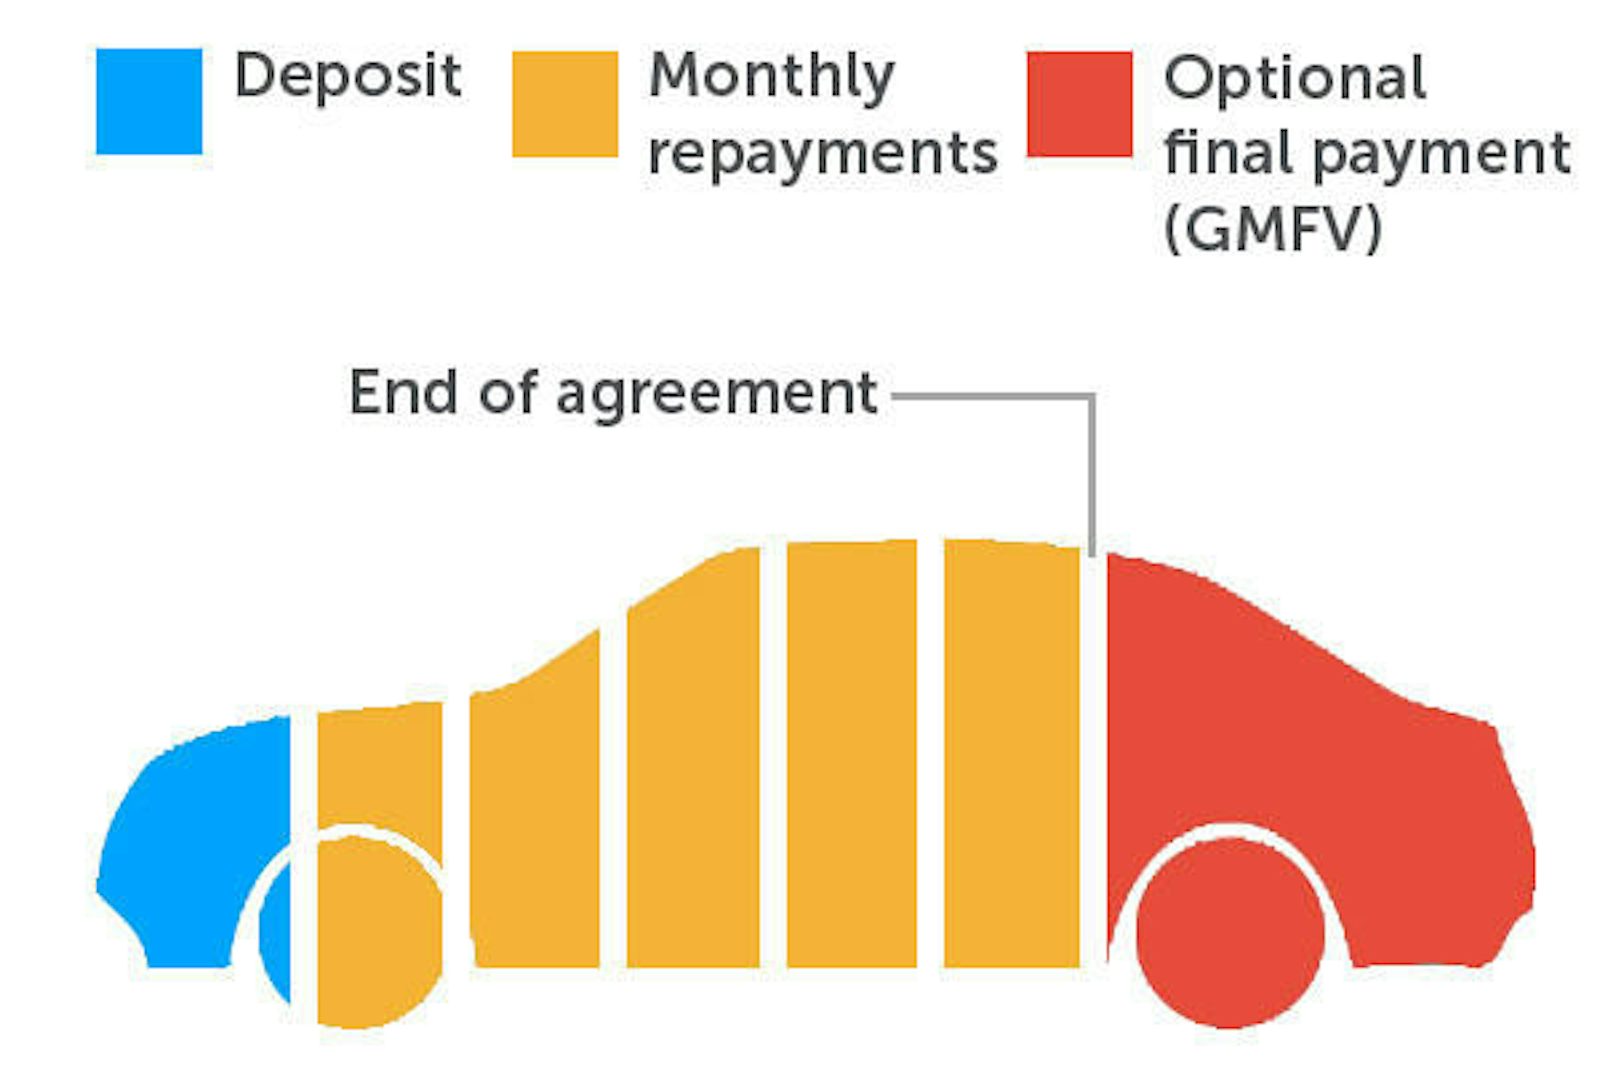
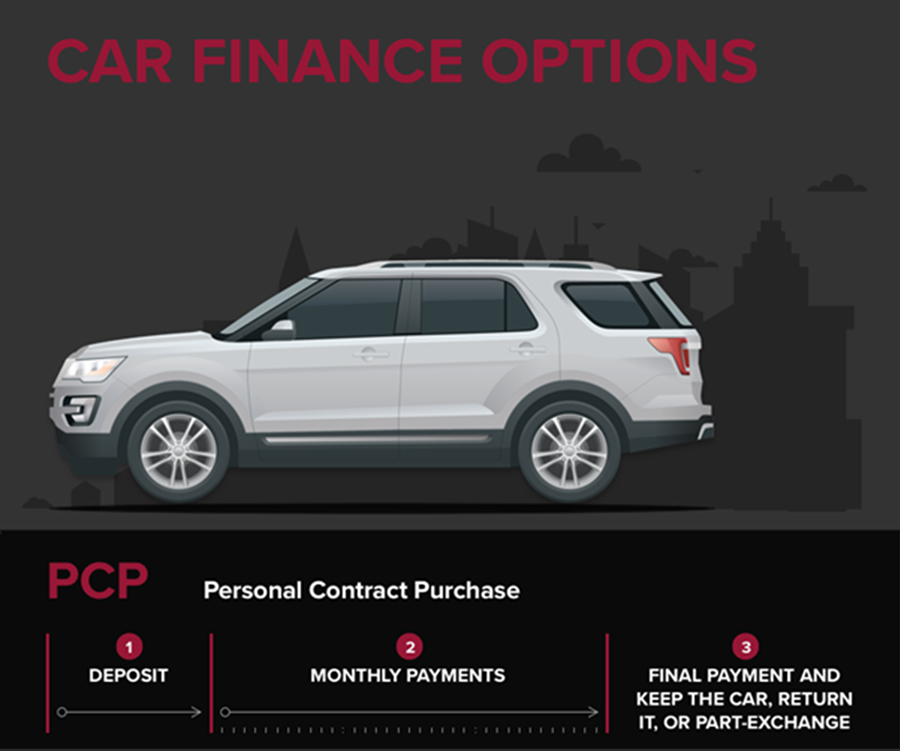
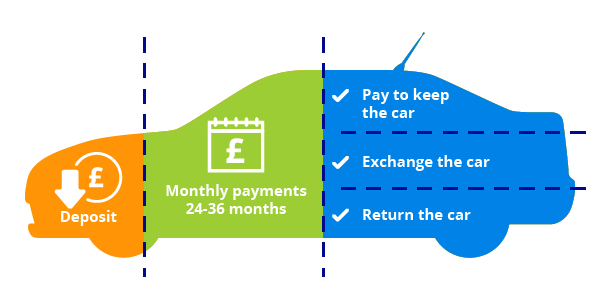
I spent years watching people get confused at dealer desks about PCP agreements, and honestly, most of it comes down to one misunderstood number. The final balloon payment, often called the Guaranteed Future Value or GFV, is where the whole structure bends. You pay monthly for the depreciation between what you drove off in the car for and what it is predicted to be worth at the end of the term, usually three years. At the end, you have three choices. Pay the balloon, return the car, or use any equity as a deposit on a new PCP deal. That third option is what most dealers push, and it is also where people quietly get rolled. PCP is structured so that the monthly payments look artificially low compared to a standard hire purchase. The catch is the residual value at the end, which the finance company estimates based on historical depreciation data from sources like Cap HPI or Experian AutoCheck. If the car retains its value better than expected, you build positive equity. If it tanks, you owe nothing beyond returning the car, which sounds safe until you hit the mileage overage and condition charges. I learned this the hard way with a 2019 BMW 3 Series I took on a 36-month PCP deal. The agreed annual mileage was 8,000. Life happened, and I hit 11,400 miles in year two. When I went to return it, the dealer tried to charge me 3,400 miles at £0.12 per mile, which came to £408. The workaround was simple but nobody tells you about it upfront. I had already been tracking my mileage via the BMW ConnectedDrive app, which logs exact odometer readings automatically. I pulled the report, showed the dealer the discrepancy between their system and the manufacturer data, and they adjusted the figure. You need your own contemporaneous records. Relying on the dealer's tally is asking to be overcharged.
The real skill with PCP is understanding when the residual value works in your favor versus when it does not. Some manufacturers subsidize their GFV to make monthly payments look cheap. A Kia or Hyundai often has an artificially high residual because they want to move volume. That means your equity pot at the end is inflated on paper, but you cannot access it unless you trade in. Meanwhile, a Porsche or Mercedes might have a lower residual that is more realistic, meaning your monthly payments are higher but the car actually holds its value without any artificial subsidy propping it up. Here is a detail most guides skip. The settlement figure you receive if you want to pay off a PCP early is not simply the remaining monthly payments. Under UK regulations, you can pay off the agreement at any time, and the amount you owe is capped at 50% of the total amount payable plus any accrued interest, whichever is lower, for the first half of the term. After that point, it is just the remaining balance including interest. This is useful if your financial situation changes and you need to exit early, but only if you request the official settlement figure in writing first. Verbal quotes from brokers are useless and often inflated. The biggest blind spot with PCP is condition assessment. The industry standard is the NATS guidelines, which define acceptable wear and tear. A scratch the size of a pound coin is fine. Anything deeper, any curb rash on alloys, or interior stains get charged. I once returned a lease-equipped Ford Focus where the dealer flagged a faint scuff on the driver's door sill that was barely visible. It set me back £175. Had I photographed every panel on delivery and kept those images, I could have disputed it immediately. Every reputable broker should send you a condition report with photos at the start of the contract. If they do not, request it in writing before you drive off the lot.
There are scenarios where PCP is the wrong product entirely. If you regularly exceed 12,000 miles a year, a standard hire purchase or even a personal loan is almost always cheaper. PCP penalizes high mileage through both overage fees and inflated depreciation assumptions. Similarly, if the car you want does not have a strong residual value history, the GFV will be guesswork rather than data, and your monthly payments could shift significantly depending on how the finance provider prices the risk. The best approach is to run the numbers yourself before walking into a dealership. Calculate the total amount payable including the balloon, compare it against the car's predicted market value at the end of the term, and check whether you would actually want to pay that balloon or just trade up. If the gap between what you would pay at the end and the car's real market value is small, you are probably better off with a different finance product altogether.
Get the Full Details