That Charge From Otc Brands Is Probably Not A Mystery Anymore
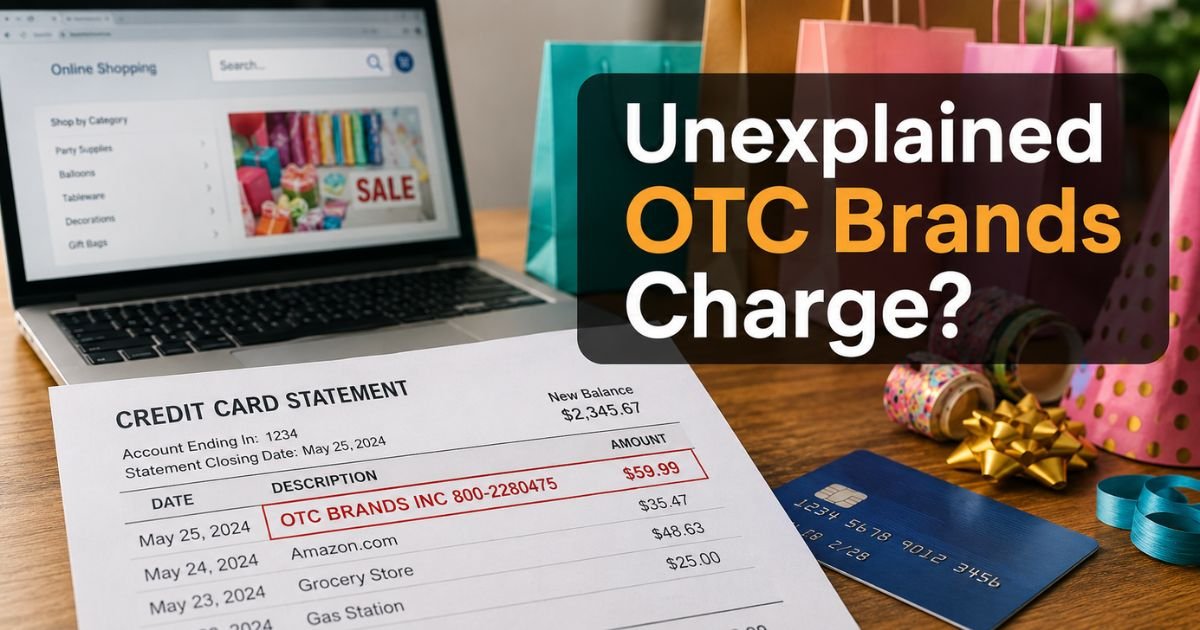
You see Otc Brands on your statement and your stomach drops for exactly three seconds before you remember you bought something online recently. I get it. I was there. The descriptor looks like some sketchy financial entity, not a store you recognize, and suddenly you're wondering if someone is running up charges on your card while you sleep. Here is what actually happens. Payment processors don't always use the retail store name. They use merchant category codes and billing descriptors that mean something to the banking network but absolutely nothing to you. OTC generally refers to over-the-counter purchases - things you can buy without a prescription at drugstores, convenience stores, and big box retailers. The charge isn't a fraud alert. It's probably just your normal spending with a confusing label.
What Is Otc Brands On My Credit Card Decoding Unfamiliar Charges
OTC brands show up on statements because the payment gateway routes the transaction through a third-party processor, and that processor assigns a merchant descriptor that prioritizes the processing category over the actual store name. CVS, Walgreens, Rite Aid, Walmart, Target, Family Dollar - they all run through various OTC-coded merchants depending on which payment network segment handles their transactions. When I first noticed this, I spent two weeks tracking down every OTC charge on my statement by going through transaction emails and receipt confirmations. That was unnecessary. The fastest way is to check your transaction history against your recent purchases at pharmacies and discount retailers. Usually the charge amount matches exactly. The only reason it does not is if the merchant added tips or processing fees that get appended to the descriptor. One thing most people miss is that the OTC brand name on your statement might not be the OTC of the store where you shopped. It could be the name of the payment aggregator that processed your card. For example, a charge at a small independent pharmacy might show up under a completely different OTC descriptor because the pharmacy uses a regional processing cooperative. This tripped me up for about six months before I realized I was looking at the payment handler, not the point of sale.
The workaround that actually works is pulling your card's detailed transaction log from your bank's app or website. The short descriptor is just the summary line. The full authorization data includes the merchant name and address that the terminal reported. That field is usually buried in the transaction details behind a link or an expandable section. Once you see the actual terminal location, you can match it to a store you visited even if the statement line says something like OTC Health Services or similar corporate entity. There are also legitimate third-party services that help decode these charges. The main one people ask about is the Merchant Category Code lookup through the banking associations, but honestly you do not need that level of formalism for your own statement. A simple reverse search on the exact descriptor text plus your city or the date of the charge usually surfaces a forum post or blog entry from someone else who saw the same thing. That is often faster than any official lookup tool. I should mention the edge case where this system breaks down. If you have a prepaid card or a secured credit card from a smaller issuer, the descriptor translation layer may not exist at all. Some community banks and credit unions skip the merchant name enrichment step and just pass through whatever the processor sends. In those cases the OTC label stays vague indefinitely and you are stuck guessing. I ran into this with a local credit union about three years ago and ended up just matching charges by amount and date manually. It took longer but it worked.
Get the Full Details

Another limitation worth noting is that not every unfamiliar charge labeled OTC is actually a purchase. Some subscription services, automatic bill payments, and recurring memberships use OTC-coded processors because of how their merchant accounts are classified. If you signed up for a wellness app or a supplement delivery service, those charges routinely show up as OTC brands even though no physical counter was involved. The billing descriptor tells you very little about the actual service type. So when you see Otc Brands on your statement, check your receipts first. Then check the full transaction details in your banking portal. If nothing matches and the amount is unfamiliar, call the number on the back of your card and ask the representative to pull the merchant category and terminal location. They can usually tell you within five minutes whether it is a legitimate charge or something that needs disputing. Most of the time it turns out to be neither mysterious nor suspicious. Just bad descriptor labeling from the payment processing side.