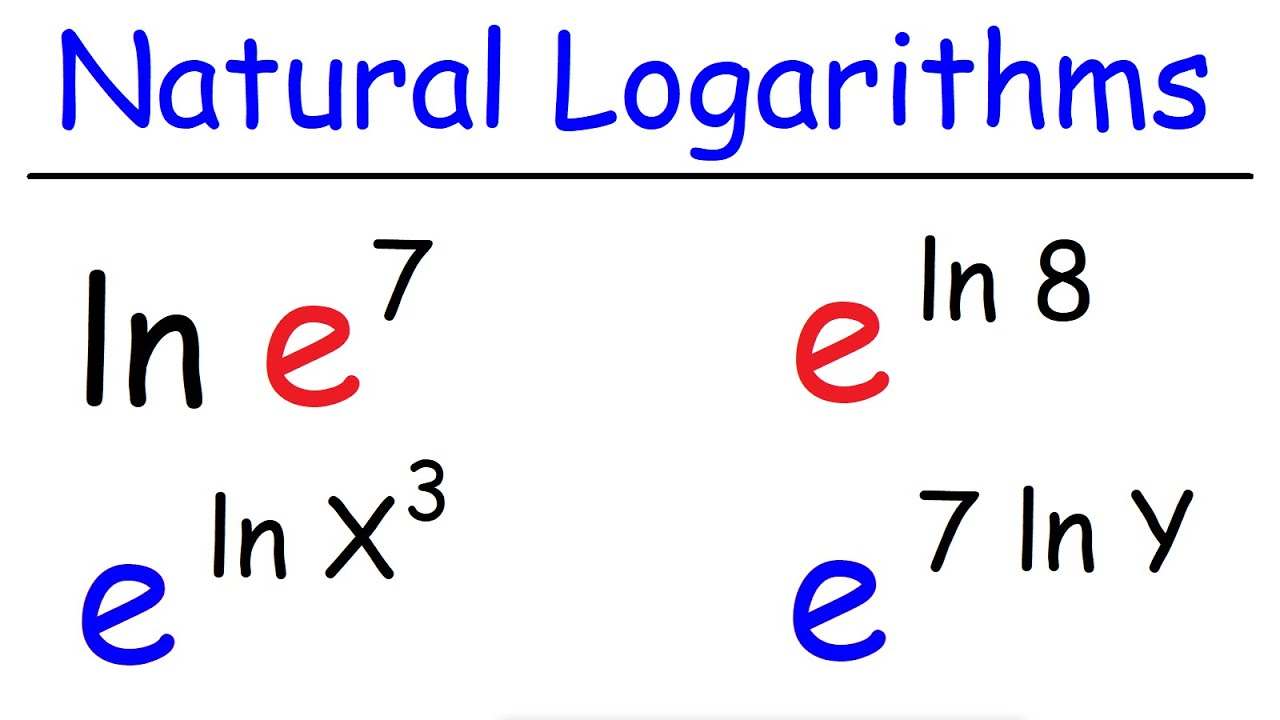Understanding The Natural Logarithm Without The Hype
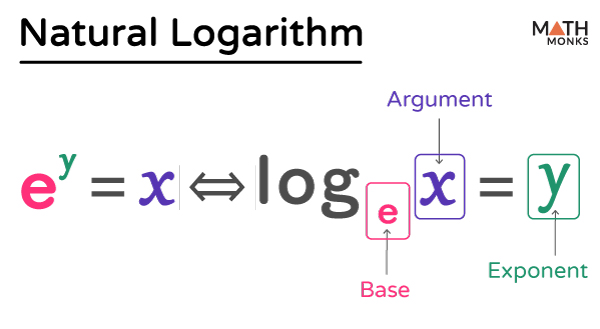
The natural logarithm, written as ln, is just the logarithm to the base e. That base e is approximately 2.71828 and shows up naturally whenever something grows or decays at a rate proportional to its current size. You do not need to memorize anything dramatic about it. It is a tool, and like any tool, it either works for your problem or it does not. At its core, ln(x) answers the question: how much time does something need to grow continuously at 100 percent per unit of time to reach size x? If you put money in a bank account with continuous compounding at a 100 percent annual rate, ln(2) tells you roughly how long it takes to double. The number is about 0.693. That is why the rule of 70 in finance works, since 70 divided by your percentage rate gives you an approximate doubling time. It is not magic. It is just calculus doing its job quietly. I learned this the hard way back in 2014 when I was working on a project modeling contaminant decay in groundwater. We had field data that looked exponential, but the sensor readings were noisy, and standard least squares fitting kept producing absurd half life values. The problem was not the model. It was that we were trying to fit the raw data directly instead of linearizing through the natural log first. Once I transformed the concentration values by taking ln of each reading and ran a simple linear regression on the log transformed data, the fit became stable and interpretable. The residuals made sense too. You can skip this step in modern software if you use nonlinear solvers, but I still prefer the log transformation for quick diagnostics because it exposes heteroscedasticity immediately.
How It Actually Works In Practice
The derivative of ln(x) is 1/x. That is the single most useful thing about this function. It means that small changes in x near zero have enormous impact on ln(x), while large changes at high x barely register. This property is why ln is the right tool for measuring relative change rather than absolute change. In finance, continuous compounding uses ln directly. The formula A = Pe^(rt) is everywhere in option pricing and bond valuation. The Black Scholes model relies on ln(S/K) as the log return variable because stock prices are modeled as lognormally distributed. This is not an accident. If returns were normally distributed, prices could go negative, which they cannot. Taking the log of prices gives you a variable that behaves much better statistically. I once spent three days debugging a portfolio risk model only to realize the team had been calculating volatility from simple arithmetic returns instead of log returns. The difference seemed tiny at first, maybe a basis point or two in annualized volatility, but it compounded across the simulation steps and produced materially wrong VaR numbers. Log returns are additive over time, which simple returns are not. That alone should decide it for anyone doing multi period analysis.
Common Misunderstandings That Waste Time
People confuse ln with log all the time. In higher mathematics and science, log usually means ln. In engineering and some applied fields, log means base 10. Check your convention before you plug numbers into anything. A factor of 2.3 error between ln and log base 10 has ruined more spreadsheets than I care to admit. Another thing that trips people up is assuming ln works the same way at extreme values. ln(x) is undefined for x less than or equal to zero. I have seen junior analysts try to take the log of negative returns or zero values and then wonder why their models crash. The workaround is straightforward: shift your data by adding a constant, or use a different model entirely. Sometimes the problem is not the math. It is that your data generation process produces boundary values that no logarithm can handle cleanly. There is also the false belief that ln is only for growth problems. It appears in entropy calculations in thermodynamics, in information theory through Shannon entropy, in the normal distribution formula, and in the Riemann zeta function. It is woven into probability theory through the exponential distribution, where the mean is simply 1/lambda and the survival function is e^(-lambda*x). If you understand ln well, you understand the exponential distribution backwards and forwards.
Get the Full Details
When Ln Fails You
The natural logarithm is not a universal fix. If you are dealing with data that has structural zeros or true mass points at zero, log transformation creates problems that are harder to solve than the original ones. You cannot take the log of zero. You can add a small constant, but that introduces arbitrary bias. In those cases, consider using a generalized linear model with a log link function instead, or switch to methods designed for zero inflated data like hurdle models. In finance specifically, log returns assume that price changes are multiplicative and the underlying distribution is lognormal. When markets experience flash crashes or fat tailed events, this assumption breaks down. The 2010 flash crash and the 2020 COVID crash both produced return distributions that log normal models handled poorly. Using ln still gives you useful quantities, but you need to be honest about the tail risk your model is missing. No amount of logarithmic transformation fixes a bad distributional assumption.
A Quick Practical Guide
If you need to calculate ln by hand for rough estimates, remember that ln(2) is about 0.693, ln(3) is about 1.099, and ln(10) is about 2.303. You can build other values from these using the property that ln(a*b) = ln(a) + ln(b). For ln(6), you add ln(2) and ln(3) to get roughly 1.792. This is not precise enough for any serious work, but it is fast for sanity checking your calculator output. For actual work, use a scientific calculator, Python, R, or Excel. The function is built into every tool. In Python it is math.log(). In Excel it is LN(). In R it is log(). All of them default to natural log unless you specify a base. Double check your software documentation once. Getting it wrong costs you minutes, not hours, but why risk it. The natural logarithm is not complicated. It is also not trivial. It connects differential equations to real world phenomena in a way that few other functions do. Spend some time with it, work through the derivations yourself, and you will find it showing up in places you did not expect. That is the nature of mathematics. The tools you learn in one context tend to reappear in completely different ones, usually when you need them most.