Most people confuse gross margin with profit. That confusion alone has sunk more small businesses than bad marketing or weak product.
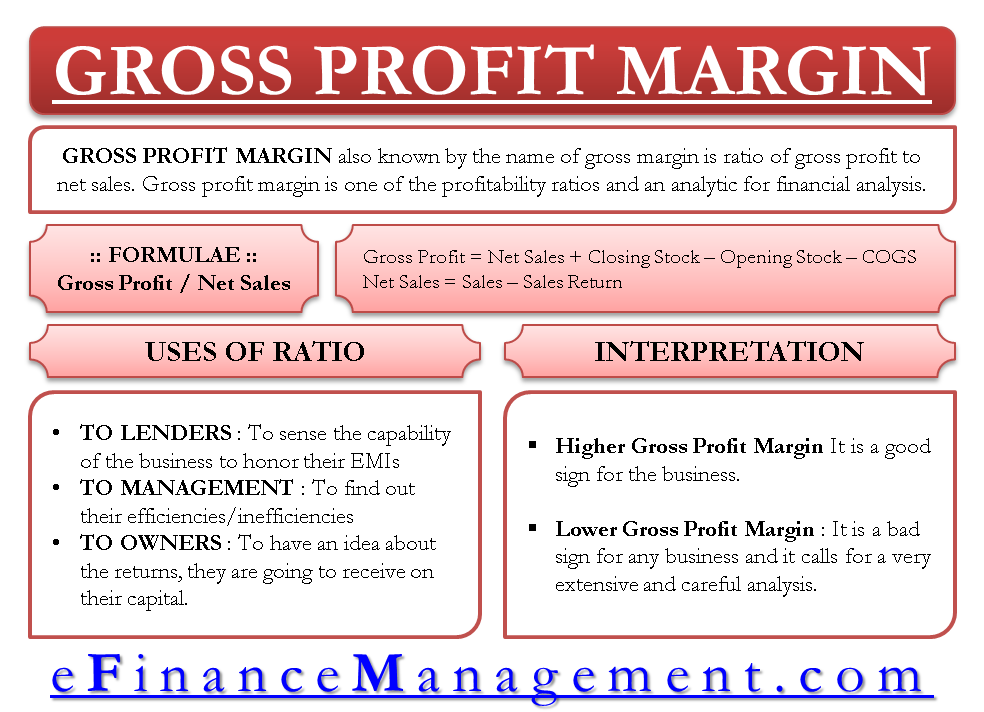
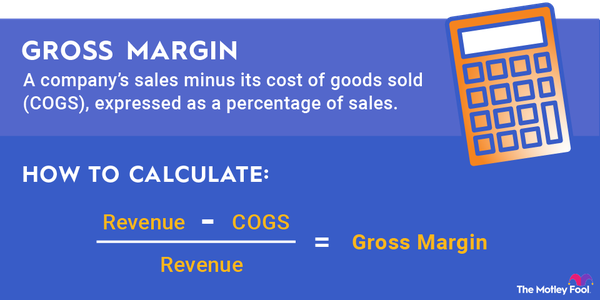
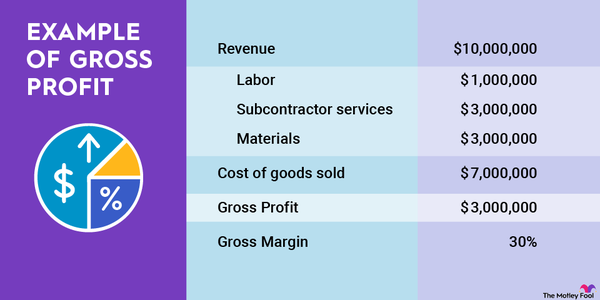
Gross margin tells you how much money remains after subtracting the direct costs of making or delivering your product. It is one of the simplest calculations in business and one of the most frequently misunderstood. People see a healthy percentage and assume everything is fine. That assumption is usually wrong. I spent three years watching founders ignore this number because it looked decent on paper while their actual cash position bled out from below the line expenses they weren't tracking properly. The calculation itself is dead simple. You take your total revenue and subtract your cost of goods sold. The result is your gross profit. Divide that by total revenue and multiply by 100 to get a percentage. That percentage is your gross margin. A company making $100,000 in revenue with $60,000 in direct costs has a $40,000 gross profit and a 40% gross margin. There is nothing fancy about this. The problem is knowing what to include in that cost of goods sold figure and what to ignore. Here is where most people mess up. COGS should only include costs that are directly tied to producing or delivering the product or service. For a manufacturer, this means raw materials, direct labor, and factory overhead. For a software company, it means hosting costs, payment processing fees, and any direct support costs tied to delivering the product. It does not include rent for your office, salaries for your sales team, or the coffee machine you bought last month. Those are operating expenses. They sit below the gross margin line. Keeping them separate matters because the two categories tell you completely different things about where your money is going.
I had a client running a subscription box business who was genuinely confused why his gross margin looked strong at 55% but he could barely break even at the end of the month. He had bundled his warehousing staff salaries into his COGS, which artificially deflated his gross margin, while his customer acquisition costs, which should have been operating expenses, were buried elsewhere in his P&L. Once we cleaned up the classification and moved the right items to the right line, his gross margin actually dropped to 38%. Lower looking margin but a completely honest picture of what was happening. That correction alone changed how he priced his boxes within two weeks.
Why This Number Matters More Than Revenue Growth
You can grow revenue all the way to a million dollars and still lose money if your gross margin is terrible. A business pulling in $500,000 with a 70% gross margin keeps $350,000 to cover operating costs and generate profit. Another business pulling in the same revenue with a 20% gross margin only has $100,000 to work with. The second company needs significantly lower operating expenses just to survive, and in most cases that is impossible to achieve. Revenue growth without margin awareness is just a faster path to burning cash. The reason people call this the silent profit guardian is that it operates quietly in the background of every financial decision you make. Every pricing change, every supplier switch, every new product launch moves this number. When you understand how each decision affects your gross margin, you stop guessing and start making informed tradeoffs. A 5% price increase on a product with a 30% margin improves your absolute dollar profit more than a 10% increase in sales volume would. That is not intuitive to most business owners. I learned it the hard way during a period when we were chasing volume to the point of exhaustion while our margins slowly compressed.
Get the Full Details
Common Mistakes That Distort Your Reading
The first mistake is using gross margin as a standalone metric without benchmarking it against industry standards. A 40% gross margin means something completely different for a restaurant than it does for a software company. Restaurants typically operate between 25% and 35%. Software companies often sit above 70%. Comparing yourself to the wrong benchmark gives you a false sense of security or unnecessary panic. Look at your actual industry peers, not generic examples you find on a business blog. The second mistake is ignoring the difference between gross margin and net profit margin. Gross margin shows you the profitability of your core product or service before overhead. Net profit margin shows you what is left after every single expense, including taxes and interest. A business can have an excellent gross margin and a negative net margin if its operating costs are too high. Both numbers deserve attention. Focusing exclusively on one blinds you to problems lurking in the other. There is also a subtle trap around how you calculate COGS when you carry inventory. The valuation method you choose — FIFO, LIFO, or weighted average — changes your cost of goods sold and therefore your gross margin, even though the underlying business has not changed. In periods of rising prices, FIFO produces a lower COGS and higher gross margin than LIFO. This is not accounting trickery. It is a legitimate difference in how you allocate costs. But it matters for comparisons. If you are evaluating multiple products or tracking performance over time, pick a method and stick with it. Do not switch midway through a fiscal year just because the numbers look better under a different approach. I learned this when a previous employer switched inventory valuation methods mid-quarter and my margin reports suddenly looked dramatically better without a single real operational improvement.
How to Use This in Practice
Start by calculating your gross margin for each product or service line separately. A blended company-wide number hides variation that matters. If you sell three products and two of them are losing money on a gross margin basis, the overall percentage will look fine while you are subsidizing the losers with the winners. Segment your data. Identify which offerings are actually contributing to your operating costs and which ones are consuming resources faster than they generate returns. Next, set a target gross margin based on your industry and your cost structure. This target should account for the operating expenses you need to cover. If your operating expenses are 50% of revenue, your gross margin needs to be above 50% just to break even. Anything less guarantees you are losing money on every sale. Most healthy businesses aim for a gross margin that covers operating expenses comfortably while leaving room for profit. The exact target depends on your capital structure, tax situation, and growth ambitions, but the math is straightforward. Then monitor this number monthly and track the trend over time. A sudden drop from 60% to 45% over two months signals something is wrong with your supply chain, your pricing, or your product mix. A slow annual decline from 65% to 60% might indicate inflation creeping into your input costs or increased discounting to maintain sales volume. Early detection lets you course-correct before the problem becomes structural. I recommend putting this into a simple dashboard that updates automatically from your accounting software. Building and maintaining that takes about two hours upfront and saves you several hours every month compared to manual spreadsheet work.
When Gross Margin Alone Will Mislead You
This metric has clear limitations that nobody talks about enough. Gross margin does not account for the capital required to generate that margin. A business with a 70% gross margin might require $2 million in working capital to operate, while another with a 40% gross margin might run lean with almost no capital requirement. On a return-on-invested-capital basis, the lower-margin business could be far more efficient. Gross margin is a profitability measure, not an efficiency measure. Use both. It also ignores customer concentration risk. If 80% of your revenue comes from one client who commands aggressive pricing, your gross margin numbers might look solid overall while hiding the fragility of your revenue base. One lost contract could collapse your entire margin profile overnight. Diversification matters just as much as the percentage itself. Finally, gross margin can be gamed through accounting choices. Deferring maintenance costs, capitalizing expenses that should be expensed, or manipulating inventory write-downs can all inflate your gross margin temporarily. The numbers will look good until they do not. This is why you need to understand the assumptions behind your calculation, not just trust the output. If you are not comfortable explaining exactly what went into your COGS line, you probably should not be relying on this metric for major decisions.

The bottom line is that gross margin is a tool, not an answer. It gives you a clear signal about whether your core business economics work. It does not tell you whether your marketing is effective, whether your team is well-managed, or whether your market is sustainable. Use it alongside other metrics. Treat it as a warning system rather than a verdict. When it stays stable or improves, your fundamentals are sound. When it erodes, something needs attention before it becomes a crisis. That is the actual value of understanding what this number means and what it cannot tell you.