Understanding That Line Item on Your Pay Stub
You pull up your pay stub after direct deposit hits and there it is, a description that doesn't immediately make sense. Comenity Pay shows up in the deductions or earnings column depending on how your employer structures things. It looks like a charge, but it isn't a tax, and it certainly isn't a standard employer contribution. The name itself is misleading because it sounds like a payment method your employer uses, but that isn't what it is. Comenity Pay, formerly known as Comenity Capital Services, is a private-label credit card issuer and payment platform. It operates store cards for retailers like Wayfair, Menards, and various other chains. When it appears on a pay stub, it almost always indicates a pre-authorized payroll deduction for a loan or credit obligation you personally owe to Comenity, not a payroll processing fee. Your employer isn't charging you to deposit your paycheck. They're remitting a deduction to a creditor you authorized separately. The reason this confuses people is structural. Payroll systems display deductions as simple line items, and the descriptor field pulls whatever shorthand the payroll vendor uses. Comenity Capital sometimes feeds back through payroll deduction programs specifically for employee loans, wage advance programs, or even employer-sponsored payment plans for benefits. The result is a line that reads like a bill collection rather than a tax withholding, and it sits alongside your standard FICA and Medicare entries without any context.
I encountered this firsthand while auditing pay stubs for a mid-size manufacturing company. An employee called HR panicked because Comenity Pay appeared as a negative amount on their net pay, and they had absolutely no memory of authorizing anything with Comenity. The issue traced back to a pre-authorization clause in an employee wage advance program the company had offered two years prior. The HR team hadn't updated the original enrollment paperwork, and the payroll vendor was mapping the deduction under Comenity Capital's tax ID, which is a standard setup for this type of arrangement. The fix was pulling the signed authorization from the employee's file, verifying the amount matched the loan schedule, and then issuing a corrected pay stub through the payroll system. It took about twenty minutes once we knew where the authorization was stored.
How the Deduction Actually Works
The mechanics are straightforward once you separate the employer role from the creditor role. Your employer runs payroll through a vendor like ADP, Paychex, or a similar platform. When a payroll deduction is scheduled for a Comenity obligation, the vendor processes it like any other garnishment or voluntary deduction. The money leaves your gross pay and moves to Comenity as repayment. Your employer never touches the funds. They simply forward the withholding based on the instruction file you set up. The amount displayed on your stub can be fixed or variable depending on the original agreement. Installment loans show a consistent dollar amount each period. Revolving credit balances tied to a payroll deduction plan may fluctuate if your payment is a percentage of the outstanding balance. This variability is one reason the line item raises eyebrows. Fixed deductions look predictable. Variable ones look like errors even when they're accurate. A detail most people miss involves the tax treatment. Payroll deductions for consumer loans are made with after-tax dollars. That means the amount reducing your net pay has already been subject to income tax and FICA. You are not getting a tax benefit from having Comenity Pay deducted through payroll. The only exception would be if it were tied to a qualified employer benefit program, which is rare for Comenity-related obligations. This is worth noting because some employees assume the deduction is reducing their taxable income when it isn't.
Get the Full Details
Why It Shows Up Differently Across Employers
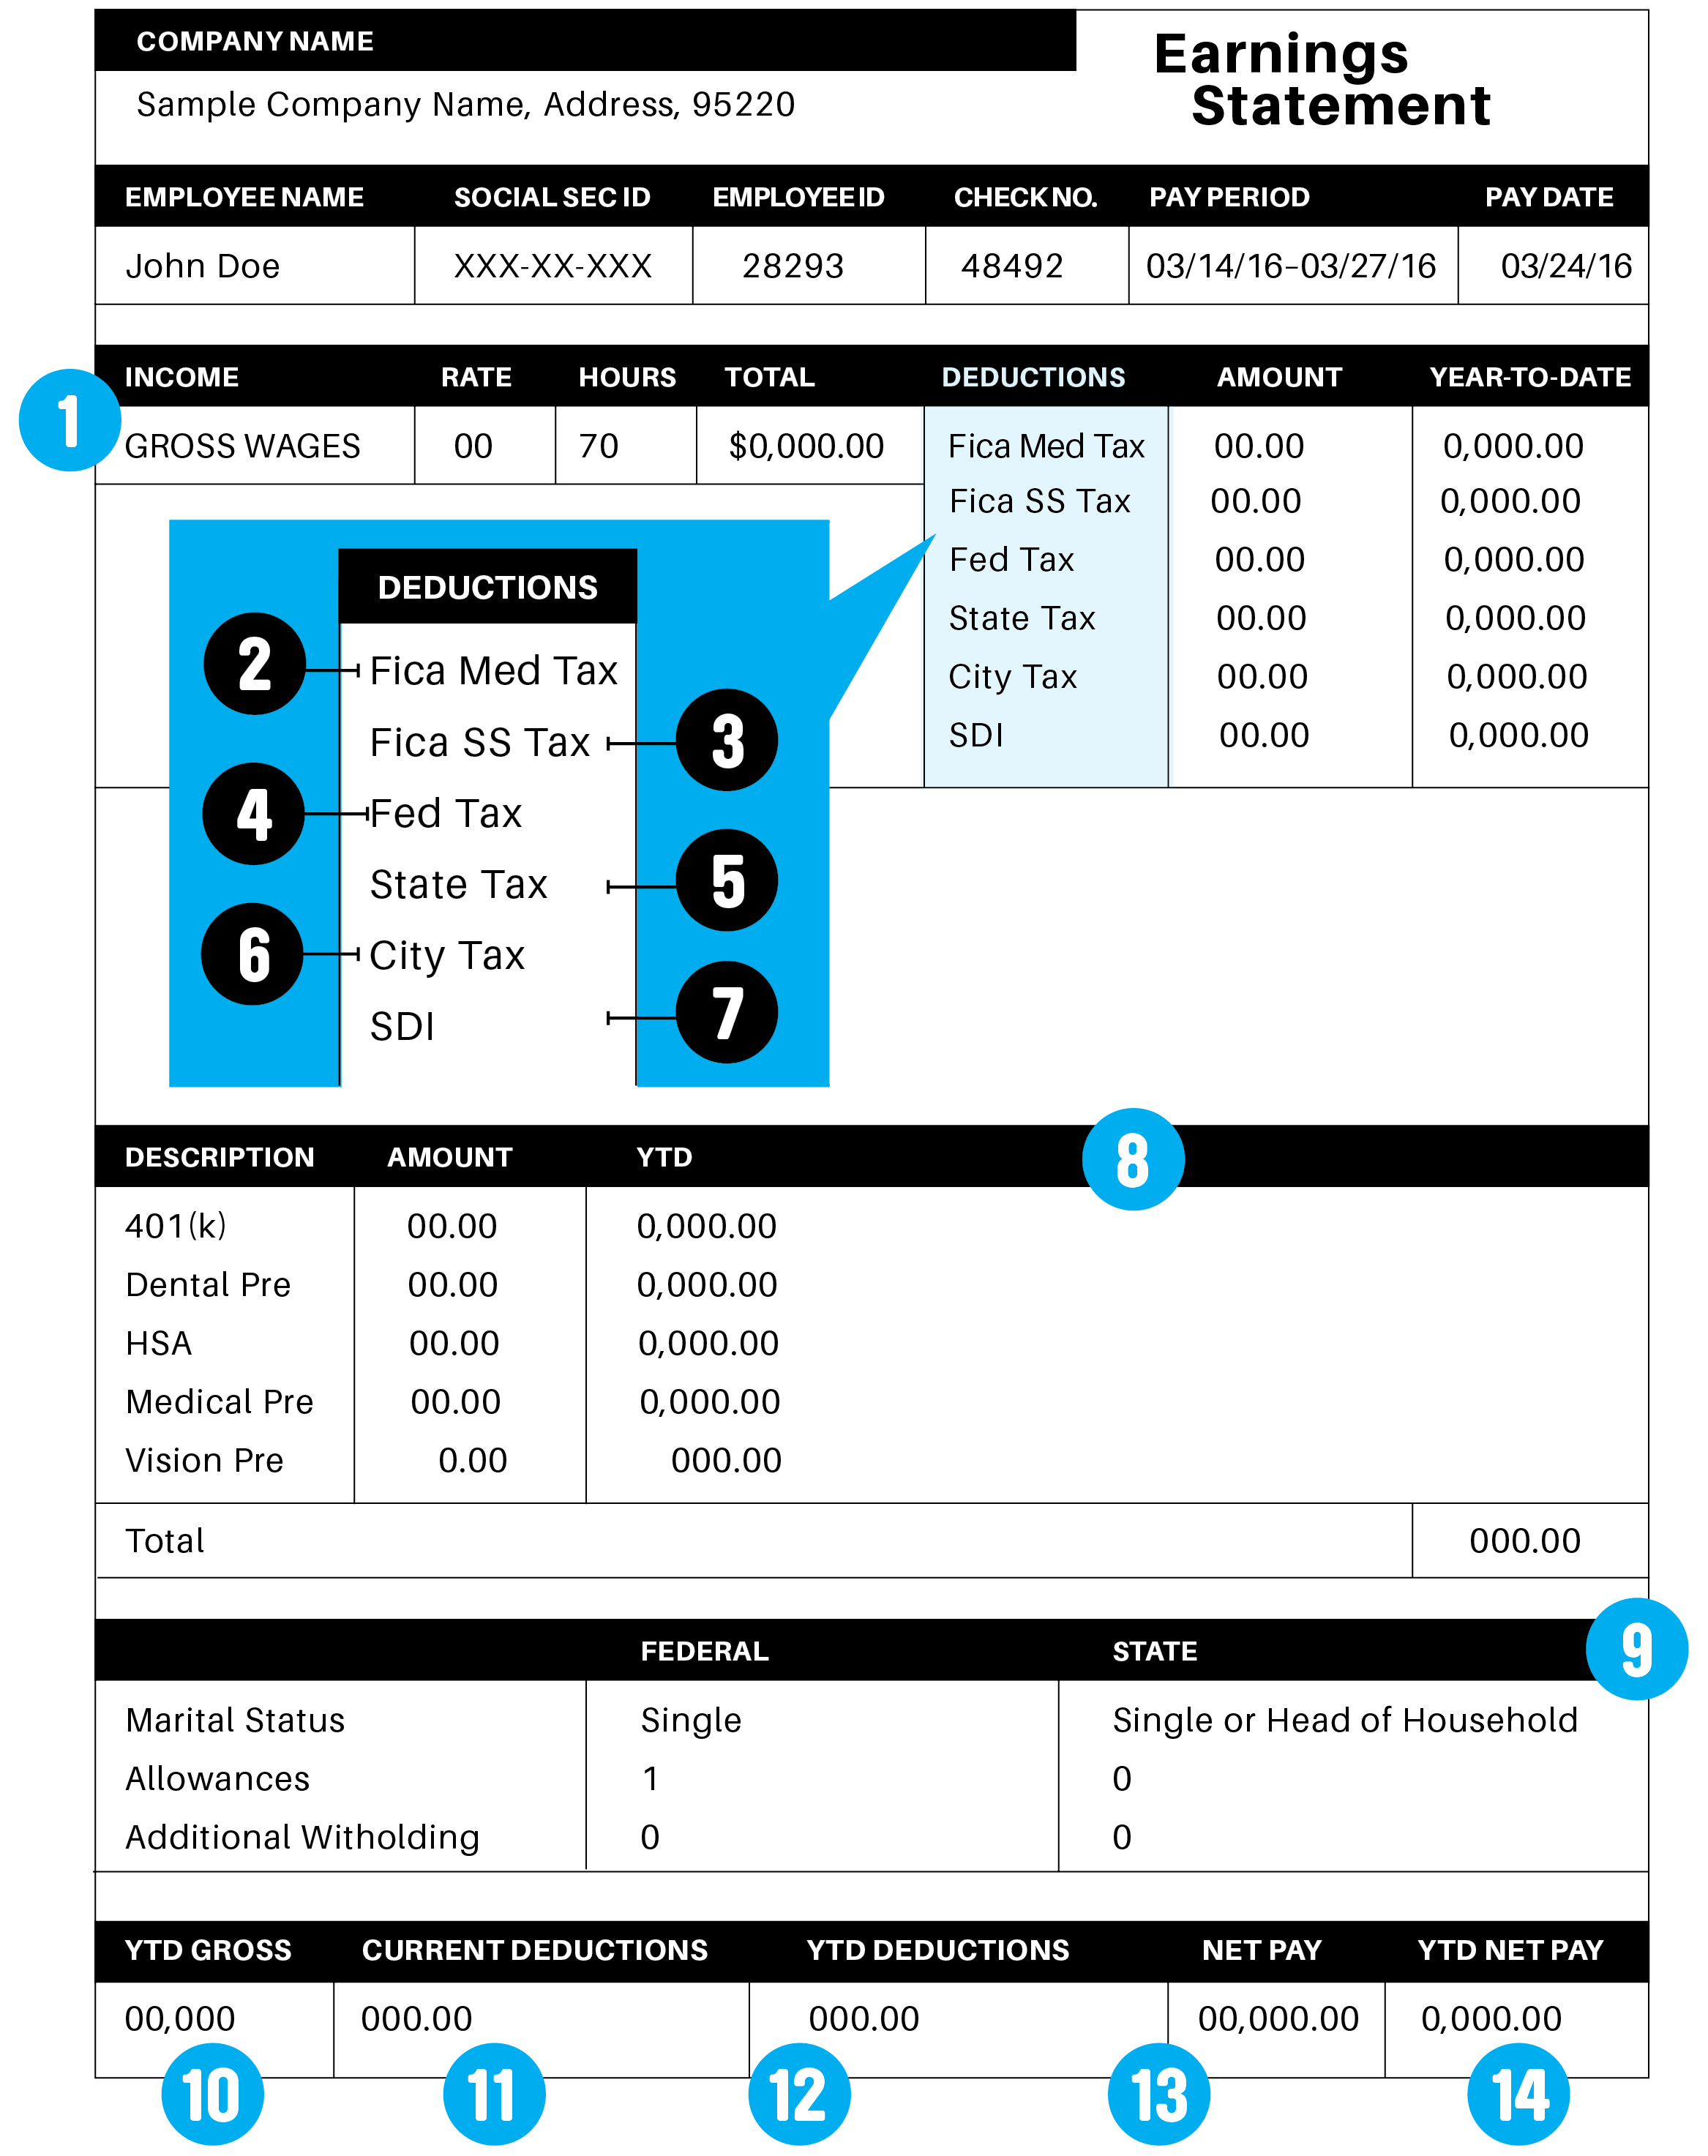
The descriptor on your pay stub depends entirely on how your payroll vendor maps the deduction code. Some systems display Comenity Pay LLC as the full name. Others truncate it to Comenity Capital, and a few show just CP or a numeric code that links back to a deduction table. The variation isn't arbitrary. It's a function of the vendor's configuration and the code your employer entered when setting up the payroll instruction. I've seen the same Comenity obligation appear as nine different descriptors across three separate companies in the same market. In one case, the payroll team used a generic creditor code that looked like an internal memo reference. In another, the full legal entity name was displayed, which made it immediately recognizable to anyone familiar with store credit programs. There is no regulatory requirement for a standardized descriptor format, which means you can't assume two identical deductions will look the same on different pay stubs.
Common Scenarios That Trigger the Deduction
The most frequent cause is a personal loan taken through a Comenity-issued credit product. Some employers partner with Comenity to offer wage-based lending programs where the repayment is automatically deducted from each paycheck. These programs are often marketed as quick access to cash with minimal underwriting. The tradeoff is the deduction sitting on your stub every pay period without much visibility into the total cost. A second scenario involves payroll deduction plans for retail credit balances. A few employers allow employees to set up automatic payments on personal store credit cards through the payroll system. This is less common now than it was five years ago, but it still exists, particularly with companies that have broad benefits platforms. The deduction appears as Comenity Pay because that's the creditor servicing the account. The third scenario, and the one that causes the most confusion, is mistaken identity. Sometimes a merchant transaction or a refund appears near payroll entries on internal reporting systems, and employees conflate the two. If you see Comenity Pay in a section labeled gross earnings rather than deductions, pause and verify the column header before assuming it's a withholding. It could be a reimbursement or a bonus that was routed through a Comenity-linked vendor account for processing, which is an unusual but documented edge case.
What to Do If You Don't Recognize the Charge
First, check the deduction amount against any active loan or credit account statements you have. Log into your Comenity account if you have one and pull the payment history. The deduction amount should match a scheduled payment. If it doesn't, or if you have no Comenity account at all, contact your payroll department with a copy of the pay stub. They can pull the deduction setup record and show you the authorization on file. If payroll says no authorization exists, request a formal dispute through your employer's payroll vendor. The vendor can suspend the deduction while the investigation runs. Most vendors process this within one to three pay cycles. Do not ignore the line item hoping it disappears. Payroll deductions of this type do not self-resolve. They continue until manually stopped or until the underlying obligation is paid off. In one case I handled, an employee's Comenity deduction was still active after they claimed the account was closed. The creditor had reported the account as satisfied, but the payroll authorization had never been terminated. The deduction kept pulling money into a dormant account. The workaround was filing a stop-payment instruction with payroll and providing documentation from Comenity showing the account closure. It took two pay periods to clear, but once the paperwork was in the system, the deduction stopped completely. Keep copies of everything you submit. Payroll departments rarely acknowledge lost emails.
Verification Steps That Actually Work
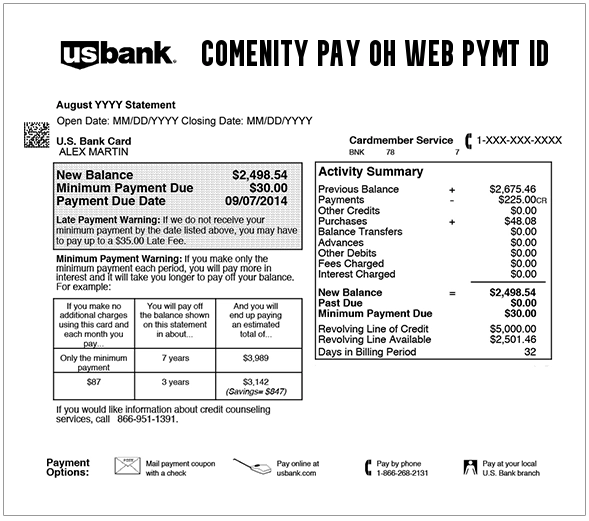
Pull your full pay stub, not the summary email. The detailed version includes the deduction code and sometimes a creditor reference number that the summary omits. Cross-reference that code with your employer's deduction master list, which HR or payroll should maintain. If your company doesn't have one publicly available, request it. Legitimate employers keep this on file for audit purposes. Then verify against your own financial records. Log into any Comenity accounts you hold, check your credit report for Comenity-related tradelines, and compare the deduction amounts. If everything aligns, the mystery is resolved. If there's a discrepancy, the gap between your records and the pay stub is where the problem lives, and that gap is what you take to payroll or the creditor.
Limitations to Be Aware Of
Payroll deduction tracking through Comenity has real bottlenecks. The system does not provide real-time balance updates to employers. Your payroll team cannot tell you your remaining loan balance or your next payment date. They only know the amount scheduled for deduction and the authorization end date, if one exists. If you need balance information, you go directly to Comenity, not to HR. Another limitation is the delay in stopping deductions. Even with a signed revocation form, most payroll vendors require the instruction to be received before the cutoff date for a given pay cycle. If you miss that window, the deduction runs for the next cycle regardless. Plan accordingly if you're paying off a Comenity loan early and want to stop the automatic withholding. Submit the revocation at least ten business days before your next expected deduction date to avoid an overpayment. The final limitation is that Comenity Pay as a descriptor gives you almost no useful information beyond the creditor name. It doesn't tell you the account type, the original loan amount, or the interest rate. For that, you need your own account statements or a credit report pull. The pay stub is a record of the transaction, not a disclosure of the terms. Treat it as such.