Understanding ACH Credits from Navy Federal
ACH stands for Automated Clearing House. It is the network that moves money between bank accounts in the United States. Navy Federal Credit Union uses this system for inbound payments like payroll, government benefits, and vendor payouts. An ACH credit means someone else initiates the transfer and Navy Federal receives it into your account. You do not authorize each transaction individually after setup. The originator does that. Most people think direct deposit just means getting paid faster. That is only part of it. The real cash flow benefit comes from predictable timing and reduced float. When your employer sends payroll via ACH credit, Navy Federal typically posts it on the expected date, sometimes before the business day even starts. I have seen funds available as early as 6 AM local time on deposit day, which matters when you have bills due that same morning. The mechanics are straightforward. Your employer or the payment sender collects your routing and account number from Navy Federal. They submit the batch through the ACH network. Navy Federal receives the file, validates the account, and credits it. Standard ACH processing takes one to two business days for most transactions. Direct deposit payroll often qualifies for same-day ACH, which is why your paycheck arrives faster than a paper check ever could.
One thing beginners miss is that ACH credit timing depends on when the sender submits their batch, not just Navy Federal's processing speed. If your employer runs payroll on Friday afternoon for a Monday payout, the file might not hit the ACH network until Monday morning. That pushes your actual deposit to Tuesday in some cases. I learned this the hard way when I restructured my bill payment schedule around expected Monday deposits and had a rent payment bounce because the funds did not arrive until Tuesday evening. Now I ask my payroll department exactly when they submit batches, and I build a buffer into my personal cash flow calendar. There is a nuance most people do not realize. Navy Federal offers early direct deposit on qualifying ACH credits, which can make funds available up to two business days before the scheduled posting date. This is not automatic for every transaction type. It applies mainly to repeat payroll deposits from the same originator. Government benefit deposits like Social Security usually follow standard ACH timing because those networks control the posting schedule. You cannot request early credit on every incoming payment and expect it to happen. Another practical detail involves the difference between when a deposit shows as pending and when it is actually available. ACH credits often appear in your account activity within hours of submission, but the available balance may not reflect those funds until the settlement completes. I have watched people spend money that showed up in their online balance only to get charged overdraft fees when the ACH transaction reversed or delayed. Always check available balance, not just current balance, before relying on incoming ACH funds for an outgoing payment.
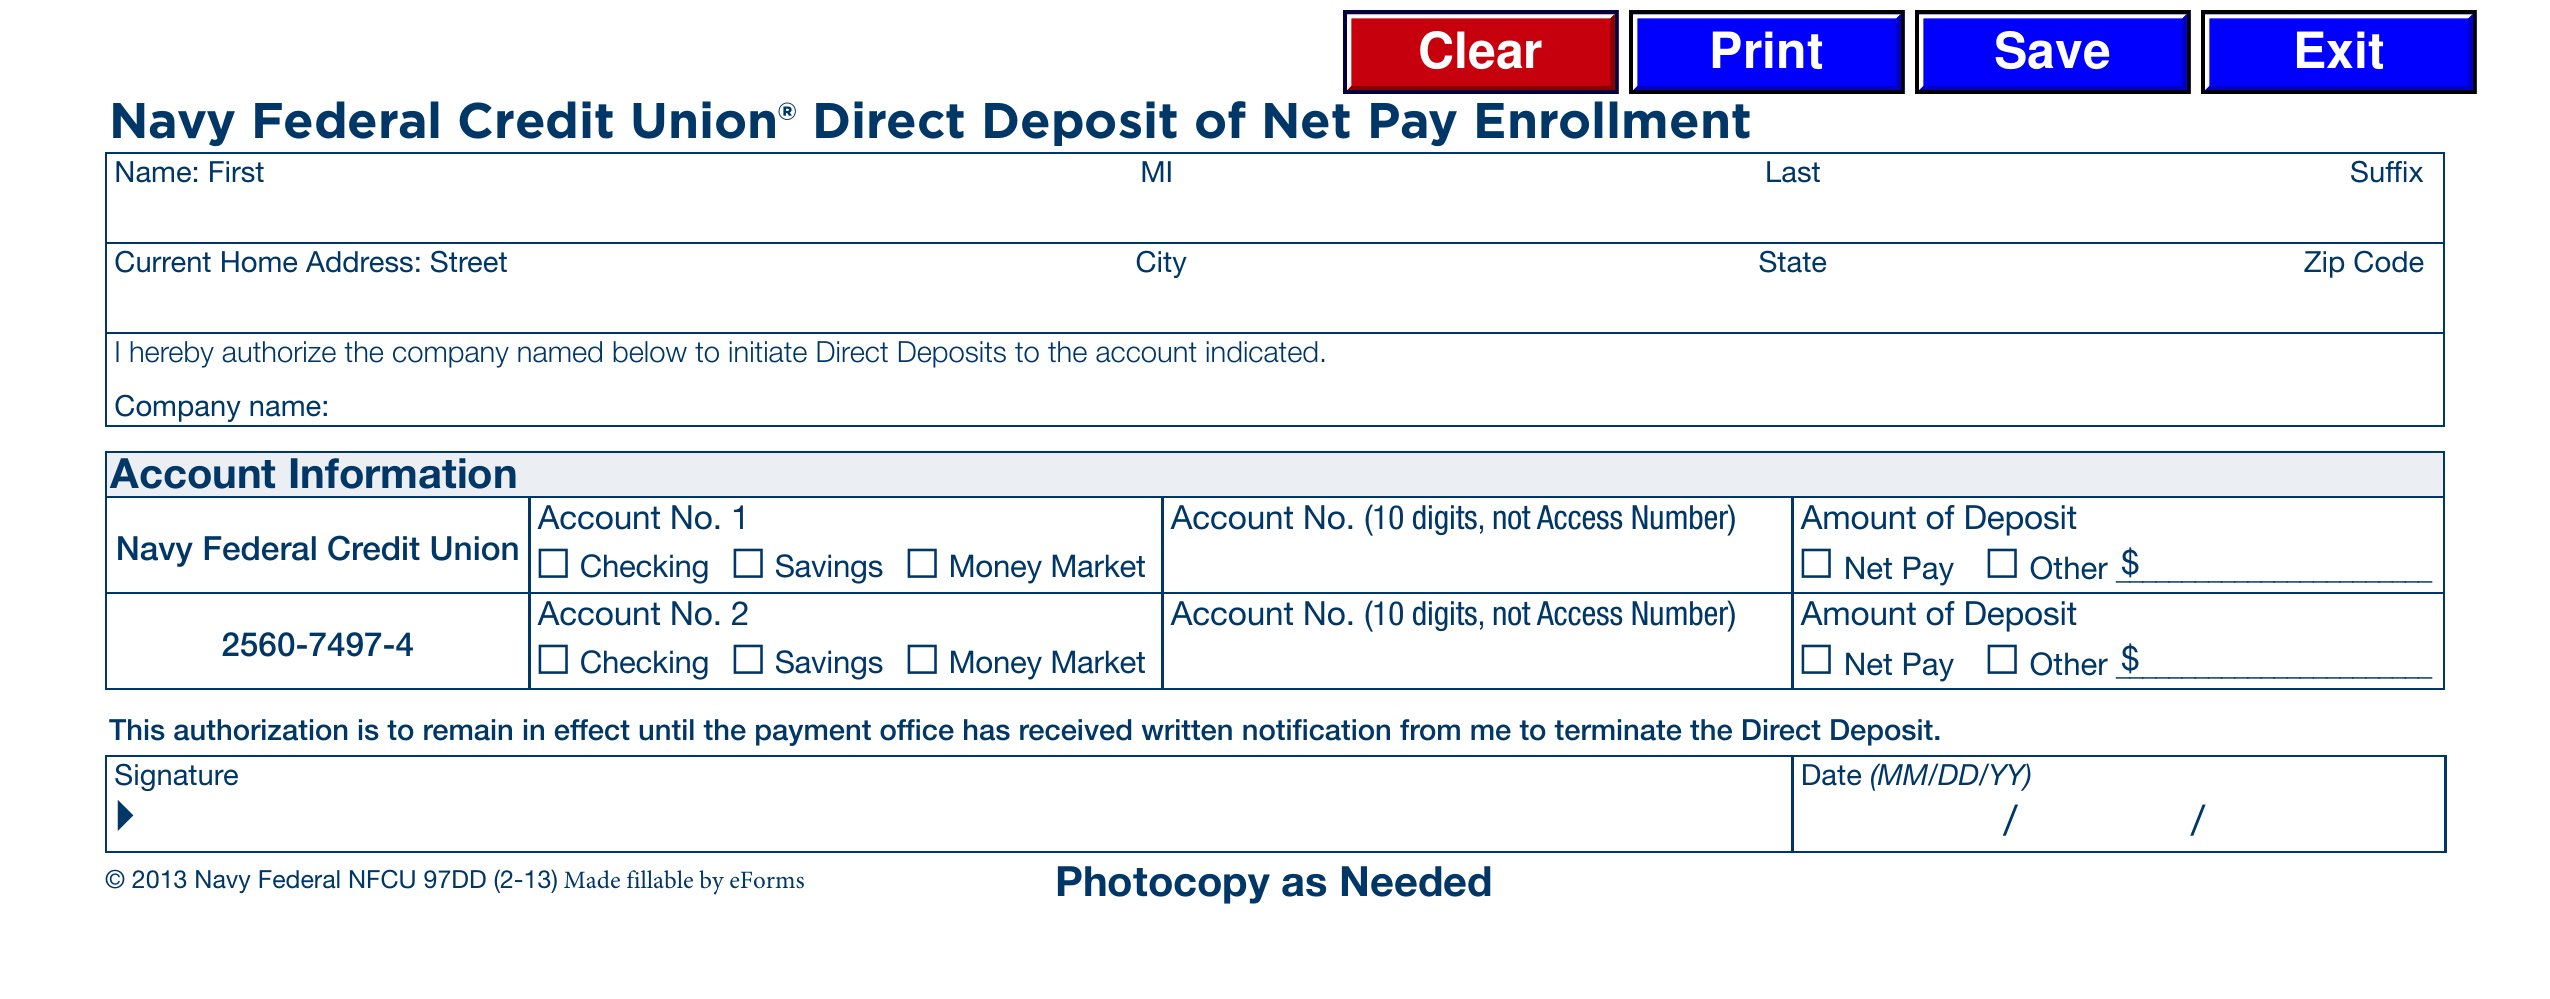
If you want to set up ACH direct deposit with Navy Federal, you need your routing number and account number. Navy Federal routing numbers vary depending on whether you are dealing with wire transfers or standard ACH transactions. For ACH credits, the standard nine-digit routing number is what matters. You can find this on Navy Federal's website or on your account statement. Give those details to your employer's payroll department or the organization sending recurring payments. They will likely send you a direct deposit authorization form to sign, either electronically or on paper. Processing that authorization usually takes one to three business days before your first deposit arrives. There are some downsides to factor in. ACH credits are not instant. Even with same-day ACH availability, there is a window where something can go wrong. An incorrect account number results in a returned transaction, which can delay your deposit by several business days while the originator corrects the information. Navy Federal does process return notifications, but you are still waiting. There is also a limit to how quickly you can access funds in some cases. While Navy Federal generally makes direct deposit payroll funds available immediately upon posting, other ACH credit types like tax refund deposits or business-to-consumer payments may have holds depending on account history and transaction patterns. The biggest limitation is that you cannot reverse or recall an ACH credit once it posts to your account. If someone sends money to your Navy Federal account by mistake, getting it back requires either the sender initiating a return request through their bank or you contacting Navy Federal to coordinate with the originator. This process is not fast. It can take five to ten business days minimum, and there is no guarantee the funds will be retrieved if the originator disputes the return. This is why verifying your account details with any sender is critical before they submit their batch.
Get the Full Details
For people managing tight cash flow, combining early direct deposit with Navy Federal's mobile check deposit and bill pay tools creates a more reliable system. I use a simple tracking method where I log every recurring ACH credit I receive, note the expected posting date, and set calendar alerts two days before each one. This prevents surprises when a payment is late or gets sent to the wrong account number. It also helps me negotiate payment terms with creditors because I know exactly when money lands in my account each month.