EBIT Margin Benchmarks: A Practical Look at Industry Norms
EBIT margin is simply operating income divided by revenue, expressed as a percentage. It strips out interest and tax structures so you can compare companies on a cleaner basis. Most people start there and then get stuck on what constitutes a good number, because the answer is entirely dependent on industry dynamics, capital intensity, and stage of growth. A 12 percent EBIT margin is excellent for grocery retail and might be considered weak for software. Understanding the distinction matters more than memorizing thresholds. I spent years building financial models for mid-market companies across varied sectors, and the first mistake I see repeatedly is benchmarking against aggregate numbers without adjusting for working capital cycles. A construction firm and a consulting firm might both report 15 percent EBIT margin, but the construction firm is likely carrying heavy receivables and inventory that the consulting firm never touches. The margin looks identical but the cash generation profiles are completely different.
What Is A Good Ebit Margin Benchmarks Examples
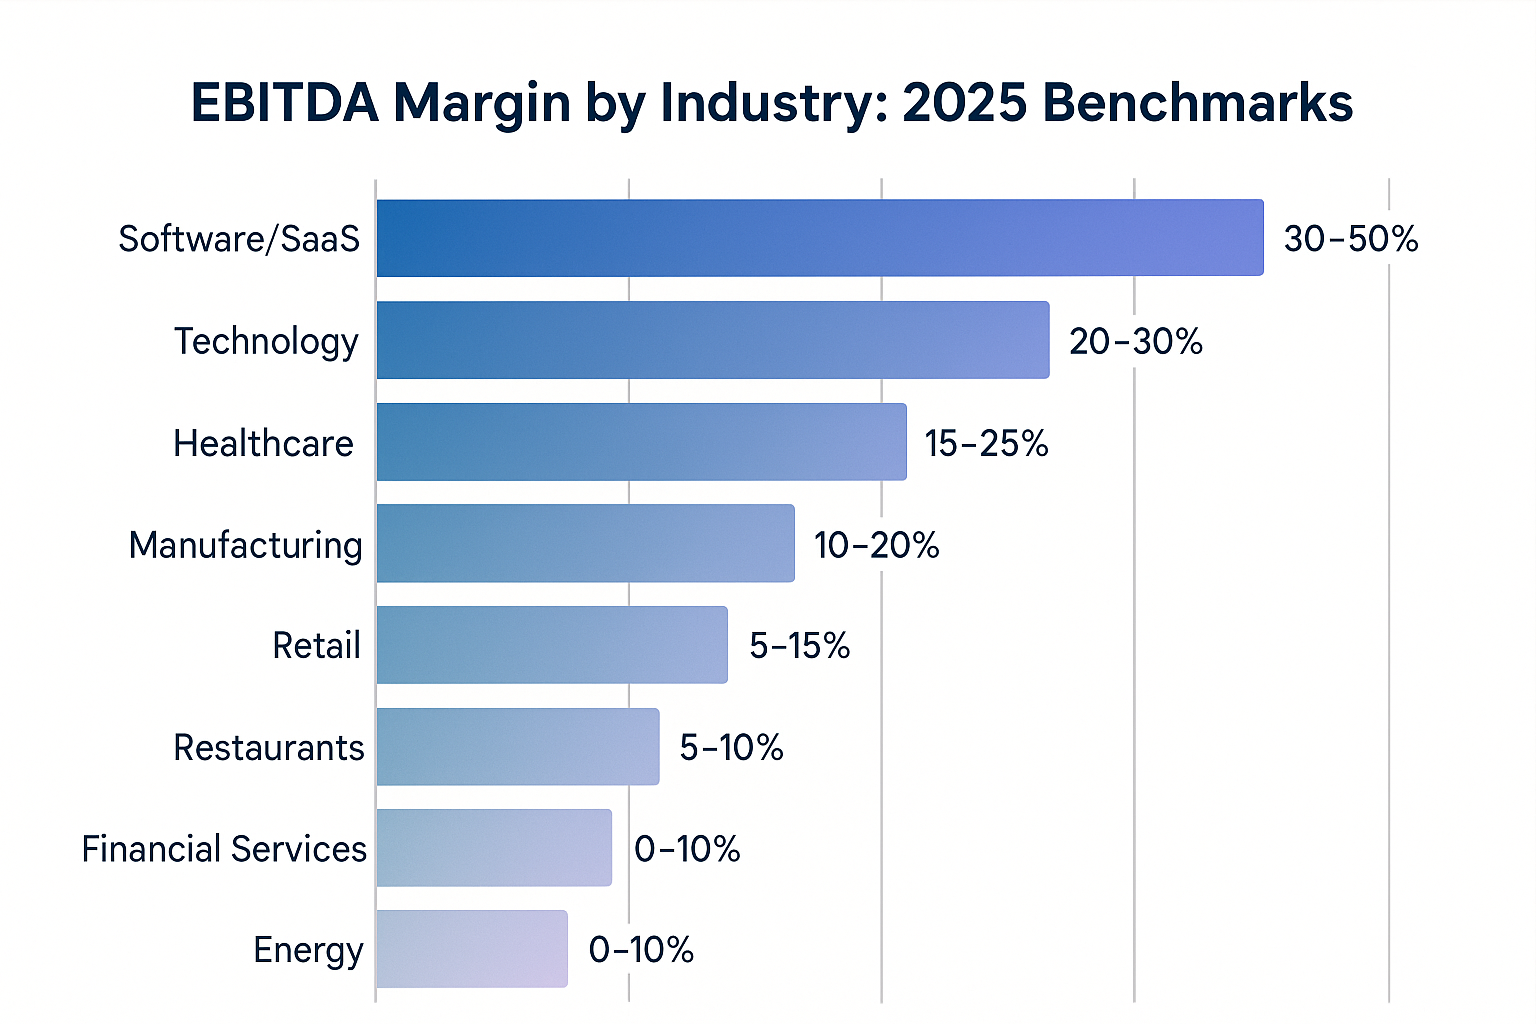
Here are practical benchmarks across typical sectors. These figures represent median ranges observed in public company filings and private benchmarking databases like SBICAP, Damodaran, and S&P Capital IQ over the past several years. They are rough guides, not gospel. Technology and Software: 20 to 40 percent is normal for mature software companies. Cloud-native firms that are still scaling can run negative EBIT margins for years while investing heavily in sales and infrastructure. A company like Salesforce or Adobe routinely posts above 30 percent. Startups in this space should not be judged by EBIT margin at all in their early years. Revenue growth rate and net dollar retention are far more relevant signals until they reach a stable growth phase. Manufacturing and Industrial: 8 to 15 percent is typical. Heavy equipment manufacturers like Caterpillar often hover around 12 to 14 percent. Specialty manufacturing with proprietary technology can push into the 18 to 22 percent range. This sector is highly cyclical, so a 10 percent margin in a trough year does not necessarily indicate structural problems. I once modeled a medium-sized industrial parts supplier that appeared to be deteriorating because its EBIT margin dropped from 14 percent to 9 percent over two years. The real issue was a shift in product mix toward lower-margin commodity parts driven by competitive pressure, not operational decay. We adjusted our benchmarking to look at margin by product line rather than the blended company-wide figure, which revealed the high-margin specialty segment was actually improving.
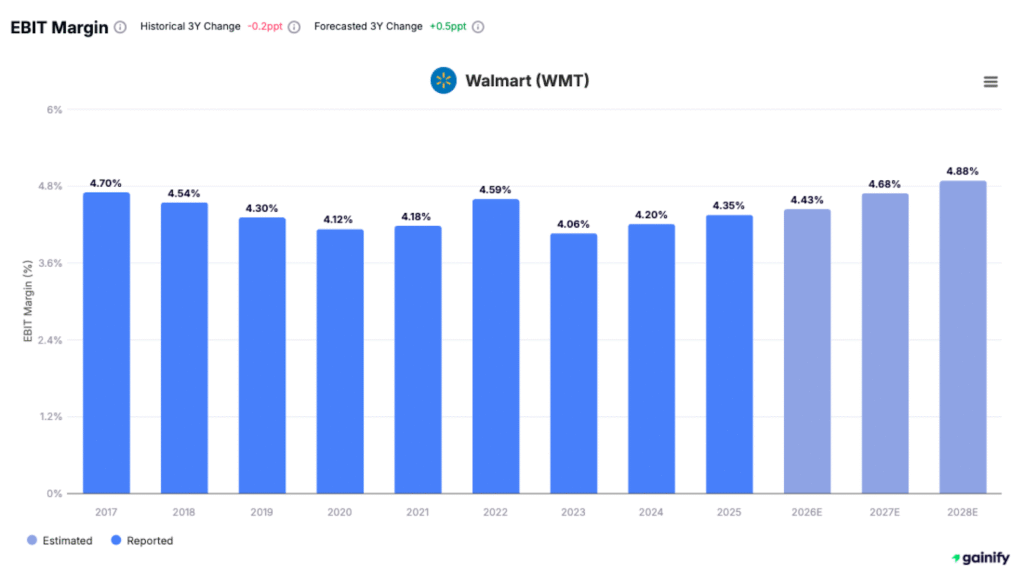
Healthcare and Pharmaceuticals: Pharmaceutical companies commonly post 20 to 30 percent EBIT margins, though this varies wildly depending on patent cliffs and R&D spending cycles. Hospitals and clinics run much lower, often 3 to 8 percent, because labor and regulatory costs dominate. Medical device manufacturers typically land between 15 and 25 percent. The key nuance here is that R&D is expensed under most accounting frameworks, which depresses EBIT for innovative drug companies relative to their cash-generating potential. Adjusted EBITDA is frequently used in this sector for exactly this reason, though it introduces its own distortions. Retail and Consumer Goods: Grocery and mass merchandisers operate on razor-thin margins, usually 2 to 5 percent EBIT. That is why volume and working capital efficiency are the primary drivers of shareholder returns. Specialty retail and branded consumer goods can achieve 8 to 15 percent. A company like Nike or Lululemon regularly reports above 13 percent. The counter-intuitive point for retail analysts is that a dropping EBIT margin is not always a red flag if it coincides with strategic store expansions or market share gains. I reviewed a regional grocery chain that saw its margin compress from 4.2 percent to 3.1 percent during a three-year renovation cycle. Revenue grew 22 percent over that same period, and the new formats ultimately drove the margin back above 4 percent within two years of completion. Professional Services: Law firms, accounting firms, and management consultancies typically range from 15 to 30 percent. Billable utilization rates and partner compensation structures are the main variables. These firms have low capital requirements, which means EBIT margin is a fairly reliable indicator of operational health, unlike capital-intensive sectors where it can be misleading.
Get the Full Details

Energy and Utilities: Oil and gas integration companies fluctuate enormously with commodity prices. During high-price environments, EBIT margins can exceed 25 percent. In downturns, they can go negative. Utilities are regulated and typically stable in the 10 to 18 percent range, with margins constrained by rate-case economics rather than operational efficiency. Benchmarking energy companies requires explicit commodity price assumptions. Comparing an EBIT margin from 2022 to one from 2020 in the oil sector is essentially meaningless without normalizing for price. Financial Services: Banks and insurance companies are generally not analyzed using EBIT margin. Their capital structures and regulatory environments make this metric unreliable for cross-company comparison. Revenue models are fundamentally different, with interest income and underwriting premiums creating distortion. Use risk-adjusted return on capital or combined ratios instead. One practical tip that rarely gets mentioned: when comparing EBIT margins across peers, normalize for lease accounting. After ASC 842 and IFRS 16, operating leases are now on the balance sheet, but the expense recognition pattern differs from company to company depending on when they adopted and how they structured their leases. Two companies in the same industry can report different EBIT margins purely because of lease timing differences, not operational performance. Checking the notes to the financial statements for lease-related expenses helps reconcile this, though it adds work to the analysis.
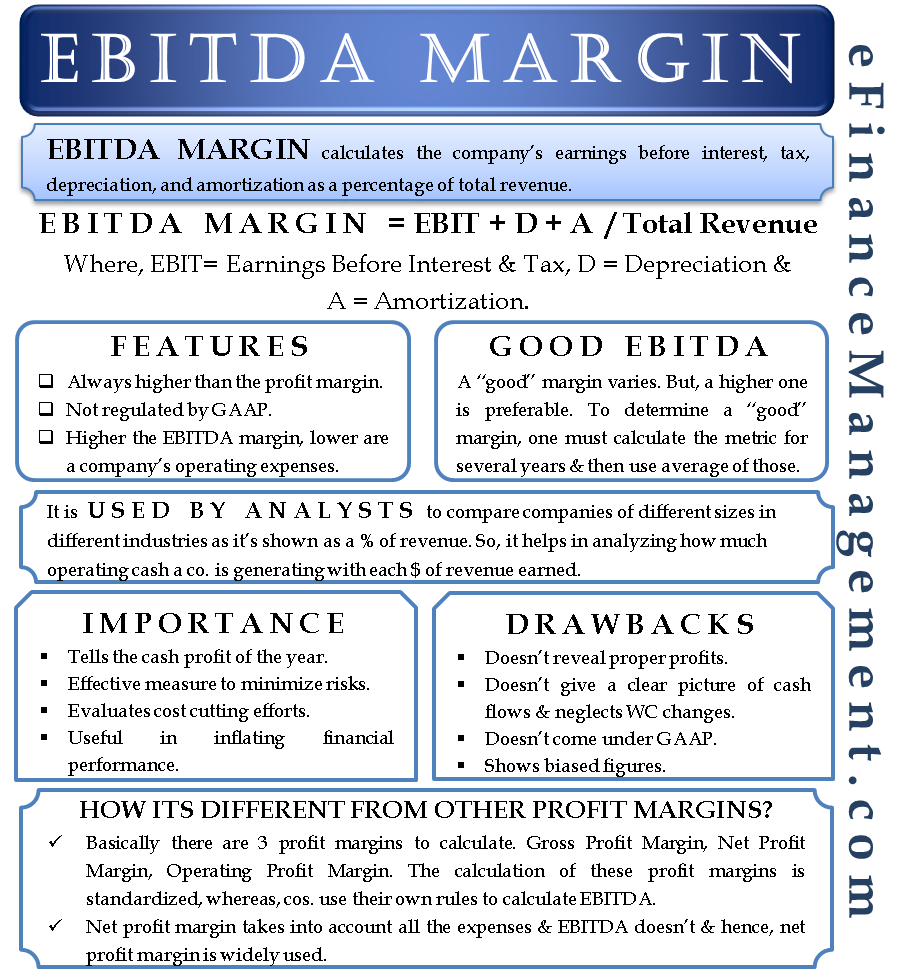
The bigger limitation of EBIT margin as a benchmark tool is that it does not account for differences in depreciation schedules. A company that recently invested heavily in new equipment will show depressed EBIT compared to a competitor with older, fully depreciated assets, even if their underlying operations are identical. This is especially relevant in telecommunications, airlines, and manufacturing. Adjusting EBIT to add back depreciation, which is essentially EBITDA margin, can provide a cleaner comparison in these cases. However, EBITDA has its own problems, particularly in capital-intensive businesses where replacement capital expenditure is a real and unavoidable cash outflow. Ignoring depreciation entirely overstates sustainable earnings capacity. If you are building a comparison model, I recommend calculating EBIT margin for each peer over at least three to five years rather than relying on a single year. One-year snapshots are easily distorted by one-time charges, restructuring costs, or acquisition accounting adjustments. A rolling average smooths out noise and reveals the true underlying trend. For private company benchmarking, sources like Thrivespace, BizBuySell, and industry-specific trade publications provide useful reference points, though the data quality varies considerably. Ultimately, a good EBIT margin benchmark is not a single number you memorize. It is a range derived from peer companies that share similar business models, geographic markets, and growth trajectories. The margin tells you something real about operational efficiency, but only when you understand what else is happening beneath the surface.