Working Out Your Hourly Rate and Take-Home Pay From a £47,000 Salary
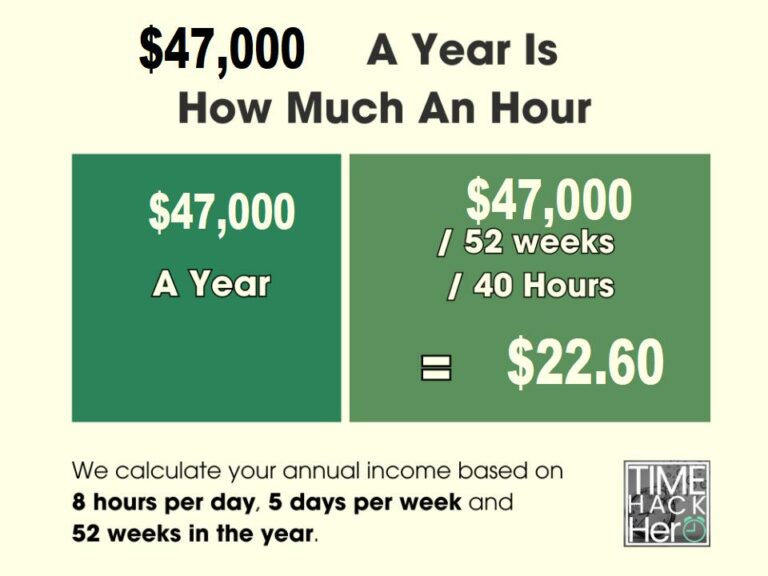
I remember the first time I had to explain this to someone in a forum. They'd been offered a £47,000 role and immediately panicked about what actually lands in their bank account each month. The gross figure looks generous until you start peeling back the layers of tax, national insurance, and pension contributions. I walked them through it step by step, and honestly the same process applies whether you are in the UK, Scotland, or anywhere else with a progressive tax system. The question breaks down into two separate calculations. First, what does your hourly rate look like before and after deductions? Second, what is your actual take-home pay once everything has been stripped out? Let me walk through both. Starting with the hourly rate. If you earn £47,000 per year and work a standard 37.5 hour week, which is pretty typical for full-time roles in the UK, you divide the annual figure by 52 weeks and then by your weekly hours. That gives you roughly £24.10 per hour on a gross basis. Some people use 40 hours instead, which drops the figure to about £22.60. The difference matters when you are comparing job offers or trying to decide whether freelance rates are actually competitive.
Now the harder part. Take-home pay depends on where you live, your tax code, whether you have a student loan, and your pension arrangements. For a basic rate taxpayer in England or Wales on a standard 1250L tax code with no student loan, the math looks something like this. Your personal allowance is £12,570, so you only pay income tax on the remaining £34,430. At 20 percent that is £6,886 in income tax annually. National insurance comes next at 12 percent on earnings between £12,570 and £50,270, which works out to roughly £4,443. Add in the 3 percent employee pension contribution if your employer auto-enrols you at the minimum, and you are looking at about £1,410 in pension deductions. Subtract all of that from £47,000 and your gross annual take-home sits around £34,261. Divide that by 12 and you are looking at approximately £2,855 per month, or about £659 per week before any other deductions. On an hourly basis after tax, that drops to roughly £17.60 for a 37.5 hour week. I ran into a specific edge case once that caught almost everyone off guard. A reader from Scotland asked about the same £47,000 salary, and the numbers looked completely different because Scotland sets its own income tax bands. The basic rate kicks in at a lower threshold, and the higher rate starts sooner. Their actual take-home was about £800 less per year than an English counterpart on the same gross salary. I had to go back and recalculate everything using the Scottish bands, and it highlighted how much geography matters in these calculations.
There are a few things people consistently miss when they try to work this out themselves. The first is that your tax code can change during the year if your circumstances shift. If you start a second job or your personal allowance gets adjusted, your hourly take-home rate fluctuates without warning. The second is that some deductions like salary sacrifice schemes for car rentals or cycling equipment actually reduce your gross pay before tax is calculated, which can lower your national insurance bill but also reduce your pension contributions and state benefit entitlements. It is a trade-off that rarely gets explained properly. Another counter-intuitive point is that the 20 percent basic rate does not apply to your entire salary. Only the portion above your personal allowance gets taxed at that rate. Everything below £12,570 is completely tax-free. This means your effective tax rate on a £47,000 salary is closer to 16 percent, not 20 percent. People often assume the marginal rate applies across the board, which makes the final figure look worse than it actually is. If you want the most accurate number, you should use HMRC's own tax calculator or run the figures through a proper payslip simulator. Online calculators vary in their assumptions about pension contributions and student loan repayments, and a 5 percent difference in your monthly take-home can add up to nearly £600 a year. I usually recommend running three different calculations and taking the average, especially if you are negotiating a salary offer and need to know exactly what you are working towards.
Get the Full Details

The limitations of this kind of calculation are worth being honest about. You cannot predict every deduction that might appear on your payslip. Childcare vouchers, union subscriptions, workplace pension employer contributions, and even some charitable giving through payroll can shift the final figure. The numbers I have given you are solid estimates for a standard employee, but they will not capture your personal situation perfectly. If you have a complex tax code, multiple income sources, or live in Northern Ireland where the tax bands differ slightly, you should verify the figures through an official source or speak to a qualified accountant who can run the exact calculation for your circumstances. One practical workaround I found useful when helping people with this is to ask your employer for a detailed breakdown of your payslip before you accept an offer. Most HR departments will provide a sample paysheet showing exactly what is being deducted and why. It takes five minutes to request and saves hours of speculation. I learned this the hard way early in my career when I accepted a role based on the gross salary alone and was genuinely surprised by the first payslip I received.
Quick Reference Summary
Gross hourly rate at 37.5 hours per week: approximately £24.10 Tax on £47,000 (basic rate, 1250L code): approximately £6,886 annually National Insurance: approximately £4,443 annually
Pension (minimum 3 percent): approximately £1,410 annually Estimated annual take-home: approximately £34,261 Estimated monthly take-home: approximately £2,855

Estimated hourly take-home: approximately £17.60 These figures assume you are a basic rate taxpayer in England or Wales with no student loan and standard auto-enrolment pension contributions. Your actual numbers may vary depending on your tax code, location, and any additional deductions or adjustments to your employment terms.