Converting an Annual Salary to Hourly and Take-Home Pay
Most people who earn a salary wonder what it actually looks like on an hourly basis, especially when comparing jobs or trying to figure out freelance rates. The math is straightforward but the details matter more than you might expect. A $47,000 annual salary breaks down to approximately $22.59 per hour before taxes, using the standard 2,080-hour work year (40 hours per week times 52 weeks). After FICA and standard federal withholding for a single filer in 2024, the take-home lands somewhere around $18.72 to $19.40 per hour depending on state taxes and deductions. Let me walk through exactly how this works and where people usually get tripped up.
The Basic Hourly Calculation
To convert any annual salary to an hourly rate, you divide by the number of working hours in a year. The most common divisor is 2,080, which assumes a standard full-time schedule with no unpaid time off factored in. $47,000 divided by 2,080 equals $22.596, or roughly $22.60 per hour gross. Some people use 2,000 hours instead, which gives you $23.50 per hour. The difference comes from ignoring the two weeks of typical vacation or holidays. Neither approach is wrong, but they produce different numbers and mixing them up causes confusion when comparing job offers. Stick with 2,080 for consistency unless your employer specifies otherwise. If you're paid biweekly, your gross check is $47,000 divided by 26 pay periods, which comes to $1,807.69 per paycheck. Semimonthly pay (twice a month) gives you $1,583.33 per check, though the exact amount shifts slightly each month because some months have more pay days. This inconsistency is one reason biweekly is generally easier to work with for personal budgeting.
From Gross to Take-Home: The Real Numbers
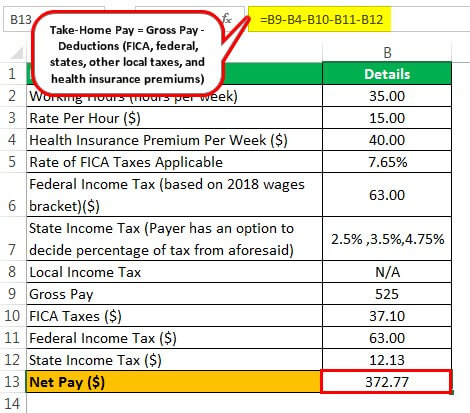
Gross pay is what your salary says on paper. Take-home pay is what actually hits your bank account after everything gets deducted. The gap between the two is where most people lose track. For a $47,000 salary in 2024, here is a realistic breakdown for a single filer with no dependents and no pre-tax deductions beyond the standard withholding: Federal income tax using the standard deduction of $13,850 leaves you taxable at $33,150. At the 12% bracket for that range, federal tax comes to about $3,978 annually, or roughly $153 per paycheck on a biweekly schedule. Social Security tax is 6.2% of gross, which is $2,914 per year. Medicare tax at 1.45% adds another $681. Those three FICA components total approximately $4,595 in mandatory federal deductions.
Get the Full Details
State taxes vary wildly. If you live in a state with no income tax like Texas or Florida, your take-home is higher. In California or New York, expect an additional $1,500 to $2,500 in state withholding annually. Using a midpoint of $1,800 for state tax, your total annual deductions land around $6,395. That puts your annual take-home at approximately $40,605, or about $19.52 per hour after all federal and average state taxes. On a biweekly basis that translates to roughly $1,562 per paycheck before any further deductions. I ran into a specific problem once when a friend was comparing two job offers and the hourly conversion threw him off completely. One job listed $23.50 per hour but required 50-hour weeks during peak seasons. The other listed $22.00 per hour with strict 40-hour weeks. The first looked better on paper, but when you actually multiply it out, the second pays more over a full year once overtime variability and burnout risk are factored in. Always calculate the annual total, not just the headline hourly rate.
Factors That Change Your Take-Home Number
The numbers above assume a very basic scenario. Real life rarely works that way, and several common deductions will shift your take-home pay significantly. 401(k) contributions are probably the biggest factor most people underestimate. Contributing 5% of your gross pay to a traditional 401(k) reduces your taxable income by $2,350 and takes another $2,350 out of each paycheck before taxes apply. Your take-home drops in nominal dollars, but your actual tax liability drops too, and you are building retirement savings. For most people at the $47,000 level, contributing at least enough to get the full employer match is non-negotiable. That usually means contributing 3% to 6% depending on the plan. Health insurance premiums are another major variable. Some employers cover the full premium, others make you pay 20%, 40%, or even 60% of the cost. A typical employee-only health insurance contribution at this income level ranges from $80 to $200 per paycheck. That is $2,080 to $5,200 annually coming straight out of your gross pay.
HSA and FSA contributions also reduce your taxable income. An HSA contribution of $4,150 (the 2024 individual limit) for a high-deductible health plan user would drop your take-home significantly but save you money on taxes and qualified medical expenses simultaneously. If you itemize deductions instead of taking the standard deduction, that could lower your federal tax slightly, though at $47,000 of income the standard deduction almost always produces the better result for most people.

The Hidden Pitfall: Salaried Employees and Overtime
Here is something that catches people off guard. If your $47,000 is a salaried position rather than hourly, you are generally not eligible for overtime pay unless you meet specific exemptions under the Fair Labor Standards Act. The salary level threshold for overtime exemption in 2024 is $36,128, so $47,000 puts you firmly above it. That means if your employer expects you to work 50 hours some weeks, you are effectively earning less per hour than the $22.60 calculation suggests. To calculate your real hourly rate when working more than 40 hours, divide your annual salary by your actual annual hours. Working 50 hours per week for 48 weeks (with two weeks vacation) gives you 2,400 hours. $47,000 divided by 2,400 is $19.58 per hour, which is substantially lower than the standard $22.60 figure. This is the single most important thing to ask about during any salary negotiation: what is the expected weekly hour commitment?
A Quick Reference for Common Scenarios
Single filer, no dependents, no 401(k), no health insurance deduction, moderate state tax: approximately $19.52 per hour take-home, or $1,562 biweekly. Same situation plus 5% 401(k) contribution and $120 monthly health insurance premium: approximately $17.85 per hour take-home, or $1,428 biweekly. Married filing jointly with one income, no children, no additional deductions: approximately $20.15 per hour take-home due to the wider tax brackets and standard deduction for married couples.
Why the Numbers Feel Different From What You Expect
Many people look at their pay stub and cannot reconcile the gross salary with the net amount deposited. The gap feels larger than it should. This is usually because people forget about the pre-tax versus post-tax distinction. Your 401(k) and health insurance come out before taxes are calculated, which lowers your taxable income. But the gross number on your offer letter does not reflect any of those deductions, so the comparison feels unfair even though it is mathematically correct. Another common source of confusion is that some employers calculate hourly rates differently internally. A company might use 2,080 hours for one calculation and 2,000 for another, then claim different effective hourly rates in different contexts. Always verify which divisor they are using if you need to compare across employers or roles. If you want an exact number for your specific situation, the IRS withholding calculator at irs.gov/tools is free and accounts for your exact filing status, state, and any additional withholdings you specify. The quick reference numbers above are estimates based on 2024 tax brackets and average state withholding. They will be close, but your actual take-home depends on your specific circumstances and any changes to tax law that may have occurred.