What Secured Debt Actually Is
Secured debt is a loan where you pledge an asset as collateral. If you default, the lender can take that asset. That is the entire mechanism. Everything else is just paperwork around it. The collateral can be a house, a car, a savings account, or in some cases, equipment or inventory for business loans. The lender holds a lien on the asset until the debt is paid off. The loan itself is recorded in public records in most cases, which is how other lenders can see what you owe against that property. I have sat across from borrowers who had no idea their mortgage had a first-lien position until they tried to refinance and discovered a home equity line of interest was already in place. The system does not stop you from signing paperwork. It just shows up later when the title search happens.
What Does Secured Mean The Definitive Guide To Secured Debt Loans And Credit
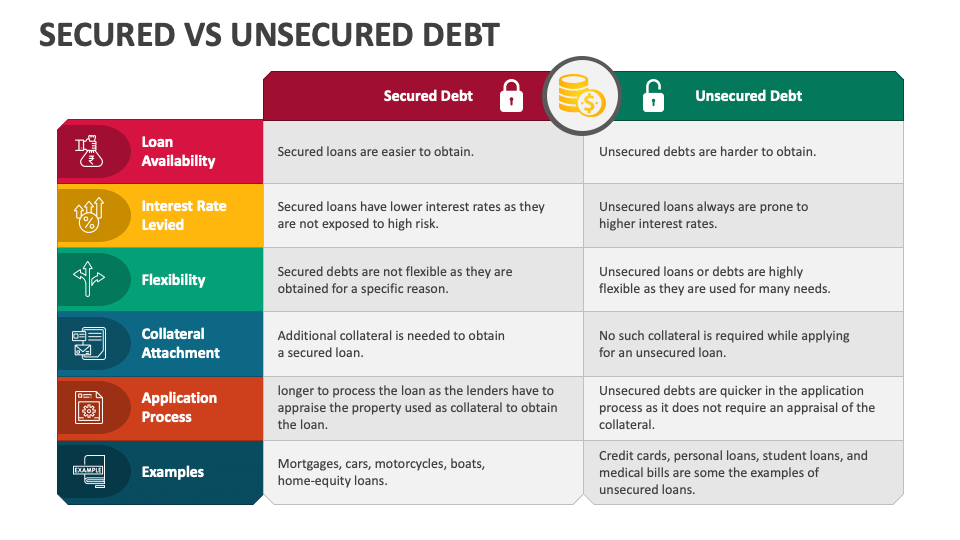
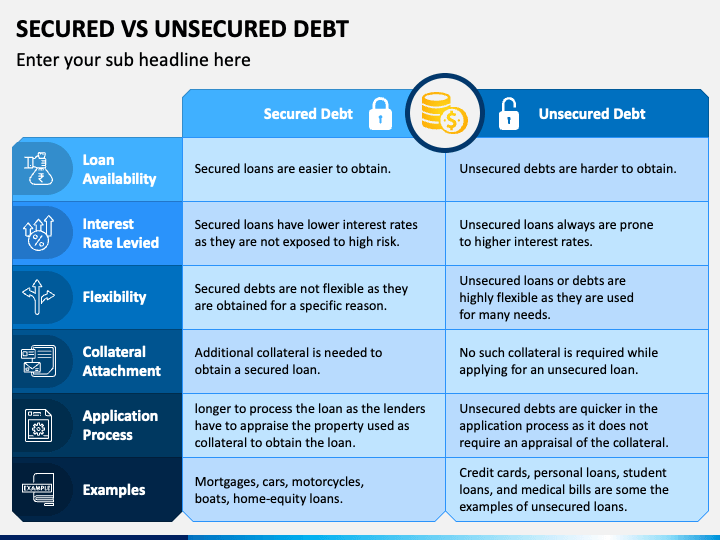
Secured loans generally come with lower interest rates than unsecured debt because the collateral reduces the lender's risk. A mortgage might carry a rate several percentage points below what you would see on an unsecured personal loan. Auto loans sit somewhere in between, typically tied to the loan-to-value ratio of the vehicle. The key metric lenders look at is the loan-to-value ratio, often called LTV. With a home purchase, an LTV of 80 percent means you are putting down 20 percent. Go above 80 percent and you usually trigger private mortgage insurance, which adds to your monthly payment without going toward principal. I had a client once who put 5 percent down on a $350,000 purchase. The PMI alone added $220 a month. She did not factor that in during her budgeting and almost fell behind within six months. With auto loans, LTV works differently. The car depreciates immediately. Lenders often refuse to finance more than the actual cash value of the vehicle. You will see a lot of borrowers rolling negative equity from a trade into a new loan. The lender sees that and either denies the loan or requires a much larger down payment to bring the LTV back into acceptable range.
How Secured Credit Cards Work
A secured credit card is not a special type of card. It is a regular credit card where your credit limit is set equal to a cash deposit you make upfront. Deposit $500, get a $500 limit. Deposit $1,000, get a $1,000 limit. The idea is that you build or rebuild credit history while the lender has zero risk. If you stop paying, they keep your deposit. The mechanics are straightforward, but the industry has found ways to make them more complicated than necessary. I spent an afternoon troubleshooting a situation where a borrower's secured card was not reporting to all three major bureaus. The issuer only reported to two. The borrower needed all three for a mortgage application. We ended up writing a formal dispute to the credit bureaus and sending copies of the issuer's policy documents. It took eleven weeks to resolve. The lesson here is that not all secured card issuers report the same way, and you should verify before you open an account.
Get the Full Details

Some secured cards charge annual fees. Others charge monthly maintenance fees that eat into your available credit. A $25 monthly fee on a $200 limit is a 12.5 percent effective cost before you even pay interest. Always check the fee schedule. The advertised rate is only half the story.
The Conversion Problem
One thing people rarely understand is that converting a secured card to an unsecured card is not automatic. Some issuers do it after eight to twelve months of on-time payments. Others require a formal request. A few will never convert and will only close the account and return your deposit after you pay it off. I ran into a case where a borrower had a secured card for three years, perfect payment history, and never asked about conversion. When they applied for a mortgage, the loan officer asked why there was a closed account with a zero balance on the report. The borrower had no idea the account existed. The issuer had closed it after two years of dormancy because the borrower never called to request conversion. Missing credit history like that can lower a score by fifteen to twenty points in some scoring models. The workaround is simple but most people do not do it. Call the issuer every six months and ask about conversion eligibility. Set a reminder on your phone. It takes ninety seconds and prevents a lot of headaches later.
When Secured Debt Makes Sense
Secured debt works well when you have an asset and need capital that you cannot get otherwise. It also works when the interest rate difference between secured and unsecured is large enough to justify tying up an asset. A home equity loan at seven percent is almost always cheaper than a personal loan at twelve percent for the same borrower profile. The math is clear. But you are risking the house. That is not abstract. If you lose your income, the foreclosure process begins within ninety to one hundred twenty days in most states after you miss payments. I have seen people argue that they would never default and therefore not worry about the risk. That is a flawed assumption. Income loss is unpredictable. Medical emergencies happen. The collateral is real. Secured cards make sense for people with thin or damaged credit files. They are one of the few products that actually report to bureaus in a way that helps those borrowers. But the fees matter. If you can get an unsecured card with no annual fee through a credit union or community bank, take that instead. Secured cards are a bridge, not a destination.

Pitfalls That Are Easy to Miss
One common mistake is using a secured loan to pay off high-interest unsecured debt without addressing the underlying behavior. You might consolidate a $8,000 credit card balance at nine percent into a home equity loan at six percent. You save money on interest, but if you run the credit card back up to $8,000 again, you now have $8,000 in secured debt and $8,000 in unsecured debt. You have doubled your secured exposure with no net improvement in your situation. Another issue is overleveraging against appreciated assets. Home values go up. People see equity and assume it is permanent. It is not. During the 2008 downturn, many homeowners with home equity lines of credit found their borrowing capacity wiped out along with their home values. The LTV ratios that seemed fine in 2006 became impossible to maintain in 2009 when property values dropped thirty percent or more in some markets. I worked with a borrower in 2011 who had taken out a HELOC against appreciated equity during the boom. When the market turned, he could not refinance and the HELOC went into recall. The lender demanded full repayment within sixty days. He had to sell the property at a loss to satisfy the debt. The workaround would have been to keep the HELOC balance conservative regardless of how high the appraised value went. Treat appreciated equity as potential, not as available cash.
The Scoring Impact
Secured debt affects your credit score in specific ways. Payment history is the largest factor, so a secured card with on-time payments helps significantly. Credit utilization matters too. If your secured card has a $500 limit and you carry a $400 balance, that is an 80 percent utilization rate, which will drag your score down. Keep utilization below thirty percent, ideally below ten percent, for maximum score impact. The age of accounts also plays a role. A secured card opened twenty years ago will contribute more to your average account age than one opened six months ago. Do not close old secured cards unless they have high fees. The length of credit history is a real factor in scoring models, and closing accounts shortens it. Hard inquiries from applying for secured products are usually minor and temporary. A single secured card application might drop a score by five to ten points for a few months. Multiple applications in a short period compound that effect. Space out your applications by at least six months if you are rebuilding credit.
Where Secured Lending Fails
Secured lending assumes you have collateral with stable or appreciating value. That assumption breaks down in several scenarios. If you are self-employed with irregular income, lenders may still require documentation that is difficult to produce. Standard W-2 verification does not apply, and many traditional lenders have strict debt-to-income calculations that exclude variable income. Another failure point is when the collateral is illiquid. Equipment collateral is common in small business lending, but selling that equipment in a default scenario can take months and fetch far less than theappraised value. Lenders know this and price it in, which means the rates on equipment loans are often higher than you would expect given the collateral. Thesecured part of the loan does not always mean cheap money. Sometimes the safest move is to avoid secured debt entirely and use an unsecured product with a higher rate, even if it costs more in interest. The math changes when you factor in the risk of losing an asset you need for daily life. A car is not just collateral. It is how you get to work. A house is not just collateral. It is where you live. Those risks are real even if the probability seems low.