Understanding Run Rate Without the Marketing Fluff
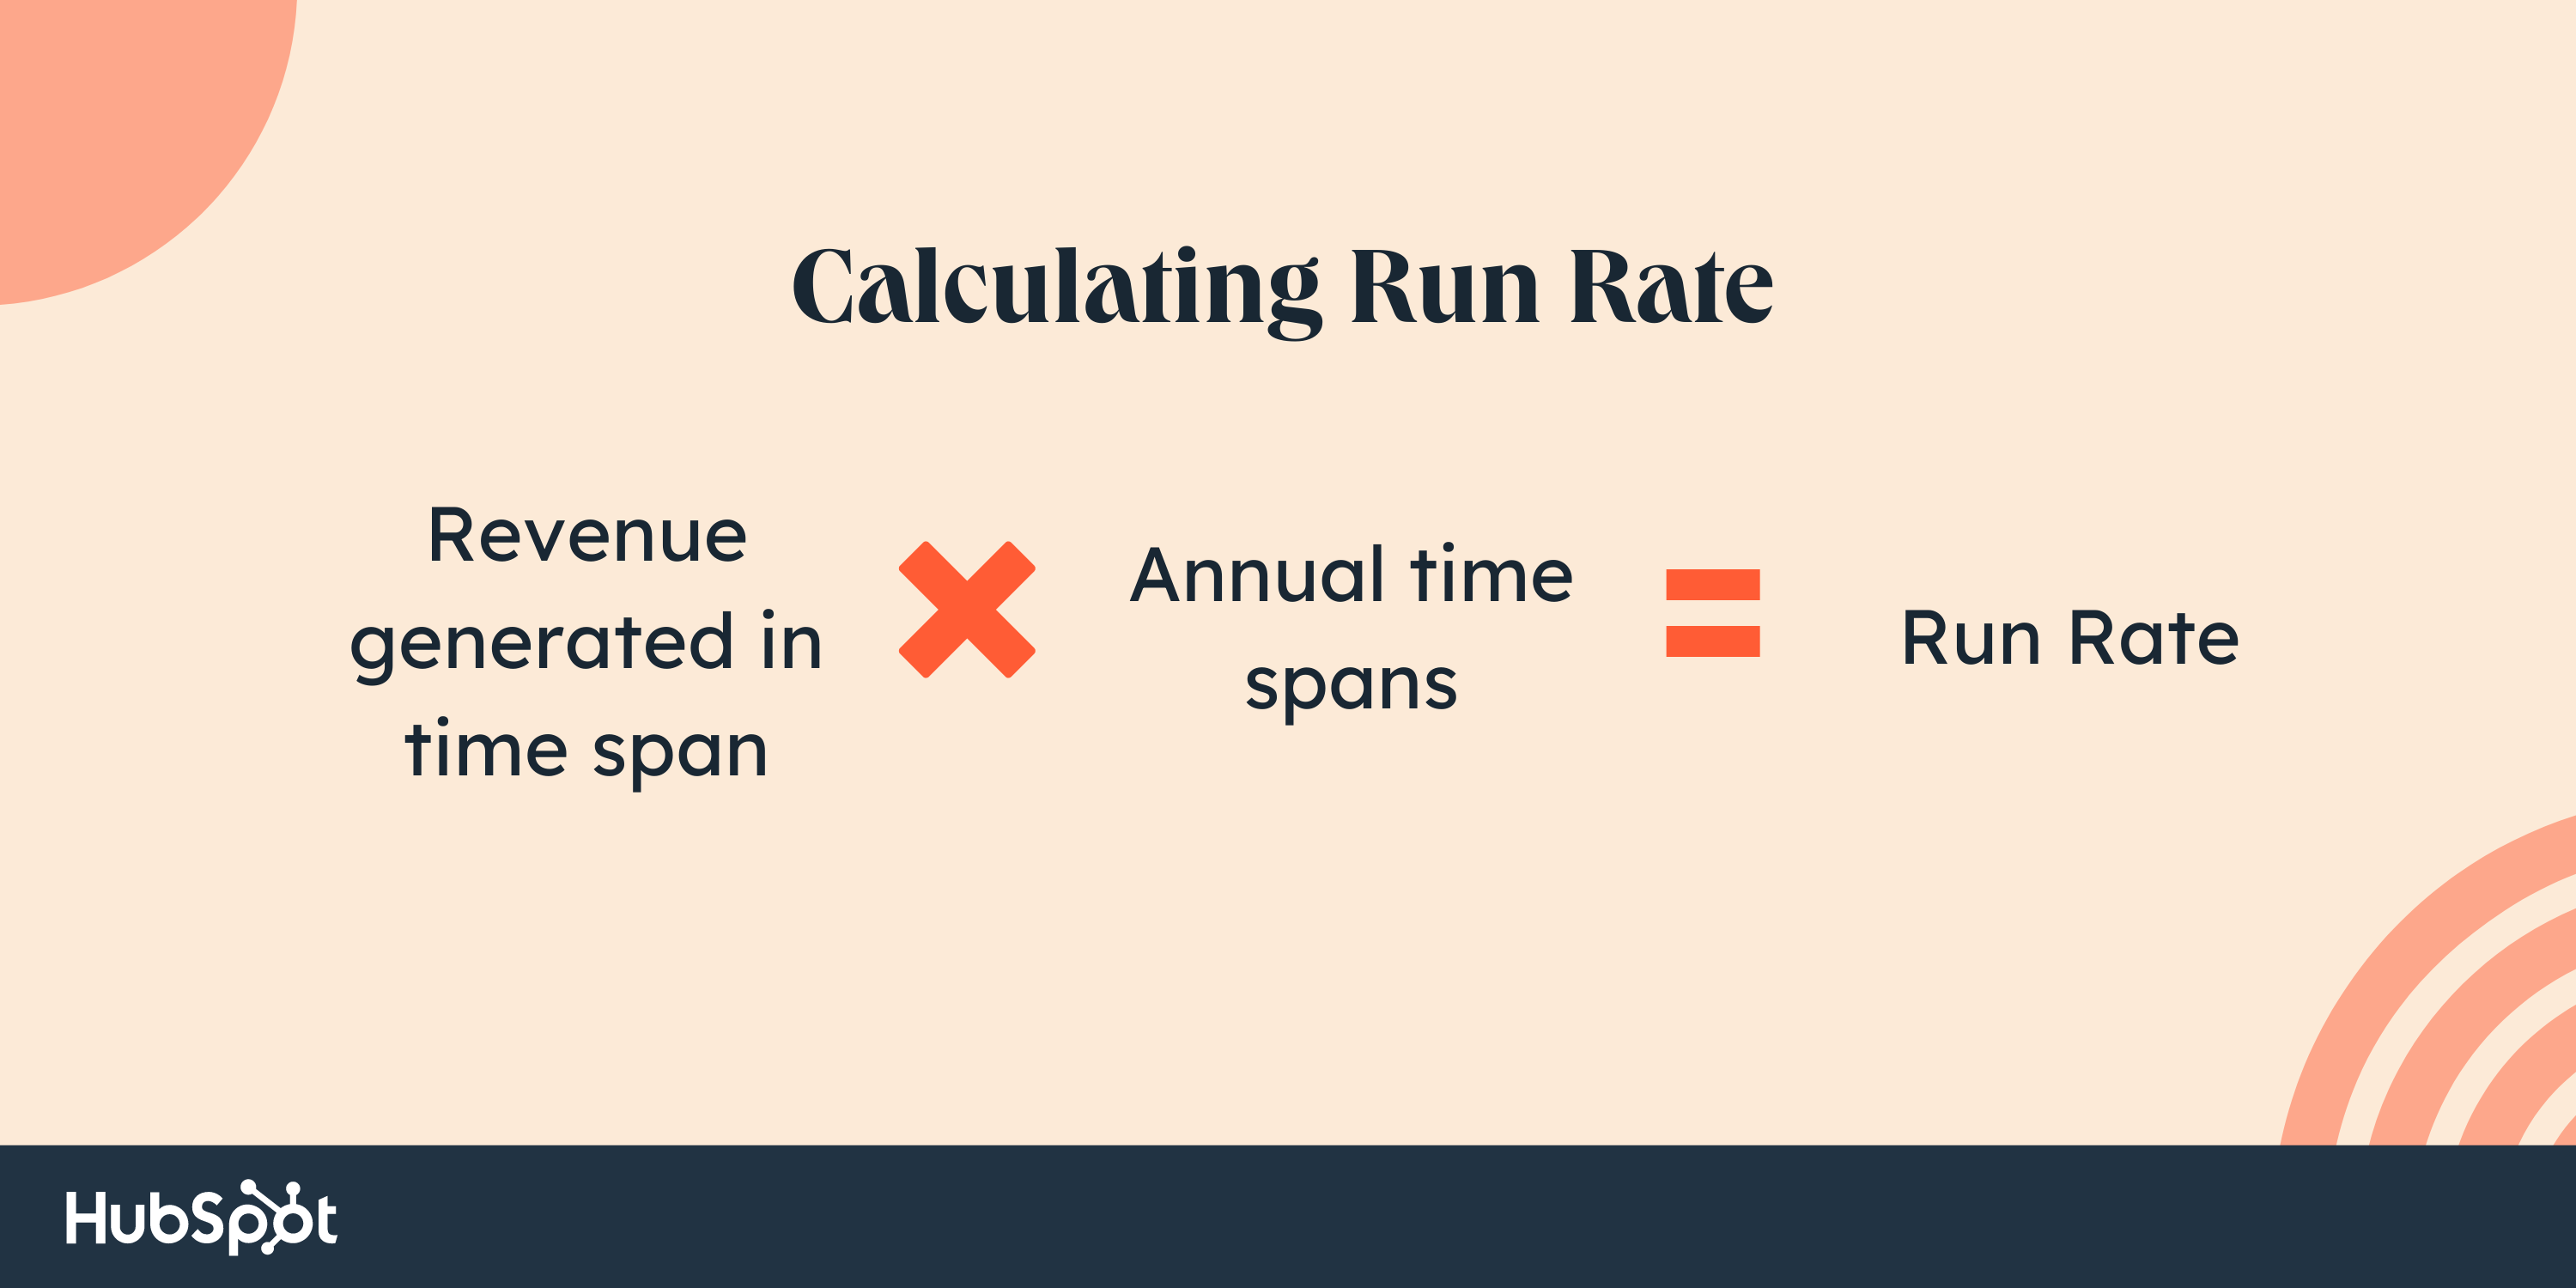
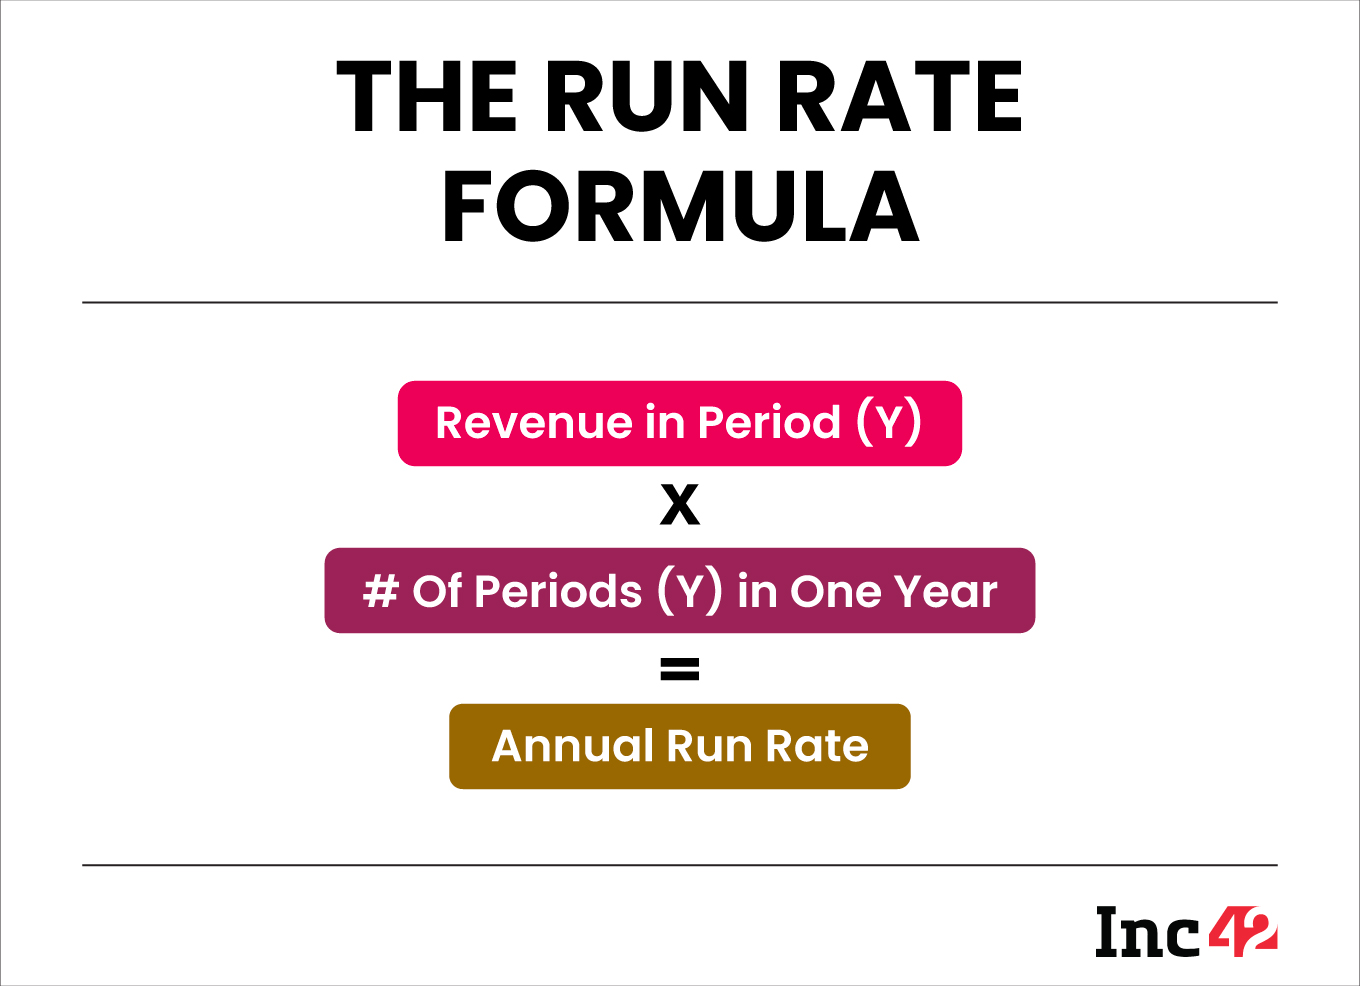
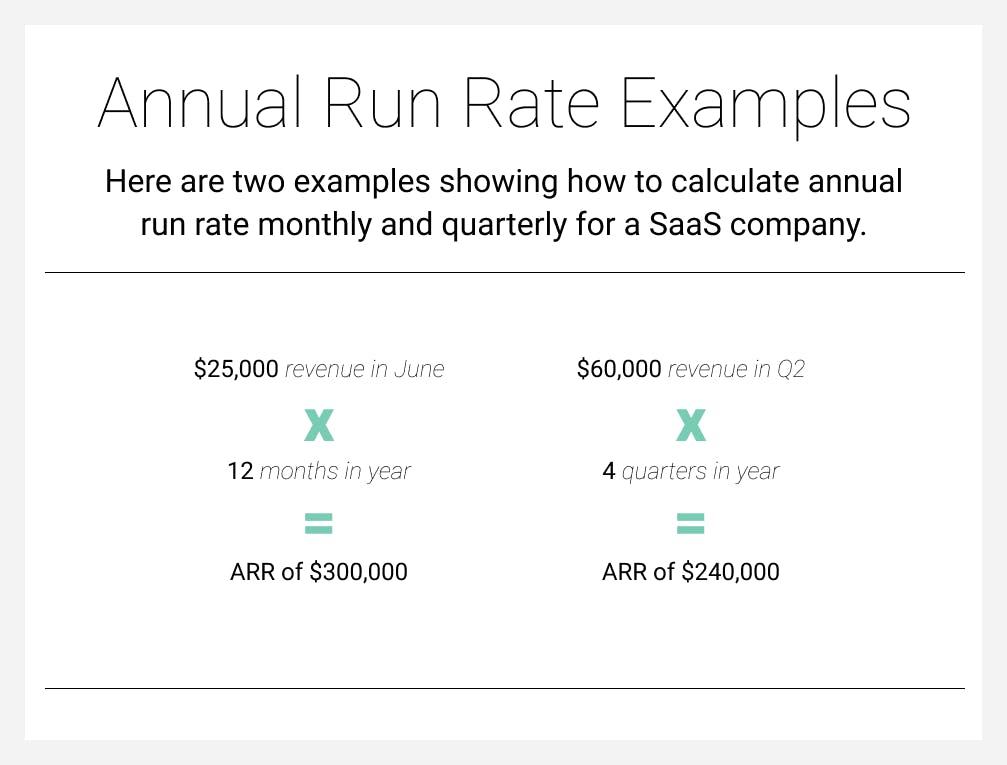
A run rate takes your current revenue for a period and multiplies it to show what the full year would look like if nothing changed. It's a quick projection tool, but it's also one of the most misused metrics in startup finance. People apply it blindly without understanding when it's actually useful. Here's how to use it properly and, more importantly, when you shouldn't. The basic calculation is straightforward. Take your revenue for any given month—say $50,000—and multiply it by twelve. That gives you $600,000. That's your monthly run rate. Some people use quarterly figures instead, multiplying by four. Others prefer a twelve-month trailing average to smooth out anomalies. All three approaches are technically correct depending on context. Where people mess this up is in the assumptions baked into the math. A run rate assumes zero growth, zero churn, and zero seasonality. If any of those conditions are false, your projection is wrong. Not slightly wrong. Significantly wrong.
I worked at a company where we reported a $2.4 million annual run rate based on a single strong month. Two months later, we had to explain to the board why we were tracking at $1.1 million instead. The run rate hadn't been wrong at the time it was calculated. Our interpretation of it was. That distinction matters more than the formula itself.
When Run Rates Actually Work
Run rates are most reliable in businesses with stable recurring revenue. Subscription models, particularly B2B SaaS with annual contracts, are the ideal use case. If your monthly recurring revenue (MRR) has held within 5% for the last six months, a run rate projection will likely land within 10% of actual results. That's useful. That's actionable. They also work for early-stage companies that need a quick reference point. When you're raising a seed round and someone asks what your annualized revenue looks like, you can't always wait for a full fiscal year. The run rate gives investors a ballpark figure fast. But it should always come with a qualifier. Always say what period you're annualizing from and note any known variables that could shift the number. For project-based revenue or one-time sales, run rates are meaningless. If your company closed a single $200,000 deal last month, multiplying by twelve to claim a $2.4 million run rate is misleading at best. Revenue concentration skews the projection instantly. In those cases, use a trailing twelve-month figure instead, or break down your pipeline into stages with probability weighting.
Get the Full Details
The Calculation Methods
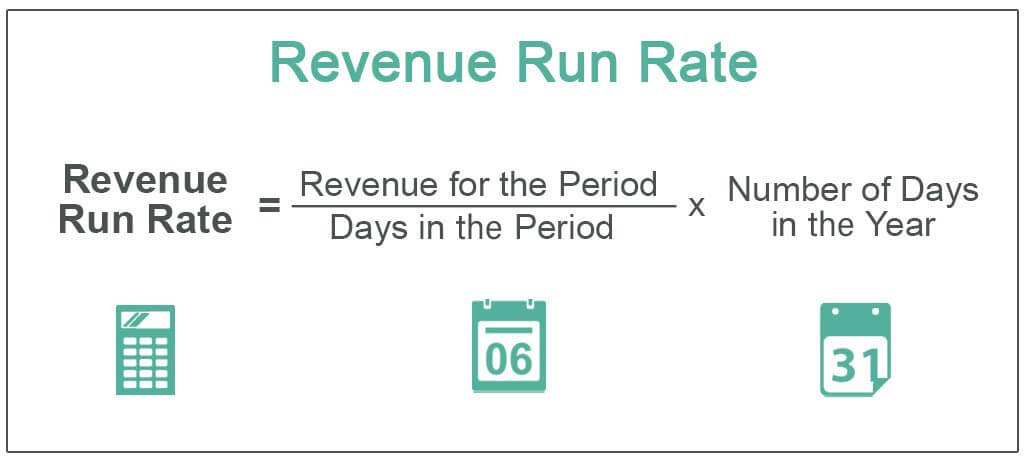
There are three standard approaches. Pick one and stick with it. Switching methods mid-quarter makes comparison impossible. The simple monthly run rate is what I just described. Current month revenue times twelve. Fastest to calculate. Least accurate if your revenue fluctuates. The trailing run rate uses the last four weeks of revenue, annualized. This smooths out month-end timing issues and gives a more current snapshot. If your billing cycles don't align with calendar months, this is the method to use. I prefer this approach for monthly tracking because it reflects actual collected revenue rather than invoiced amounts.
The annualized run rate takes your full year-to-date revenue, divides by the number of months elapsed, and multiplies by twelve. This is the most stable method for established businesses but the slowest to reflect change. If you lost your biggest client last month, your year-to-date figure won't show it until the next reporting cycle. Here's a practical example. Company X brings in $80,000 MRR with consistent month-over-month growth of about 3%. A simple monthly run rate gives $960,000 annualized. The trailing four-week figure comes to $82,000, annualized at $984,000. The year-to-date approach, with eight months at an average of $76,500, produces $1,147,500. All three numbers are defensible. Only one will be close to actual year-end results, and it depends entirely on whether the growth trend continues, stalls, or reverses.
Pitfalls That Kill Projections
Seasonality is the biggest silent killer of run rate accuracy. Holiday revenue spikes, summer slowdowns, end-of-quarter pushes—these all distort single-month figures. I learned this the hard way when we were acquired. The buyer's model assumed our Q4 run rate would repeat quarterly. It didn't. Q1 and Q2 averaged half of Q4 revenue. The adjustment to our projection cost us a valuation discrepancy that took six months to resolve. Another pitfall is using gross revenue instead of net revenue. Refunds, chargebacks, and discounting can erode your actual run rate significantly. A company reporting $100,000 in gross monthly revenue might actually retain $85,000 after deductions. Use net revenue for your run rate calculation if refunds or chargebacks are a material portion of your business. Contract timing distorts run rates too. If a large annual contract gets signed mid-month, prorating the revenue affects your monthly figure. Some companies recognize the full amount in the signing month. Others spread it. Whichever method you use, be consistent and disclose it. Mixing recognition methods between reporting periods invalidates the comparison.
Advanced Usage: Combined Run Rate
Investors and analysts often ask for the combined run rate, which adds new recurring revenue from the current period to your existing run rate. It shows the direction your business is moving, not just where it sits today. If your trailing run rate is $984,000 and you added $40,000 in new MRR this month, your combined run rate is $1,032,000. That's a more useful number for showing momentum. The downside is that combined run rate can overstate sustainability. New revenue includes customers who may churn next month. Factoring churn into your projection makes the number more honest but also more complex. A simple formula for a churn-adjusted run rate would be: (Monthly Recurring Revenue minus Monthly Churn) multiplied by twelve. This gives you a floor, not a ceiling.
When to Drop the Run Rate Entirely
Some situations demand a different approach. If your revenue is lumpy—large irregular deals, project-based work, or heavy reliance on a few enterprise contracts—run rates add false precision. They create an illusion of predictability that doesn't exist. In those cases, use a weighted pipeline model instead. Assign probability percentages to each deal in your funnel and sum the expected values. It takes more time but produces a more realistic projection. Pre-revenue companies shouldn't use run rates at all. There's nothing to annualize. Use burn rate and runway metrics instead. If you're burning $50,000 per month with $600,000 in the bank, you have twelve months of runway. That's a clearer picture of your financial position than any revenue projection.
A Note on Interpretation
The run rate is a snapshot, not a forecast. It tells you what your revenue would be if today's conditions held for a full year. It does not predict what will happen. The difference between those two statements is where most financial mistakes originate. Use run rates as a baseline for comparison, not as a ground truth. Track the variance between your run rate and actual results over time. When that variance exceeds 15%, your underlying assumptions need review. I stopped reporting a single run rate to my board after my second acquisition. Now I report three numbers: the simple run rate, the trailing run rate, and the churn-adjusted run rate. The spread between them communicates more than any single figure ever could. A narrow spread means stability. A wide spread means volatility that needs attention. Both are useful. Neither is a crystal ball.