Understanding Recourse in Legal and Financial Contexts
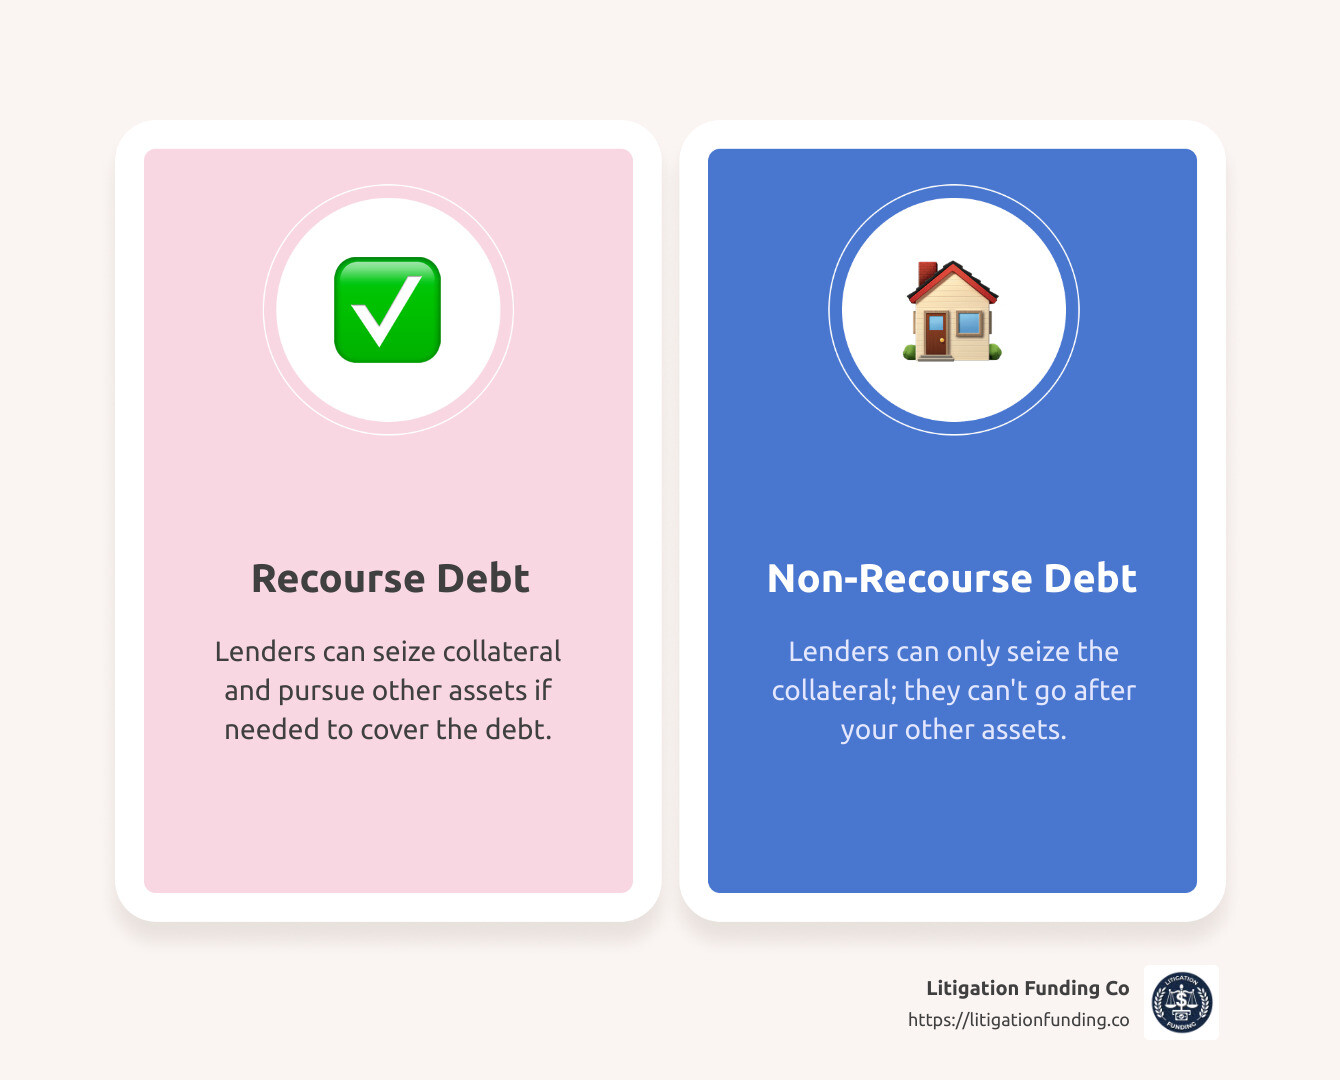
Recourse is a term that comes up constantly when dealing with loans, contracts, and debt obligations. Most people encounter it when taking out a mortgage or business loan, but it applies to far more than just borrowing money. The concept is straightforward on paper and significantly messier in practice. At its core, recourse refers to the legal right of a lender or creditor to pursue repayment from a borrower beyond just the collateral securing the debt. If you take out a recourse loan and default, the lender can go after your other assets, your wages, or other property. A non-recourse loan limits the lender to seizing only the collateral. That distinction matters enormously, especially in commercial real estate and business lending. I dealt with a client back in 2019 who had signed a commercial mortgage that turned out to be full recourse, not non-recourse as he was told by the broker. The property defaulted during the pandemic. The lender pursued a deficiency judgment against his personal assets because the loan documents were unambiguous about the recourse clause. It cost him roughly eighteen months of litigation and a significant portion of his savings. The broker had said the wrong thing, and my client had not read the actual contract carefully enough to catch the discrepancy.
How Recourse Works in Practice
When a borrower defaults on a recourse obligation, the creditor has several paths available. First, they seize and sell the collateral. If the sale proceeds do not cover the full outstanding balance, they can pursue a deficiency judgment. This is where recourse differs from non-recourse arrangements. In a non-recourse structure, the lender absorbs the loss once the collateral is gone. With recourse, the borrower remains personally liable for the remaining amount. The process usually goes like this. The creditor files a lawsuit for the deficiency amount after collateral liquidation fails to satisfy the debt. The court then determines whether the sale was conducted in a commercially reasonable manner. If the creditor sold the collateral too quickly or at an unreasonably low price, the borrower may have a defense that reduces the deficiency. I have seen courts cut deficiency judgments by thirty to fifty percent in cases where the collateral liquidation process was clearly rushed or poorly executed. After obtaining a judgment, the creditor can garnish wages, place liens on other property, or freeze bank accounts. State law governs exactly what they can and cannot touch. Some states offer strong homestead exemptions that protect primary residences from deficiency judgments. Others provide minimal protection. This is why jurisdiction matters so much in any recourse dispute.
Common Types of Recourse Obligations
Recourse appears in several different areas of law and finance. Mortgage lending is the most common. Purchase-money mortgages in some states are non-recourse by statute, but refinances typically convert the debt to full recourse. I remember working through a case where a homeowner refinanced their primary residence and inadvertently lost their non-recourse protection. The lender then came after their second property and retirement accounts after the market dropped. Business loans are another major category. Small business administration loans, for example, almost always require personal guarantees that make them recourse obligations. Commercial equipment leases frequently contain recourse clauses. Even vendor agreements sometimes include cross-default provisions that create recourse exposure if the borrower falls behind elsewhere. Guarantor liability is perhaps the most misunderstood aspect of recourse. When someone cosigns or guarantees a loan, they become directly liable for the full amount. This is recourse in its purest form. I have seen individuals sign as guarantors for their children's business loans without understanding that the lender could come after their home, their car, and their bank accounts. The credit card industry uses recourse provisions in merchant agreements all the time, requiring business owners to cover chargebacks and losses from their personal funds.
Get the Full Details
Limitations and Drawbacks You Should Know About
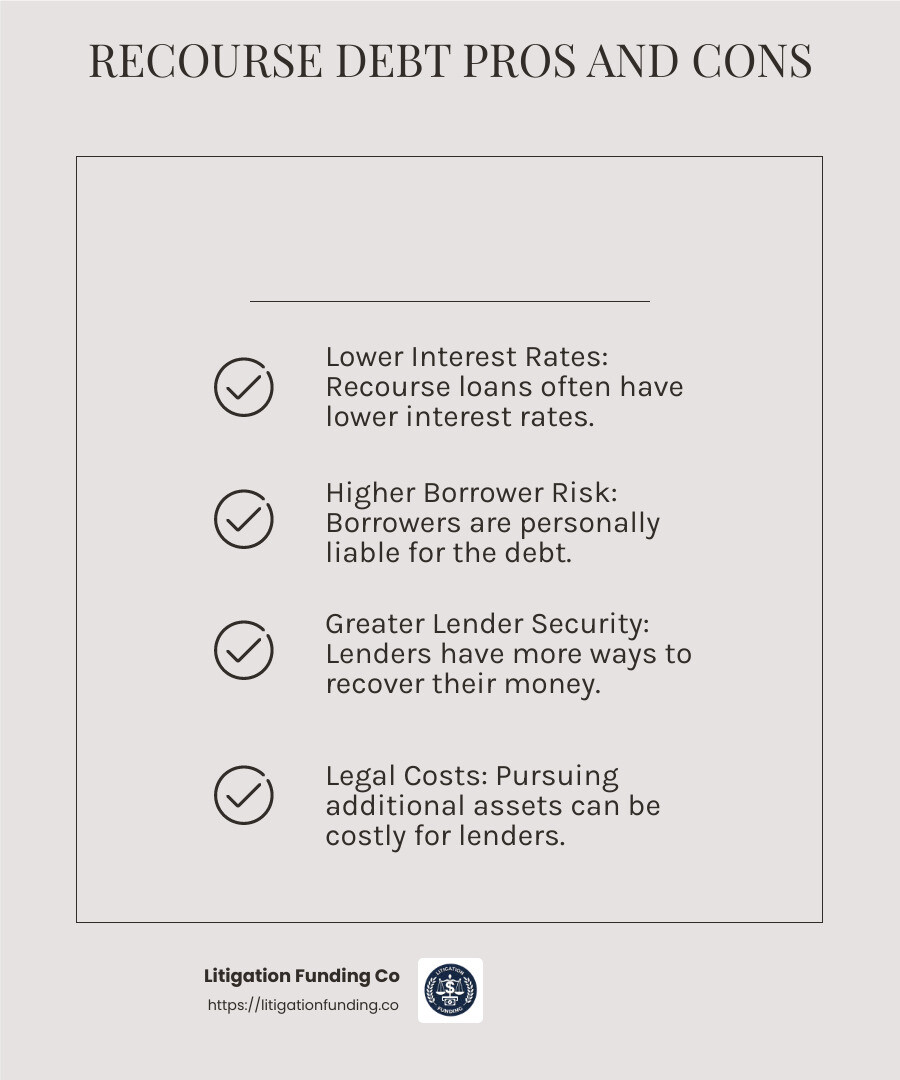
Recourse is not a blanket solution for creditors, and it does not guarantee recovery. Even with full recourse, a borrower who has no attachable assets is effectively judgment-proof. The legal process to pursue recourse costs money, takes time, and produces uncertain results. Filing a lawsuit, going through discovery, obtaining a judgment, and then actually collecting can take two to four years in many jurisdictions. During that time, the borrower may declare bankruptcy, which discharges the deficiency entirely in a Chapter 7 filing. The biggest practical limitation is the cost-benefit analysis. A lender pursuing a deficiency judgment on a hundred thousand dollar loan might spend twenty thousand dollars in legal fees over three years and recover nothing if the borrower has already hidden or spent their remaining assets. Many creditors write off small deficiencies rather than chase them. They have internal policies about minimum collection thresholds. For borrowers, recourse creates enormous pressure that can lead to poor financial decisions. I worked with a small business owner who, facing a recourse claim, took out high-interest payday loans to make partial payments, digging himself deeper into debt rather than negotiating a settlement. The right move in that situation would have been to approach the lender before default and propose a structured payoff or deed in lieu of foreclosure. Lenders often prefer that outcome because it avoids legal fees and extends the collection timeline by months instead of years.
What You Can Do If Facing a Recourse Claim
If you are dealing with a potential recourse obligation, the first step is always to review the actual contract language. The written terms control, not what anyone told you verbally. Look for the recourse clause, the guarantee provision, and any limitations on liability. Check whether your state has statutes that modify or restrict recourse for certain types of debts. Some states cap deficiency judgments or require the creditor to offer mediation before filing suit. Negotiation should come before litigation whenever possible. A lender that wants cash is often willing to accept a lump-sum settlement for sixty to seventy percent of the deficiency. This saves both sides legal costs and gives the borrower a clean exit. I structured several of these settlements where the borrower borrowed from family or sold a vehicle to pay a reduced amount, and the lender agreed to release all further recourse claims in writing. If negotiation fails, you may need to consider bankruptcy as an option. Chapter 7 discharge eliminates most recourse obligations, though secured creditors retain their lien rights. Chapter 13 allows you to repay a portion of the debt through a court-supervised plan while keeping your assets. The choice between chapters depends on your income level, the amount of secured debt, and whether you own exempt property.
Documentation is critical throughout the entire process. Keep records of every communication with the creditor, including dates, names, and the substance of what was discussed. If the creditor violated state collection laws or attempted to enforce recourse beyond what the contract allows, those violations can provide leverage or even create a counterclaim. I once had a case where the lender threatened to garnish wages before even filing a lawsuit, which was a clear violation of state law. That procedural error became our primary negotiating chip, and we settled for a fraction of what they initially demanded.
When Recourse Does and Does Not Apply
Not every debt carries recourse. Consumer credit cards generally do, but the terms vary by issuer and jurisdiction. Credit union loans sometimes include waiver provisions that limit recourse to specific collateral. Auto loans are frequently recourse, though some states restrict deficiency judgments on vehicle sales below a certain amount. Student loans present a special category, with federal loans offering income-driven repayment options that function differently than standard recourse collection. The key insight that most people miss is that recourse is not binary. It exists on a spectrum. A loan might be partially recourse, with the borrower liable for only a portion of any deficiency. It might be recourse only after certain conditions are met, such as the lender failing to sell the collateral within a specified timeframe. Some contracts include recourse carve-outs for bad faith actions by the lender, where the borrower can offset the deficiency by proving the lender acted improperly during the collection process. Reading the fine print matters more than understanding the general concept. The specific language in your contract will determine exactly what recourse means for your situation. If you are unsure about a clause, have it reviewed by a qualified attorney before signing anything. The cost of a document review is trivial compared to the cost of discovering too late that you signed away your protections.