The Word Keeps Changing Depending On Who Is Saying It
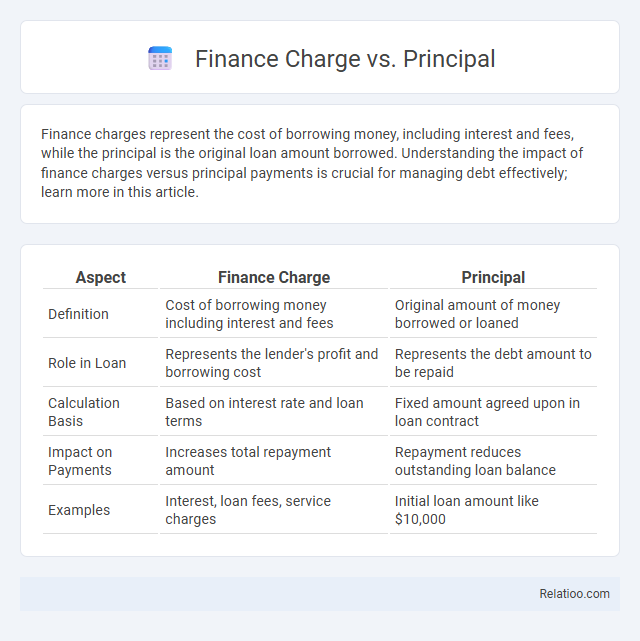
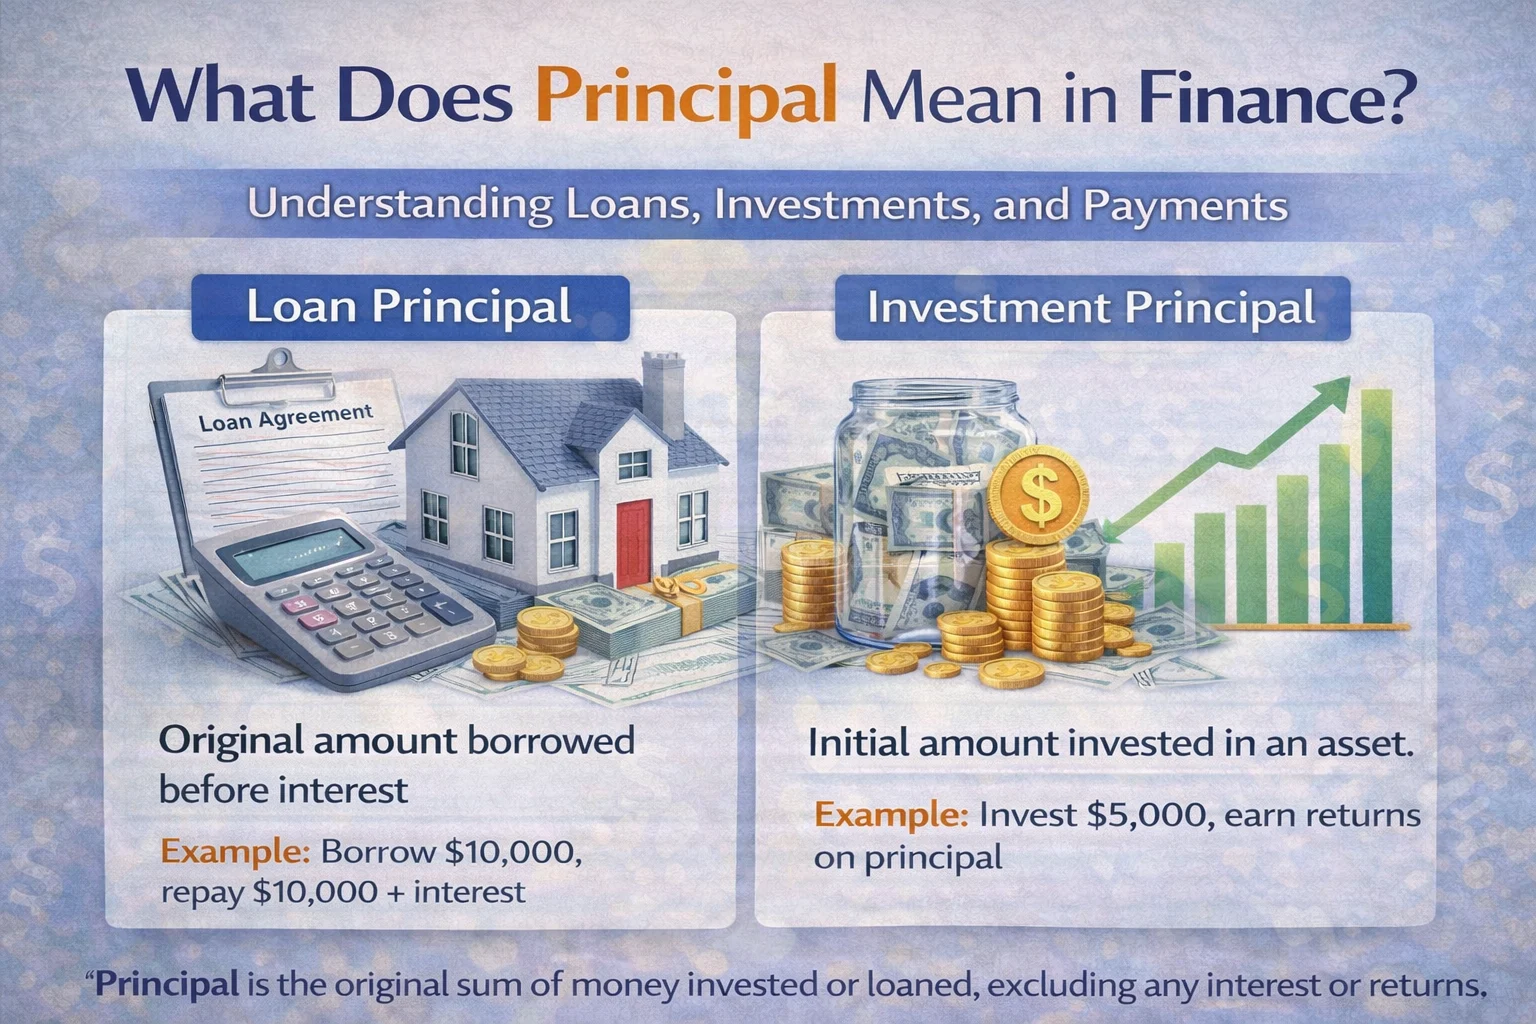
Principal is one of those terms that seems simple until you open a mortgage document or sit through a corporate finance meeting. The definition shifts by a half-step depending on context, and that half-step is where people lose money. I have seen juniors treat every instance of the word the same way and then wonder why their modeling was off by six figures. At its most basic, principal is the original sum of money before any interest accrues. That is the textbook definition and it is correct. The problem is that in practice, the word does not stay anchored there. In lending, principal refers to the outstanding balance remaining after payments. In corporate governance, a principal is a person—usually a shareholder or senior decision-maker who delegates work to an agent. In investment banking, principal often means equity capital contributed by the firm itself rather than borrowed money. Same word, three completely different mechanics. I learned this the hard way on a mid-market leveraged buyout around 2019. The term sheet used "principal" when referring to the equity contribution required from the sponsor, but the credit agreement used "principal" to mean the drawn balance on the senior debt facility. My team spent two days reconciling because we assumed both meant the same thing. We were wrong. The workaround was straightforward once we caught it: I built a term map in Excel listing every occurrence of the word across all deal documents and color-coded them by definition. Lending-related entries in blue, equity-related entries in green, governance entries in yellow. It cut the reconciliation time from days to about three hours and made the confusion visible to everyone in the room.
Here is what most guides do not tell you about principal in lending. The outstanding principal balance is not a linear decline. In a standard amortizing loan, the first payment might include $3,000 in interest and only $500 in principal reduction. By payment forty-eight, it could be reversed. People who skip ahead to look at the principal balance without checking the amortization schedule will misjudge cash flow timing. This is especially relevant when refinancing or prepaying. Prepaying $100,000 on a loan in year two saves significantly more in total interest than prepaying the same amount in year eight, because the principal base is still larger earlier on. Not obvious to someone who has only ever dealt with simple interest accounts. In corporate finance and accounting, principal also appears in debt issuance. When a company issues bonds at a discount or premium, the principal stated on the bond certificate is the face value, but the carrying value on the balance sheet is different. The difference gets amortized over the life of the bond using the effective interest method. Beginners often miss this entirely. They record the bond at face value and move on. The carrying value drifts from face value over time, and if you are modeling debt covenants or net leverage ratios, using face value instead of carrying value will throw off your numbers. A twelve percent coupon bond issued at ninety-five cents on the dollar does not have a principal liability of one hundred cents. It has a carrying value that starts at ninety-five and steps up to one hundred over the bond's life. The principal you are actually responsible for repaying is still one hundred at maturity, but the accounting and economic picture is not that simple. There is also the principal-agent problem in corporate governance, which is where the word leaves finance altogether and enters organizational theory. Shareholders are principals. Management is the agent. The agent may act in their own interest rather than the principal's. This is not a calculation issue. It is a structural one. Equity compensation, board oversight, vesting schedules, and performance metrics exist precisely because the principal-agent gap creates real cost. The cost of that gap is called agency cost, and it can easily run into the low single digits of enterprise value for under-governed companies.
When you move into private equity and venture capital, principal takes on yet another meaning. A general partner committing "principal" to a fund means they are putting up their own capital alongside limited partners. This is different from management fees or carried interest. The principal commitment is the actual equity the GP risks. It signals skin in the game. Limited partners pay close attention to how much principal the GP commits relative to the total fund size. A typical target is one to three percent of total fund commitments coming from the GP as principal. Below that and LPs get nervous. Above that and the GP may be overexposed relative to their ability to diversify personally. One edge case that catches people off guard involves cross-collateralization. In a syndicated loan structure, multiple facilities can share the same collateral pool. If you pay down principal on Facility A, the released collateral may immediately support borrowing on Facility B. The principal balance drops, but your available capacity does not improve as much as it appears. I worked on a situation where a client thought they had freed up $40 million in capacity by paying down $40 million in senior debt. They had not. The cross-collateral clause tied the two facilities together, and the model showed the net available capacity barely moved. Without modeling the cross-collateral mechanics explicitly, you would have recommended a draw that never cleared. Another thing worth understanding is how principal interacts with tax. Interest payments on debt are generally tax-deductible, which creates a tax shield based on the principal amount outstanding and the interest rate. Debt tax shields are a standard part of valuation in DCF models. But the shield depends on the company actually generating enough taxable income to use the deduction. A profitable subsidiary in a high-tax jurisdiction gets full benefit. A company in a loss position gets nothing until it turns profitable again. Principal that sits on the books during a multi-year loss period produces zero tax benefit. The theoretical value of the shield is not the same as the realized value.
Get the Full Details
There is also a practical limitation to how principal is treated in distressed situations. When a company restructures, lenders often agree to principal haircuts. A creditor might accept sixty cents on the dollar to avoid a longer bankruptcy process. The principal balance on the books drops, but the legal obligation that was originally stated is now modified. Reconciliation between the old principal amount and the new one requires careful documentation. If you are modeling recoveries for a credit fund, using the original principal face value instead of the restructured principal will overstate expected cash flows. I once saw a fund underwrite a recovery position assuming full principal repayment because they had not accounted for a restructuring that had already been announced but not yet closed. The trade went poorly when the haircut was confirmed at sixty-five cents on the dollar. In foreign currency debt, principal adds another layer. A U.S. investor holding Japanese yen-denominated bonds faces principal risk in two directions. The coupon payments are in yen. The principal repayment at maturity is also in yen. If the yen weakens against the dollar, the dollar-value of both the coupons and the principal decline. Currency-hedged funds attempt to isolate this, but the hedge itself has a cost that reduces the effective yield. Unhedged, the principal is exposed to translation risk every day until maturity. This is not theoretical. During the yen's depreciation cycle from 2022 through 2024, unhedged Japanese bond positions lost roughly fifteen to twenty percent in dollar terms from currency movement alone, on top of the modest coupon income. For individuals thinking about their own finances, the practical takeaway is that principal is never just a number. It is a moving target that changes based on amortization, prepayment, refinancing, restructuring, currency fluctuation, and accounting treatment. When you see the word in a document, the first question to ask is which version of principal they are talking about. The original face amount, the current outstanding balance, the equity contribution, or the governance role. Misidentifying any of those leads to downstream errors. The reconciliation step I mentioned earlier—the term map—is the single most useful tool I have found for catching these mismatches before they become problems.
One final detail that rarely gets discussed is how principal behaves in revenue-based financing. Unlike traditional loans where principal declines on a fixed schedule, revenue-based financing ties principal repayment to a percentage of monthly revenue. In good months, principal drops fast. In bad months, it barely moves. The total principal to be repaid may include a cap on total repayment amount, which means the effective principal cost can vary widely depending on revenue performance. This structure is common in startup lending and ecommerce financing. The principal is technically the amount advanced, but the actual economic cost depends entirely on how revenue plays out over the life of the note.