What Does Ltd Mean Unlock The Secrets Of Limited Liability Companies
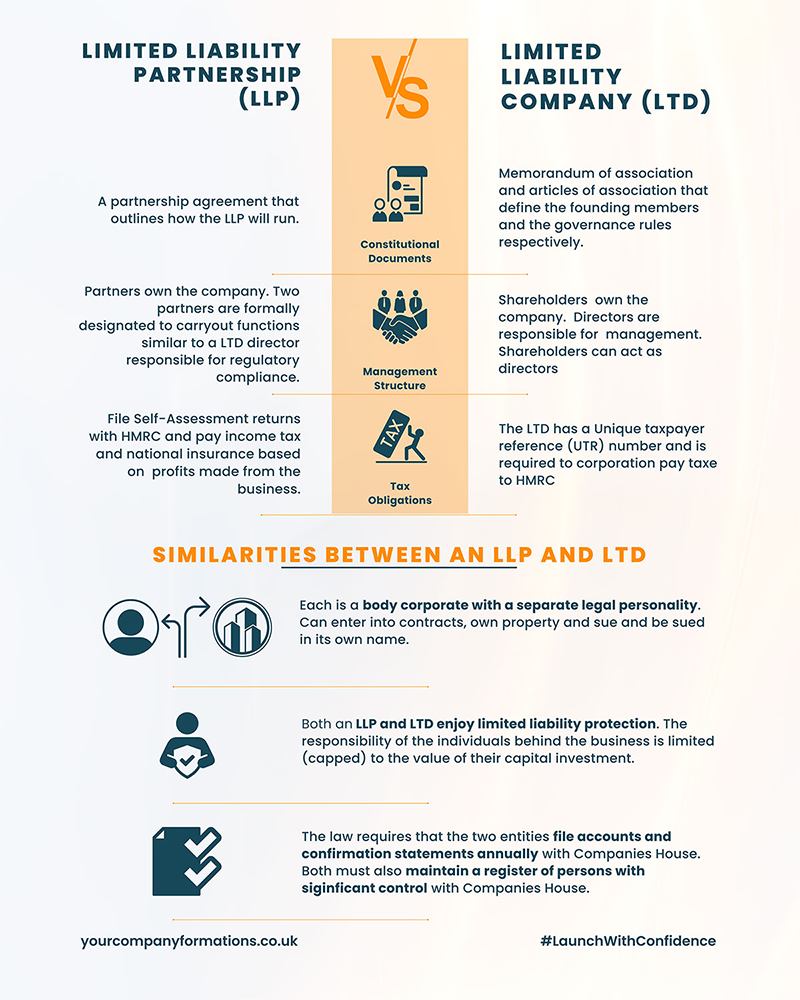
Ltd is just a legal suffix that tells you the company has a particular type of corporate structure. It stands for Limited, meaning the owners' financial risk is capped at whatever they invested. That's it on the surface. But the details matter, and most people gloss over them because the basic explanation sounds simple enough. When you register a Ltd company, you are creating a separate legal entity from the people who own it. The business can hold assets, incur debt, and be sued in its own name. The shareholders are not personally liable for the company's debts beyond the amount unpaid on their shares. This is the core mechanism, and it has real practical implications that go beyond what the acronym suggests.
What Does Ltd Mean Unlock The Secrets Of Limited Liability Companies
Here is where things get less straightforward. The liability protection is not absolute. I spent three years working with small business owners in the UK, and I watched two situations where the corporate veil was pierced through negligence rather than any legal technicality. In one case, a sole director treated the company bank account as his personal wallet, transferring funds without any documentation. When the business failed with outstanding tax liabilities, HMRC went after him personally because the separation between him and the company had been effectively erased by his actions. The other case involved a Ltd company with multiple directors who never held proper board meetings or kept minutes. A creditor sued and argued that the company was operating as a sham. The court agreed because there was no evidence of independent decision-making or governance. The directors became personally liable. These are edge cases, but they happen far more often than people expect. Forming a Ltd company is quick. In the UK, you can register through Companies House for £12 and have it confirmed within 24 hours. In the US, LLC registration varies by state and can take anywhere from a day to several weeks depending on processing times. The speed of formation creates a false sense of security. People think the protection comes automatically with the paperwork. It does not.
Practical Mechanics and Common Pitfalls
You need to maintain proper records. File accounts on time. Keep company finances separate from personal finances. Hold directors' meetings when required. These are not bureaucratic checkboxes. They are the actual safeguards that keep the liability protection intact. I have seen more business owners lose their personal assets to avoidable paperwork failures than to any legitimate legal challenge against the corporate structure. Another thing people misunderstand is the difference between a Ltd and an LLC. They sound similar but operate differently depending on jurisdiction. A UK Ltd is governed by company law with strict filing requirements including annual confirmation statements and accounts. A US LLC is governed by state law with more flexible operating agreements. The liability protection functions similarly in both, but the compliance burden is quite different. Tax treatment adds another layer of complexity. In the UK, Ltd companies pay Corporation Tax on profits. Shareholders then pay personal tax on dividends. This creates a double taxation scenario that many new business owners find surprising. In the US, LLCs can elect to be taxed as pass-through entities, meaning profits flow directly to owners' personal tax returns. The tax implications alone can determine which structure makes sense for your situation.
Get the Full Details

When Ltd Structure Fails You
There are scenarios where the limited liability protection simply does not work. If you provide professional services and the company makes a mistake, clients may pursue you personally regardless of the corporate structure. Professional indemnity insurance exists for this reason. If you personally guarantee a business loan or lease, the guarantee overrides the liability protection. Banks and landlords routinely require personal guarantees from Ltd company directors, especially for new businesses without established credit history. I encountered a contractor who set up a Ltd company to protect his home. He signed a personal guarantee for a £50,000 equipment lease. The business failed within eight months. He lost the equipment and had to sell part of his property to cover the guarantee. The Ltd structure provided zero protection because he signed away the protection before the company even started trading. This is not a rare occurrence. Another limitation is credibility. Some larger clients and government contracts require suppliers to have a certain financial history or trading track record. A brand new Ltd company with thin financials may be passed over in favor of an established business, regardless of the liability advantages. The structure helps with risk management but does not substitute for a solid business reputation.
What Actually Matters in Practice
The real question is whether forming a Ltd company makes sense for your situation. If you are running a low-risk service business with minimal debt and no professional liabilities, the costs and compliance burden may outweigh the benefits. A sole trader structure might be simpler and cheaper. If you are taking on significant financial obligations, hiring employees, or operating in a higher-risk industry, the Ltd structure provides genuine protection worth the administrative overhead. The protection is real but conditional. It requires active maintenance of the corporate separation. It does not cover personal guarantees. It does not protect against professional negligence claims in the way that insurance does. And it does not eliminate tax obligations. Understanding these boundaries before you register is more valuable than understanding the acronym itself.