What Financed Actually Means When You See It on a Receipt or Contract
Most people encounter the word financed without really knowing what it entails until they're staring at monthly payments they didn't expect to have. The basic idea is straightforward enough—someone else paid upfront and you're repaying them over time—but the details matter more than the definition. When a purchase is financed, you're not buying outright. A lender covered the cost, and now you owe them principal plus whatever interest they charged. That's it. Simple. But then you open the fine print and realize there's more to unpack than just the monthly amount.
What Does Financed Mean A Simple Explanation You Need To Know
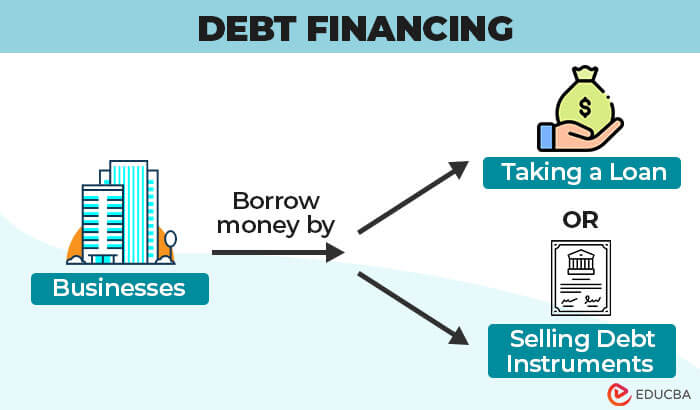
Financed means money was borrowed to cover a purchase, and repayment happens across multiple periods instead of all at once. The lender owns the asset until you complete those payments. If you skip a payment, they can typically repossess the item or report you to credit bureaus. I worked in auto lending for eight years before moving to real estate. One thing I noticed repeatedly is that people focus entirely on the monthly payment and completely ignore the total cost over the loan's life. You'll see ads promising forty-nine dollars a month on a twenty-thousand dollar car, but when you run the numbers, that payment stretches over seventy-two months with eight percent interest. You end up paying thirty-two thousand total. The financed amount itself is called the principal. Interest gets layered on top based on your credit profile, the lender's risk assessment, and current market rates. Two people buying the same item can finish with wildly different total costs purely because one had a seven-hundred-and-fifty credit score and the other sat at six-hundred-and-twenty.
Here's a scenario most people never consider: some financing deals come with deferred interest clauses. You make all your payments on time, look like a responsible borrower, and then get hit with every cent of accumulated interest from day one. I watched a customer nearly lose his truck because he financed through a dealership promotion that sounded too good to be true. It was. The good news is that you can often pay off financed purchases early without penalties. Some lenders charge prepayment fees to protect their expected interest income, but federal regulations limit those on certain loan types. Always read the prepayment clause before signing anything. Credit cards count as a form of financing when you don't pay the full balance each month. That's consumer revolving credit with annual percentage rates that routinely exceed eighteen percent. It's convenient, but expensive if you carry balances past the grace period.
Get the Full Details
When you're deciding whether to finance something, compare the cash price against the financed total. Subtract one from the other to see exactly how much borrowing costs you. If the difference exceeds what the item is worth to you in convenience, reconsider your options or look for a lower-rate alternative.