How Brazil's Resource Base Actually Works
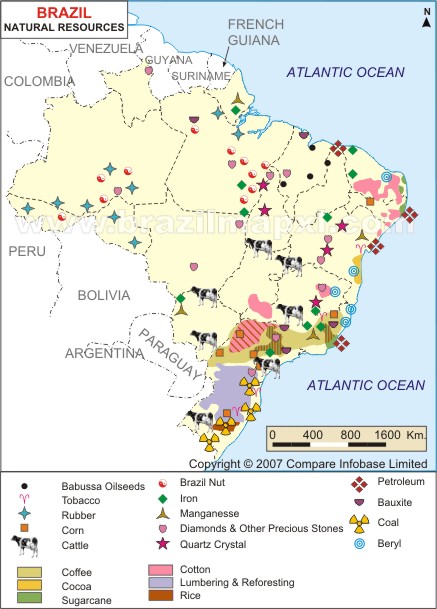
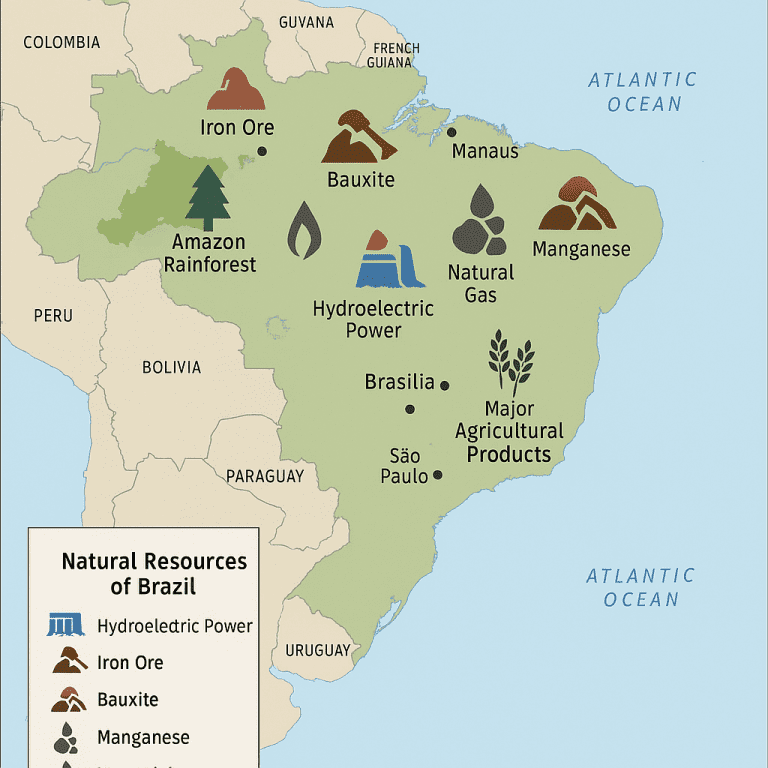
Brazil sits on one of the most concentrated resource endowments on the planet. I spent about four years auditing commodity supply chains across South America, and the thing that always caught people off guard was how deeply intertwined the economic and ecological systems are here. They're not separate tracks. You pull iron ore from Minas Gerais and the water tables shift. You clear land for soy in Mato Grosso and the rainfall patterns in the Pantanal change within two seasons. Most outsiders treat these as parallel stories. In practice they collide constantly. The core list is straightforward if you look past the textbook summaries. Iron ore is the anchor, with Vale operating the giant Carajás mine in the state of Pará. That single operation produces roughly 850 million metric tons annually, which is about a fifth of global seaborne iron ore supply. The ore grades run 65 percent Fe on average, which is notably higher than Australian or Canadian counterparts. This means lower processing costs per ton of steel produced, but it also means the waste rock volumes are massive and the tailings management problem is existential. The Brumadinho collapse in 2019 wasn't a rare accident. It was the logical endpoint of decades of relaxed oversight on tailings dam design. Bauxite follows. Pará hosts some of the world's largest bauxite reserves, feeding aluminum smelters that draw heavily from hydroelectric generation. The ratio here is brutal. Producing one ton of aluminum requires roughly four tons of bauxite and about 13 megawatt-hours of electricity. Brazil's hydro backbone makes the energy cost competitive, but the environmental tradeoff is enormous reservoir flooding and methane emissions from decomposing organic matter underwater. I worked a project near Tucuruí where the local fishing economies collapsed within three years of reservoir filling. The government compensation programs existed on paper. In practice they paid out at half the assessed value and took eighteen months to disburse.
Oil and natural gas make up the third pillar. The pre-salt layer beneath the Santos and Campos basins holds an estimated 50 to 80 billion barrels of recoverable reserves. Petrobras dominates extraction through deepwater drilling platforms that operate at depths exceeding 2,000 meters. The technical barrier to entry here is extreme. A single FPSO unit costs between 500 million and 1.5 billion dollars depending on capacity. That concentration of capital means the sector generates huge export revenues but employs relatively few people compared to mining or agriculture. The fiscal regime changed significantly under the 2010s production-sharing model, which shifted risk away from the state operator but introduced complexity that still slows new field development. Agricultural resources deserve their own category because they're not naturally occurring in the same way. The Cerrado biome was transformed from savanna into what is now the world's largest soybean exporting region. Brazil produces over 150 million metric tons of soy annually, with Mato Grosso state alone accounting for roughly 40 percent. The soil is naturally acidic and low in phosphorus. The workaround, which was adopted aggressively from the 1970s onward, involved massive lime application and bacterial inoculation for nitrogen fixation. This agricultural intensification came at the cost of roughly 400,000 square kilometers of Cerrado conversion since 1985. The Atlantic Forest fared even worse, with an estimated 90 percent original coverage removed. Copper, nickel, tin, and other metals round out the mineral portfolio. Trombetas operates one of the world's largest nickel refineries. The Maues tin deposits in Amazonas remain underdeveloped largely due to indigenous land conflicts and logistical constraints. Gold mining in the Amazon basin, particularly around Santarém and the Tapajós river system, has exploded in informal and illegal operations. IBAMA estimates that illegal gold mining generated over 60 tons of mercury contamination in the Amazon basin between 2017 and 2022. Mercury bioaccumulates in fish, which is the primary protein source for riverside communities. This isn't a future risk. It's a current public health crisis with elevated blood mercury levels in 60 to 80 percent of patients at clinics in affected municipalities.
The freshwater resources are themselves a commodity. The Amazon basin contains approximately 20 percent of the world's fresh surface water. São Francisco River, often called the "River of National Integration," supplies water to over 12 million people in the semi-arid Northeast. The proposed transposition project has been debated since the 1990s and remains partially incomplete. The ecological cost involves altering downstream flow regimes that coastal mangroves and estuarine fisheries depend on. I visited the lower São Francisco in 2018 during a drought year. The river was running at 30 percent of normal discharge. The desalination plants in Jaguaribe, Rio Grande do Norte, were operating at full capacity and still couldn't meet demand for the sugarcane irrigation zones that dominate that corridor. Wind and solar potential represent an underutilized resource layer. The northeastern coast, particularly Ceará and Rio Grande do Norte, has capacity factors for wind generation exceeding 45 percent, which rivals the best sites in Denmark. Solar irradiance averages 5.5 kilowatt-hours per square meter per day across much of the interior. The bottleneck isn't the resource quality. It's transmission. The grid infrastructure simply wasn't built to move power from the generation zones to the consumption centers in São Paulo and Rio de Janeiro. Projects stall at ANEEL licensing for 18 to 24 months on interconnection studies alone. I tracked one 300-megawatt wind farm in Piauí that sat permitted and unbuilt for three years because the substation upgrade required from the grid operator was delayed by environmental licensing disputes over bird migration corridors. Biodiversity itself functions as a resource, though the valuation mechanisms are incomplete. The pharmaceutical industry sources roughly 25 percent of modern drugs from rainforest compounds. Brazil's flora includes an estimated 55,000 plant species, of which only about 4,000 have been pharmacologically screened. The benefit-sharing framework established under the 2001 Biodiversity Law requires genetic heritage access authorization and fair profit sharing. In practice the system is bottlenecked. CPAP, the former access registry body, processed fewer than 200 applications annually between 2015 and 2020 despite hundreds of pending submissions. Research institutions and biotech companies navigate this by structuring collaborations through universities that already hold blanket authorization, which concentrates benefit among well-connected institutions and excludes smaller operators and traditional communities who hold the actual knowledge.
Get the Full Details
Practical Implications For Analysis And Investment
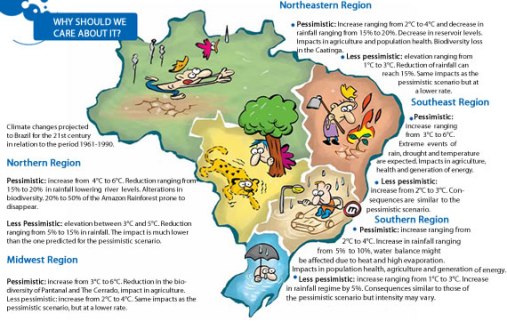
When you're evaluating Brazil's resource sector, the standard commodity price models miss the regulatory and infrastructural friction that actually determines realized returns. Iron ore prices matter less than tailings dam compliance costs, which have increased capital expenditure by 15 to 20 percent per project since Brumadinho. Bauxite spreads are secondary to hydroelectric availability, which varies year to year with rainfall patterns that are intensifying under climate change. The Tucuruí reservoir dropped to 28 percent capacity in 2024, forcing aluminum smelters to curtail production by up to 40 percent during dry seasons. Agricultural commodity analysis requires understanding the land use conversion pipeline. Soy expansion drives cattle ranchers inward, pushing them into forested frontier areas. The arc of deforestation in the Amazon follows a predictable pattern: roads open, land speculation begins, forest is cleared for pasture, cattle prices dictate further expansion. The carcass model that ties agricultural commodity prices directly to deforestation rates has a lag of approximately 18 months. If you're pricing soy futures without monitoring Brazilian cattle inventory data from IBGE, you're missing a leading indicator for forest conversion pressure. Forestry resources are another layer. Brazil's planted forest area covers roughly 9.5 million hectares, predominantly eucalyptus and pine. This supports a pulp and paper industry that generates over 20 billion dollars in annual exports. The growth cycle is six to seven years for pulp-grade eucalyptus. The industry is geographically concentrated in Bahia, Pará, and Rio Grande do Sul. Each state has different soil conditions and precipitation regimes that affect yield per hectare. Bahia's recôncavo region produces an average of 40 cubic meters per hectare annually. Northern Pará operations under improved genetics reach 55 to 60 cubic meters. The marginal cost difference between these regions determines which mills stay operational during pulp price downturns.
The lithium question deserves attention. Argentina and Chile dominate South American lithium, but Brazil's deposits in Minas Gerais and Goiás are significant. The Araxá deposit alone is estimated at 400,000 tons of lithium equivalent. Processing capability is the gap. Brazil currently lacks integrated lithium chemical production at scale. Companies are importing concentrate for domestic battery material production, which adds logistics cost and reduces margin. The national strategy targets 100,000 tons of lithium carbonate equivalent production by 2028, but securing processing technology partnerships has been slower than projected due to Chinese company dominance in lithium refining know-how. Timber extraction from the Amazon remains a contentious resource stream. Legal logging operations are governed by forest codes that require sustainable management plans and harvesting permits. Illegal logging accounts for an estimated 50 to 70 percent of total timber removal from the Amazon biome. The enforcement capacity of IBAMA and ICMBio is constrained. The agency's budget was cut by approximately 40 percent between 2019 and 2022, reducing inspection teams from over 1,200 to roughly 700. Satellite monitoring detected over 14,000 illegal logging incidents in 2021. Prosecution rates remained below 15 percent due to staffing shortages in environmental judiciary roles and evidentiary requirements that demand chain-of-custody documentation that rarely survives field seizures. Fisheries constitute an often-overlooked resource dimension. Brazil's coastline extends roughly 7,400 kilometers. The continental shelf fisheries support both industrial and artisanal sectors. The shrimp industry alone generates about 1.2 billion dollars in annual exports, with Paraná and Rio Grande do Norte as the primary states. Overfishing pressures are documented in southeastern coastal zones, where juvenile capture rates have declined by an estimated 30 percent since 2010. The aquaculture sector, particularly tilapia and shrimp farming, has grown to offset wild capture stagnation. Tilapia production reached 400,000 tons in 2023, making Brazil the third-largest global producer. The feed cost structure remains the binding constraint, with fishmeal and soybean meal comprising 60 to 70 percent of production costs.
The geothermal resource is negligible in Brazil due to tectonic position. The volcanic activity that makes geothermal viable in Iceland or Indonesia doesn't exist here. This limits diversification options for regions that might otherwise pursue mixed renewable portfolios. Hydro dominates because the geography demands it. The hydropower share of electricity generation is approximately 65 percent. This creates vulnerability that wind and solar can address, but only if transmission constraints are resolved. The government's grid expansion program, PAC Energia, allocates roughly 15 billion reais through 2026 for transmission line construction. Historical completion rates for these projects average 60 percent of planned capacity, delayed by land acquisition disputes and indigenous territory negotiations. Soil resources are being depleted faster than replacement rates justify. No-till farming has mitigated erosion on approximately 30 million hectares of cropland, but nutrient mining from continuous soy-corn rotations is a real phenomenon. Soil tests across Mato Grosso and Goiás show declining phosphorus availability in topsoil layers, requiring increasing fertilizer inputs per unit of output. Fertilizer import dependence is near 80 percent, exposing producers to price volatility and currency risk. The domestic production push through Odebrecht's phosphate operations in Minas Gerais and the alleged fraud scandal that followed has not materially changed import dependency. The diamond and gemstone sector operates in a gray zone between formal and informal extraction. Diamantina in Minas Gerais and the alluvial deposits in Rondônia and Amazonas produce significant rough stones. Artisanal miners, known as garimpeiros, operate in areas that overlap with indigenous territories and conservation units. The legal framework permits small-scale mining in designated areas, but enforcement is inconsistent. Gold prices above 1,800 dollars per ounce have made many marginal deposits economically viable, increasing pressure on regulated areas. The government's Operation Green Planet in 2023 removed over 200,000 illegal mining machines from the Tapajós region, but the operation displaced rather than eliminated the activity, with miners relocating to tributary streams and secondary river systems that are harder to monitor.

Cobalt and other battery metals remain largely unexplored. Brazil's geological survey, CPRM, has mapped cobalt occurrences in the Amazon craton region, but exploration activity is minimal compared to Africa or Canada. The regulatory uncertainty around indigenous land rights and environmental licensing discourages the capital expenditure required for discovery-stage exploration. Any assessment of Brazil's critical minerals profile should note that current reserve estimates cover maybe 10 to 15 percent of the prospective area. The resource potential is likely substantially higher, but the data gap is real and intentional, given the exploration disincentives. The carbon sequestration potential of standing forest represents an increasingly traded resource. Brazil's Amazon and Cerrado biomes store an estimated 120 to 150 billion tons of carbon in biomass and soil. The CAR, the rural environmental registry, covers approximately 75 percent of rural properties but contains significant data quality issues. Self-declared reserve areas frequently overlap or exceed legal boundaries. Verification requires ground-truthing that satellite imagery alone cannot provide. The carbon credit market structure depends on this verification. Project developers using remote sensing without ground validation have faced rejection from verra and gold standard auditors at rates exceeding 30 percent in the Brazilian context. The legitimate projects that pass validation command premium prices, but the pipeline of bankable credits is constrained by measurement uncertainty. Genetic resource data is another opaque category. Institutions like Fiocruz and the National Institute for Amazonian Research maintain bioprospecting collections, but the taxonomic backlog is enormous. An estimated 80 percent of Brazil's described species have not been bioactive-screened. The institutional capacity gap between description and screening means the resource is effectively unquantified. This isn't a data collection problem. It's a funding problem. The annual budget for taxonomic research across all Brazilian federal institutions is approximately 80 million reais, which supports fewer than 200 professional taxonomists nationwide. The resource exists. It's just not characterized.
When people ask about Brazil's natural resources, the answer depends entirely on whether they mean extracted commodities, ecosystem services, or unquantified biological potential. The economic data covers the first category reasonably well. The ecological consequences span all three and are poorly measured. The tension between them is the defining feature of Brazil's resource economy. Extraction generates export revenue and fiscal receipts. Ecosystem degradation imposes costs that rarely appear on corporate balance sheets or government budgets. The fiscal system treats resource rents as revenue without requiring corresponding investment in restoration or diversification. This accounting gap is where the real risk lives. It's not in commodity prices. It's in the unresolved liability.