What actually happens when you miss a Westlake payment
A late fee hits your account and your balance goes up. That is the basic version. The reality involves a few moving parts that are easy to overlook until they already hurt you. Westlake operates a lot of auto installment loans and some point-of-sale financing products. The fee structure differs between those two. An auto loan might carry a flat late fee while a retail loan uses a percentage of your missed payment. Both approaches cost you money. Both approach it differently. I spent several years working loan servicing operations before moving to the other side. One thing I learned the hard way is that people rarely lose sleep over the late fee itself. They lose sleep because they did not realize it had triggered additional downstream consequences. A single late payment can push your account into a higher risk bucket. That changes how future billing cycles look. It does not always show up on your statement immediately either. You might pay on time for three months after the late fee and still see the damage reflected elsewhere.
Westlake Financial Late Payment Fees Impact And How To Avoid Penalties
Here is the practical side of it. Westlake Financial charges late fees according to state law and your loan agreement terms. In most cases, if your payment is more than fifteen days past due, a late fee gets assessed. The exact amount depends on your contract. It is typically somewhere between a flat dollar amount and a small percentage of your scheduled payment. Some states cap it lower. Others allow the higher end. You can find your specific fee in the disclosure documents you received when you closed the loan. Look for the section labeled late payment charge or similar language. The impact goes beyond the fee itself. Once a payment is reported as late to the credit bureaus, which usually happens at thirty days past due, your credit score takes a hit. That is where the real cost lives. A late payment stays on your report for seven years. Westlake reports to at least one major bureau, possibly all three depending on your account type and state of residence. The score drop depends on your starting score. Someone with a 720 score will see less damage than someone at 620. But both people feel it when they try to refinance. I ran into a specific edge case that still surprises people. A customer called because she could not figure out why her account was being reported as delinquent when she had submitted a payment the day before. The issue was time zone alignment. Her online payment portal used Eastern Time for cutoffs while her bank account was tied to Central Time. She thought she submitted on time. Her bank processed it late. Westlake flagged it. The workaround was not complicated. I had her request a courtesy removal by explaining the time zone issue in writing through the secure message center. They do not always grant it, but they sometimes do for first-time occurrences. Two years later, that same customer was still getting those reminders from other lenders who pulled her file.
Now let us talk about what actually prevents this from happening. The most reliable method is setting up automatic payments. Westlake allows you to link a checking account and have the minimum due auto-drafted each month. This eliminates the forgetting problem entirely. The downside is that autopay does not protect you if your account is empty on the processing date. A returned payment fee hits just as hard as a late fee, sometimes harder depending on your state. Make sure you verify the auto-pay amount against your budget before you enable it. Another approach that works but gets overlooked is setting up payment alerts. You can configure text or email notifications for upcoming due dates and for when a payment posts. These are free. Most people skip them because they assume they will remember. They do not. I have seen too many people miss a payment because they were traveling and their calendar reminder got buried under trip planning. If you are already late, you have options. Paying the past due amount plus the late fee brings your account current. That stops the bleeding. But the late payment might already be reported if it passed the thirty-day threshold. At that point, the damage is done unless you negotiate. You can call Westlake and ask for a goodwill adjustment. The success rate is low but not zero. It works best when you have a history of on-time payments before the lapse. If you have been late multiple times before, they will deny the request faster. There is no penalty for asking though. One phone call takes five minutes and costs nothing.
Get the Full Details
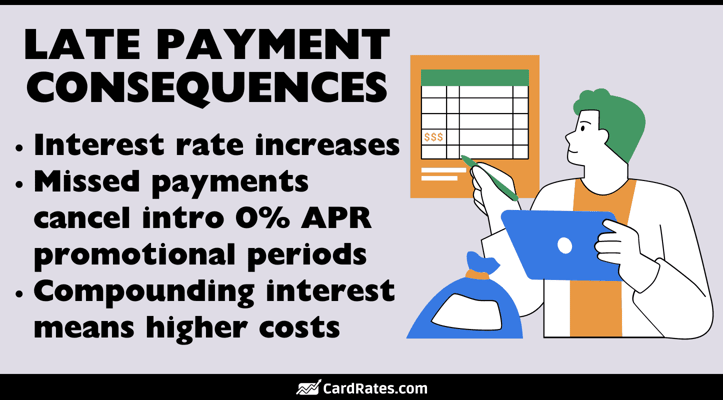
Here is a counter-intuitive point that most people do not know. Paying only the minimum due every month keeps your account current for credit reporting purposes but it maximizes your interest cost over the life of the loan. Westlake loans are installment loans, so the interest is front-loaded in most cases. You pay more interest in the early months. Skipping extra payments to avoid late fees might seem smartbut it makes the loan significantly more expensive overall. If you can afford to pay an extra fifty dollars a month, doing so reduces the principal faster and saves you hundreds in interest. The math is simple enough that I do not need to work it out here. A second nuance involves grace periods. Not all Westlake products include one. Some loan agreements have a grace window of a few days where a payment is not considered late even if it arrives after the due date. Other products start counting late immediately. Your contract will specify whether a grace period exists. If you are not sure, check your original paperwork or call customer service. Do not assume you have one. I have seen people lose money because they assumed a three-day window when none existed. The strongest protection remains a combination of autopay plus a manual check within forty-eight hours of the due date. Autopay handles the forgetting problem. Manual verification catches the insufficient funds problem. You will know immediately if the transaction fails and can move money around before the late fee attaches. This approach cuts the probability of a late occurrence down to near zero for most borrowers.
There are situations where none of this helps. If your income is irregular, autopay is a liability until your cash flow stabilizes. In those cases, calendar reminders and manual payments are your only real tools. Set at least two reminders. One seven days before the due date. One the morning of. Two reminders cost nothing and are more reliable than relying on memory. Westlake also offers a deferment option for temporary hardships, but that is a separate conversation. Deferment extends your loan term and increases total interest paid. It is a trade-off, not a solution. The bottom line is that late payment fees on a Westlake loan are expensive in two ways. They cost you money upfront through the fee itself. They cost you money long-term through credit damage and higher interest exposure. Avoiding them requires minimal effort if you set the right systems in place early. Do not wait until a payment is late to think about it. By then, the fee is already there and your options shrink quickly.