The Real Cost of Moving Money Across Borders
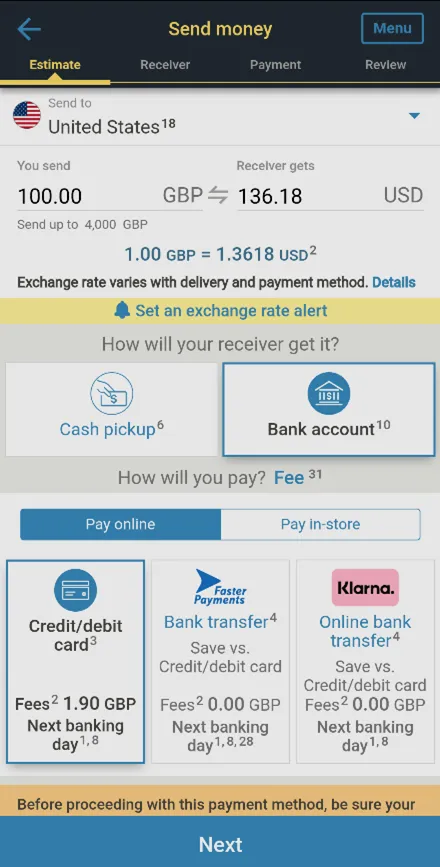
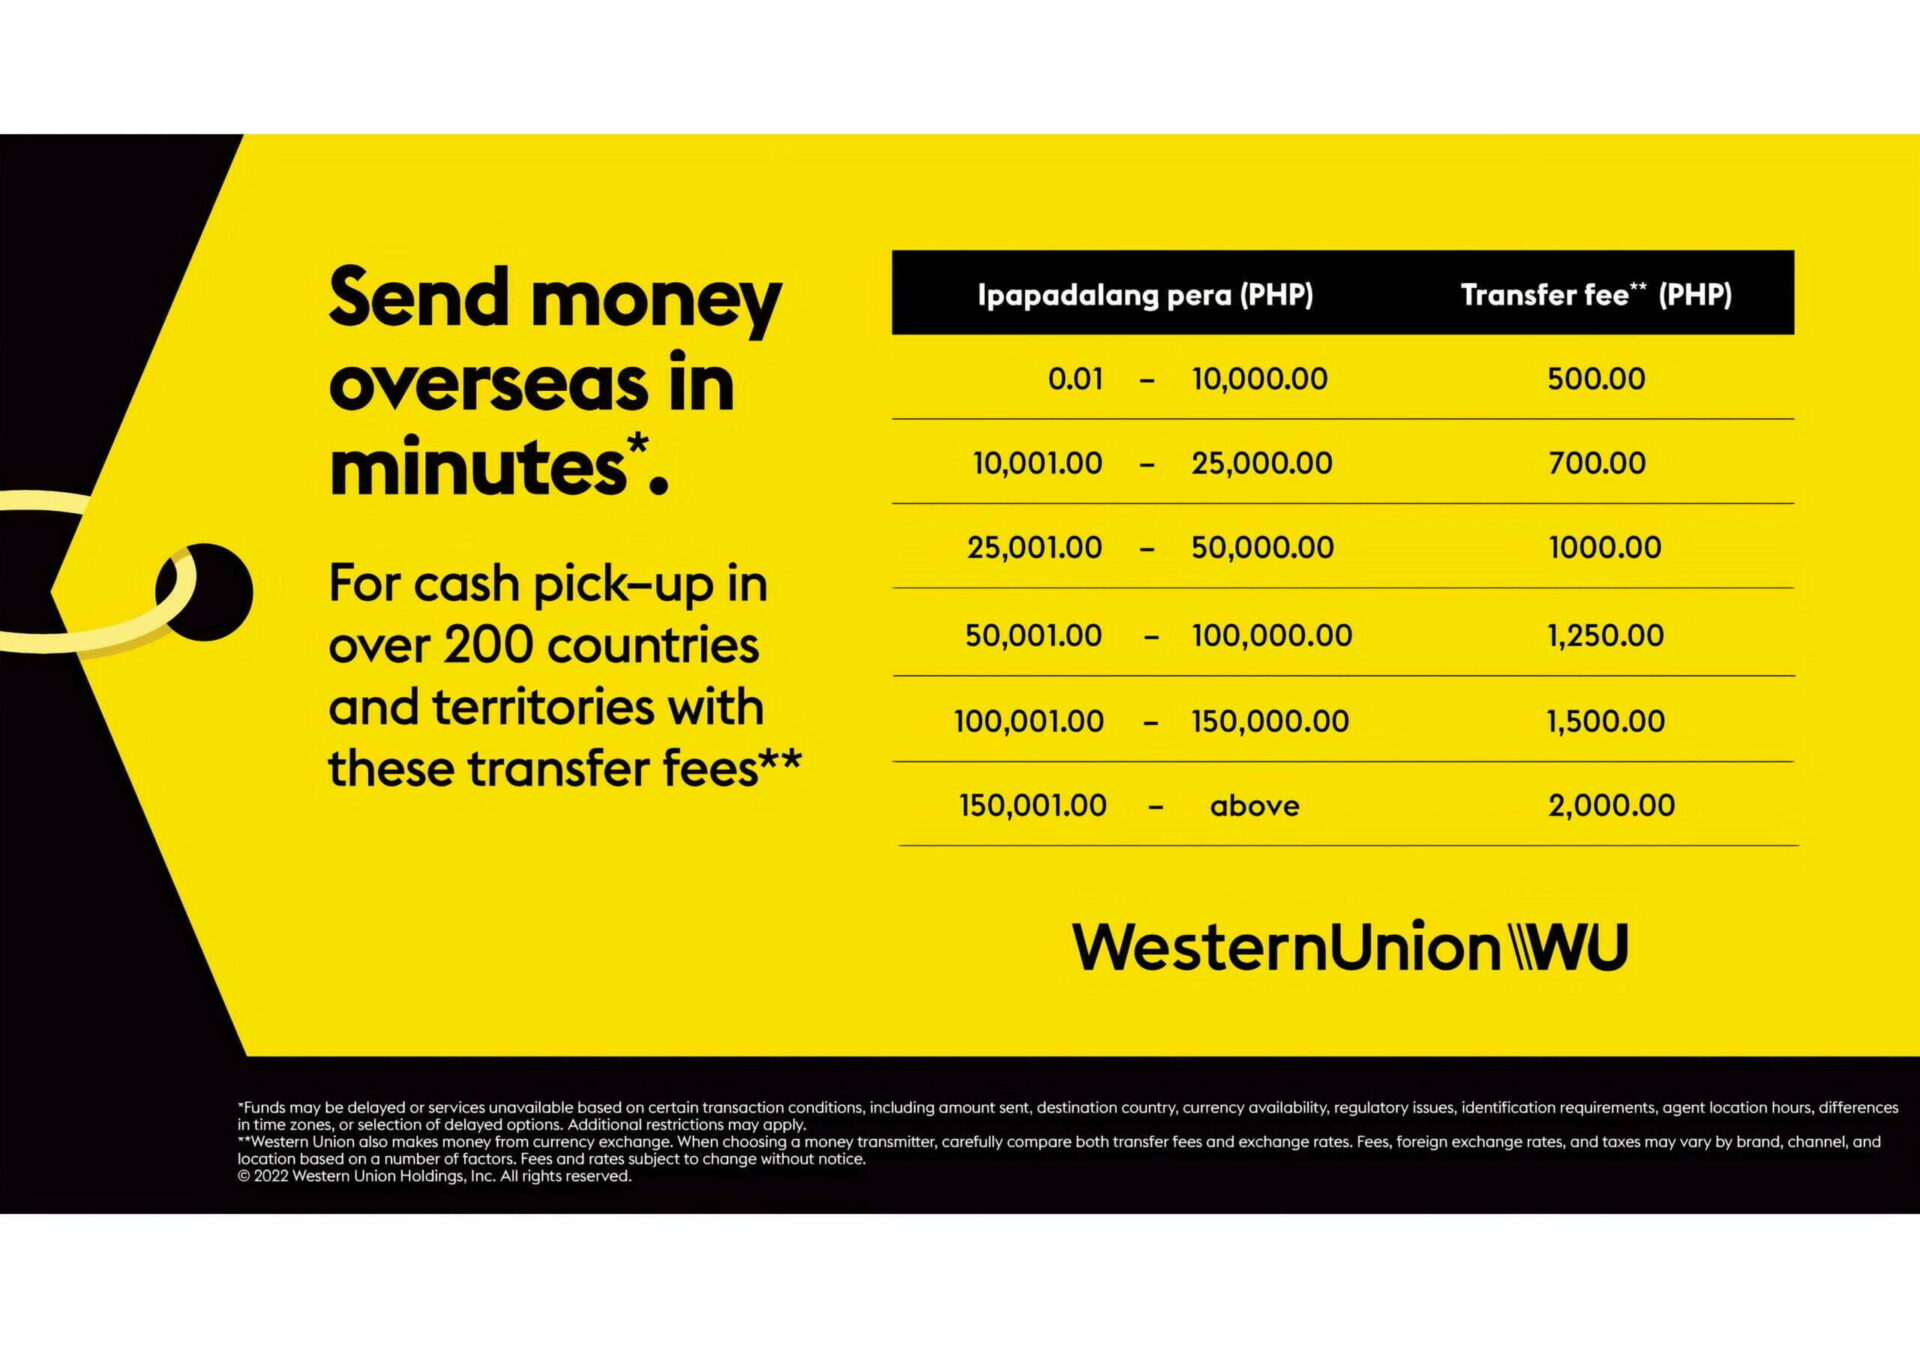
Western Union's exchange rates look reasonable at first glance. You type in a amount, see the rate, and think you are getting a fair deal. That is where most people stop reading and lose money. The rate displayed at the point of sale or on the app is not the mid-market rate. It is a marked-up rate that includes their margin, and on large transfers it adds up fast. Here is how the pricing actually works. When you send money through Western Union, you are paying two separate costs. There is the transfer fee, which varies by country, payment method, and speed. Then there is the exchange rate markup, which is the hidden chunk. For major currency pairs like USD to EUR or GBP, the markup typically sits between 2 and 4 percent. For exotic pairs, it can climb to 8 or 9 percent. I once sent money to the Philippines for a family member and checked the rate against Xe.com. Western Union was offering about 4.2 percent below the mid-market rate on the PHP. On a two thousand dollar transfer, that was roughly eighty-six dollars gone before the money even left my account. The workaround I ended up using consistently is straightforward. I started comparing Western Union's total cost against Wise, Remitly, and Revolut for the same corridor and amount. Wise almost always comes in cheaper for mid-to-large transfers because they use the real mid-market rate and charge a small transparent percentage fee. For a two thousand dollar transfer to the Philippines, Wise was about sixty-five dollars cheaper than Western Union after factoring in both the fee and the rate difference. That is not a typo. Sixty-five dollars on a single transfer.
If you do end up using Western Union, there are a few practical moves. Choosing bank debit instead of credit card usually drops the fee by a few dollars. Paying in advance with a scheduled transfer rather than walking into a physical agent location can save you the walk-in premium. And checking their promotional codes occasionally helps, though the rate markup remains the same regardless.
When Western Union Actually Makes Sense
I am not saying Western Union is always a bad choice. There are scenarios where it is the right tool. If the recipient needs cash pickup within minutes and you cannot wait for a bank transfer to clear, Western Union still moves fast. In parts of Africa, Latin America, and rural South Asia, Western Union agent networks reach places that digital-only services simply do not cover. If your recipient is an elderly relative who does not use a smartphone or bank account, the cash pickup option is genuinely useful. The speed is real, not marketing inflation. Most cash pickups complete within ten to thirty minutes at a physical location. Another edge case is emergency transfers where you have already logged into the Western Union app and verified your account. Setting up a new account with Wise or Revolut takes time, identity verification, and linking a bank account. If you need money across the border in the next hour and cannot wait two days for onboarding, Western Union is the default option. Just accept that you are paying a convenience premium, which in this case runs about 3 to 5 percent depending on the corridor.
Get the Full Details

The Numbers Breakdown
Let me walk through a concrete example. Say you are sending one thousand five hundred US dollars to Mexico in pesos. The mid-market rate on a given day might be 17.20 MXN per dollar. Western Union might offer you 16.55 MXN per dollar after their markup. That is a difference of 0.65 pesos per dollar, or about 3.78 percent. On fifteen hundred dollars, you lose roughly fifty-seven dollars in value compared to the real rate. Wise in the same scenario would give you the 17.20 rate and charge around six dollars in fees. The gap between the two options is about fifty-one dollars on this transfer. On larger amounts, the gap widens dramatically. Send five thousand dollars to India through Western Union and you could be looking at two hundred dollars or more in hidden costs. Same amount through a low-cost remittance service and the total cost drops to maybe thirty or forty dollars including fees. The math does not lie, but it also does not appear prominently in Western Union's marketing materials.
Things People Miss About the Rate Display
Western Union shows you the exchange rate on their app and website, but they do not show you the mid-market rate alongside it. This is by design. Most people do not know what the mid-market rate is, so they accept the displayed rate without question. A useful habit is to pull up the current mid-market rate on a site like Xe or OANDA before you confirm any transfer. Compare the two numbers quickly. If Western Union's rate is more than one percent away from the mid-market rate, you are being overcharged on the spread alone, regardless of what their fee schedule says. Another thing nobody mentions is that Western Union changes rates frequently throughout the day. The rate you see at 9 AM might be different from the rate at 2 PM. Currency volatility matters here. If you are sending a large amount and the rupee or the real is moving, locking in the rate early through their rate lock feature can save you money. Not always, but often enough that it is worth checking before you commit.
Alternatives Worth Considering
Wise remains the strongest option for most people sending money through bank channels. They use the mid-market rate, charge transparent fees, and deposits usually arrive within one to two business days for major corridors. Revolut works similarly for subscribers, though their free tier has monthly limits that kick in around five hundred pounds or dollars depending on the plan. Remitly has competitive rates for specific corridors, especially toward the Philippines, India, and Central America, and they sometimes run promotions that beat Wise on price for first-time users. PayPal can be competitive for small transfers between people who already have accounts, but the fees are steep for anything above a few hundred dollars. Its exchange rate markup is also around three percent, which puts it in roughly the same ballpark as Western Union, minus the physical agent network. If you are comparing purely on cost for a digital transfer, PayPal is not the answer for large amounts. Safari's recommendation is to never assume the first rate you see is the best available rate. Pull up at least two alternatives before confirming a transfer over five hundred dollars. Ten minutes of comparison shopping saves real money. Western Union is fine for urgent cash pickups and hard-to-reach destinations. For everything else, especially regular transfers, the math heavily favors services that quote the mid-market rate and charge a visible fee instead of hiding the cost inside a bad exchange rate.